Summary
- The SEC proposes a five-business-day minimum for one preparatory step before a shareholder voting record date, down from the general twenty-day rule.
- Banks and brokers can still take seven business days to supply the figures the company requests. The SEC is considering whether to shorten their deadline too.
- Investors who have lent shares may have less time to get them back for voting. The proposal remains open for comment, not adopted law.
A deal to approve, a director to choose
A shareholder may want a new board. A company may want a deal approved before markets turn against it. Both need a vote, but they do not necessarily want the same calendar.
For the company, waiting can mean another day of uncertainty over a transaction. For an investor who has lent out shares, a few extra days may be needed to get them back and vote. The SEC's proxy-modernisation proposal puts those competing needs into an unexpectedly simple arithmetic problem: five days to prepare, potentially seven days for an answer.
Start with the question being asked. When investors hold shares through banks and brokers, the company needs to know how many customers require voting papers and how many copies to provide. It asks the institutions in its shareholder records. This is the broker search—not a hunt for a broker, and not a count of votes.
The SEC would let companies send that inquiry as little as five business days before the record date, instead of the general twenty-business-day minimum in Rule 14a-13. The record date fixes voting entitlement. It is not the meeting day or the deadline for returning a ballot. Shareholders are not being told to cast their votes within five days.
The reply that misses the company's schedule
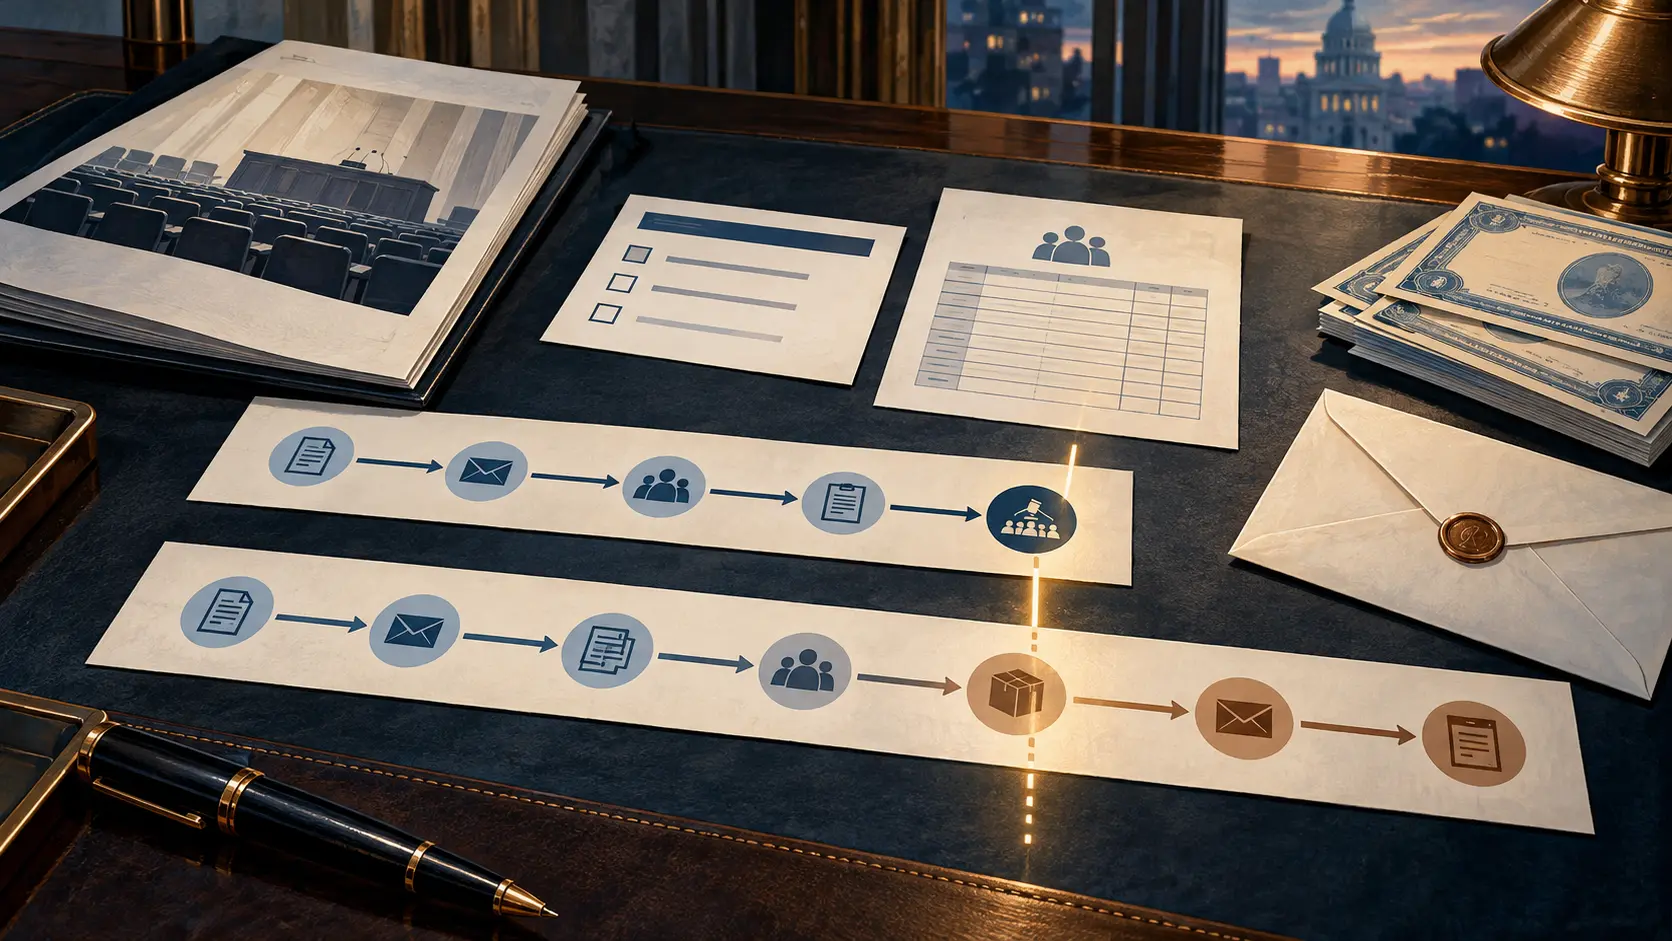
Here is the awkward part. A broker can currently take seven business days after receiving the inquiry to give an approximate customer count. Banks have seven days for their counts too. If a company chooses the proposed five-day minimum and its intermediary uses all seven days, the answer can arrive after the record date.
That is a scheduling example, not a report of lost votes. It does explain the practical bind: the company wants to arrange the papers while a permitted answer about how many are needed remains outstanding. Starting earlier gives it room, but eats into the saving. The SEC explicitly acknowledges that limitation.
One option is to reduce count responses to three business days. A separate bank duty—naming other banks that hold securities through it—would remain at one business day under that alternative. The one-day step does not identify every individual shareholder. None of these changes is settled, and companies could choose a longer lead time than five days.
Whose days are being saved?
The SEC's case for speed is that electronic searches can often finish in three days, according to staff's understanding. It wants less transaction delay and quicker preparation in contested director elections. That is a reason to reconsider an old timetable, not proof that every inquiry runs smoothly.
For share lenders, learning the record date later may squeeze the time available to recall stock. The SEC says earlier public notice or a voluntarily longer search could help. The effect is uncertain; a shorter search does not automatically deprive an investor of a vote.
There may be benefits for investors too. A shorter interval could reduce opportunities to exploit non-public knowledge of the date, or borrow shares to gain votes while bearing little economic exposure. On that latter practice, known as empty voting, the SEC says the research is mixed and the potential gain uncertain. Ordinary securities lending is not itself evidence of abuse.
Our earlier account also missed existing flexibility. Staff guidance dated 23 January 2026, question 133.02, permits a shorter search without staff objection if the company reasonably expects timely distribution to beneficial owners and otherwise complies with the rule. There is also an existing practicability exception for special meetings. Twenty days was not an absolute wait in every case; those qualifications do not make the new five-day proposal law.
The S7-2026-33 docket was released on 16 September, published in the Federal Register on 21 September and accepts comments until 20 November 2026. The fact sheet covers other changes to annual-report delivery, incorporation by reference, certain exempt-solicitation filings and contact details. The shareholder-proposal proceeding S7-2026-32 is separate.
A faster deal and a prepared shareholder are not incompatible aims. But the useful saving is time nobody needed—not time somebody else still needs to get the papers, recover the shares and have a say.
Member Briefing
Read the full trend briefing
Members read the full briefing with the source notes behind every finding.
Strategic Circle
A daily briefing in your language, built from changes we have verified.
Join for USD 20/monthCancel anytime.
Members also get the full research library, a daily briefing on the networks they follow and the private forum.