Summary
- Iron Mountain's Q2 2026 supplement records $262.871 million in data-centre revenue and $472.002 million of data-centre growth capital expenditure in the same quarter. Construction is consuming capital now; newly completed capacity earns rent later.
- The June Form 10-Q reports $887.813 million of group operating cash over six months, $1.106206 billion of cash capital spending and $532.7 million of common dividends. Management raised debt, repaid other borrowings and used project-level financing during that period.
- The company's operating portfolio was 528.5 MW and 97.1% leased at 30 June. Another 160.2 MW was in its development table, including 114 MW pre-leased. Pre-leasing fixes a customer commitment; energization and commencement determine when the new rooms start paying.
The construction invoice arrived ahead of the new rent
Iron Mountain's second-quarter data-centre business took in $262.871 million and produced $137.343 million of adjusted EBITDA. Revenue rose 38.8% from a year earlier. It was hardly an empty shell waiting for its first tenant. Yet the same company supplement lists $472.002 million of growth investment in data centres for the quarter. That is roughly 1.8 times the segment's current quarterly revenue.
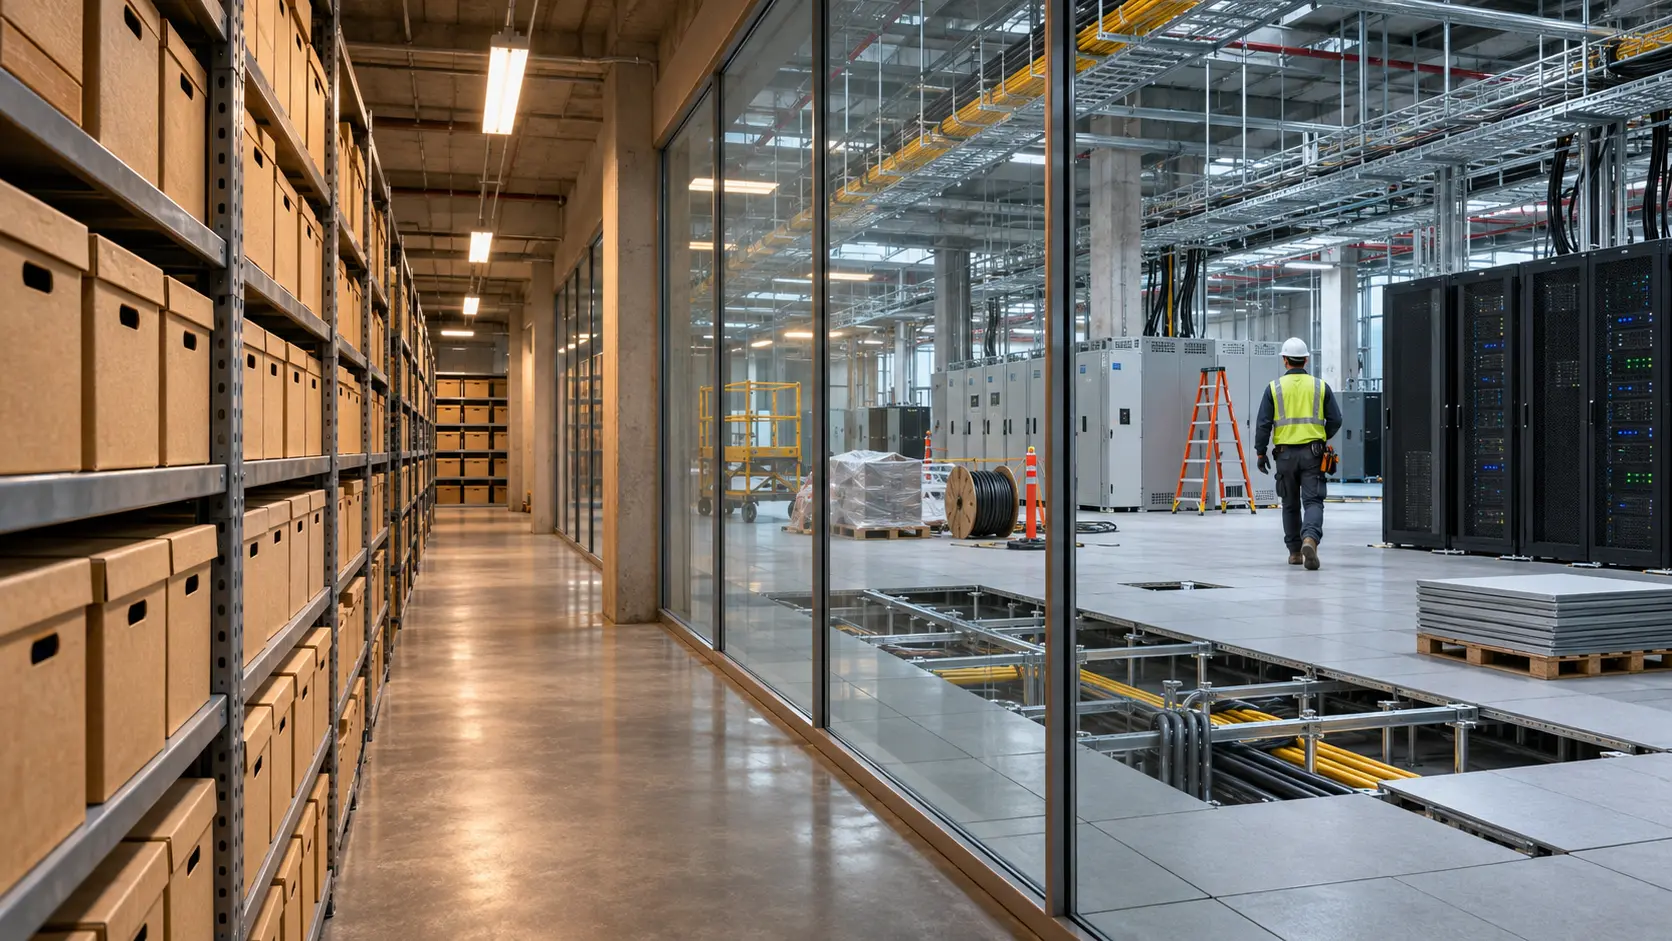
Those figures measure different things. Revenue came from customers already using data-centre space and services. Growth capital buys land, construction and equipment for capacity that will be billed later. The comparison exposes a timing choice: Iron Mountain is directing substantially more current capital into its future data-centre estate than that estate presently earns in a quarter. It has to keep the cash and financing bridge intact while concrete and power gear turn into rented megawatts.
The older records-management franchise gives scale to that decision. Global RIM, the company's records and information management segment, reported $1.433562 billion of quarterly revenue and $620.751 million of adjusted EBITDA. The data-centre segment reported $262.871 million of revenue and $137.343 million of adjusted EBITDA. Iron Mountain's filings report pooled group cash flow rather than a dollar-by-dollar transfer from document storage to a named server hall. The business, however, plainly carries both a long-established rent stream and a much younger construction schedule under one capital-allocation roof.
Six months of cash flows show the bridge in motion
In the first half of 2026, Iron Mountain generated $887.813 million of cash from operations and paid $1.106206 billion for capital expenditure, according to its Form 10-Q. The simple gap was $218.393 million before other investing activity and before $532.7 million of dividends. On an accrual basis, $880.086 million of the $1.118122 billion total capital spend was data-centre growth investment, about 79%. That share explains why the buildout dominates the allocation conversation even though records management remains the larger revenue business.
Management did not leave the funding column blank. During the half-year, it received about $1.485 billion net from 6.25% notes due in 2035. It also reported roughly $621.2 million of net payments, mainly on its revolving credit facility, partly offset by borrowings on data-centre credit facilities. Financing cash flow was a net $303.985 million. These are movements across a group with older debt, shareholder distributions and several capital projects. The notes proceeds cannot be assigned wholesale to new data centres; their existence shows the balance sheet working through the construction cycle.
One project makes the financing terms concrete. Iron Mountain's Virginia 9 subsidiary signed a facility allowing up to $298 million of term loans at SOFR plus three percentage points, with a 0.90% fee on unused commitments. At 30 June, only $29.595 million was outstanding, at a 6.9% rate. The project sits in a consolidated joint venture; the filing recorded about $49.9 million of non-controlling interest, and the supplement says the venture funds construction while Iron Mountain manages it. The unused loan capacity is a priced option to draw, not a pile of cash already in the account.
The megawatts have several dates, and the dates matter
The operating data-centre portfolio had 528.5 leaseable MW and was 97.1% leased by MW at 30 June. The development table listed another 160.2 MW in development, 114 MW of it pre-leased. Virginia 9's two 14 MW phases were fully pre-leased, with expected completions in the fourth quarter of 2026 and first quarter of 2027. A 24 MW future phase in Chicago was also pre-leased, but the supplement says construction on that line had not commenced.
A signed lease removes one commercial uncertainty. Contractors, power availability, commissioning and the contractual start of rent set the cash timetable. The supplement's expected development-investment total explicitly excludes costs for pre-leased capacity where work has not started. Counting every signed megawatt as operating capacity would give investors an extra building for free.
Iron Mountain expected about $2.2 billion of total 2026 capital expenditure as of the June filing, excluding possible acquisitions. The current company cash engine, debt market, project lenders and venture partners all have a claim on how that ambition is funded. The strongest evidence of success will be completed rooms that begin billing at a rate and time capable of carrying the capital already committed. For now, the company's own tables show a fast-growing business whose next wave of rent requires another large invoice first.
Primary documents
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance