Summary
- WIOCC describes substantial stakes in African subsea infrastructure, including a fibre pair on Equiano. System design, equipped capacity and a customer's order are different quantities.
- Public records explain much of the business and its financing. They do not replace a route-specific agreement covering delivery, inland connectivity and restoration after a fault.
An internet provider preparing to connect its customers needs a date it can plan around. A vast cable is little help if the connection it has ordered stops at the shore, short of its own network. That is why the useful question about WIOCC is not just how much bandwidth sits beneath the sea, but who can bring it the rest of the way.
WIOCC's Equiano page gives that question a concrete starting point. It describes a cable system designed for 144 terabits per second: twelve fibre pairs at 12 Tbps each. WIOCC says it owns one pair. The system's total is not a pool of bandwidth that a customer can simply order from this supplier.
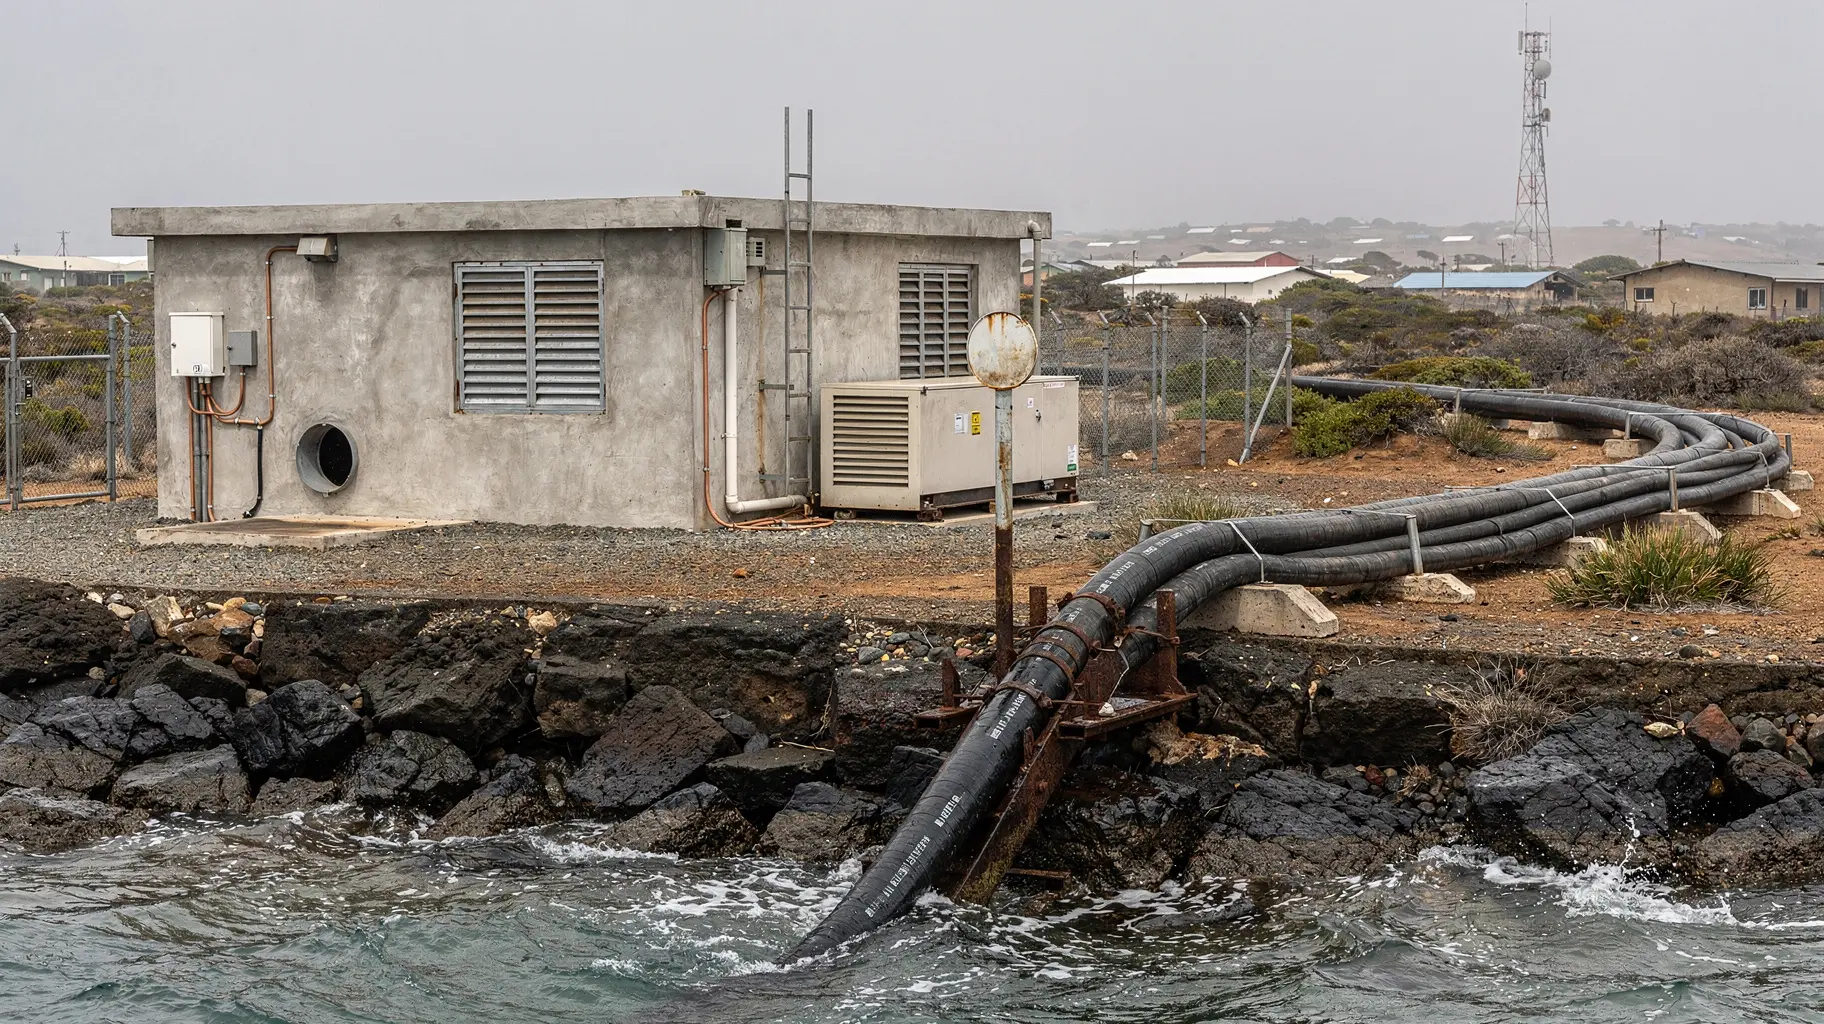
The more revealing detail appears alongside it. WIOCC says it owns one pair and controls the submarine line terminating equipment used to light and upgrade its capacity. That is a specific role in making a cable useful, rather than merely a claim to be connected to it. At the Nigerian end, the company identifies Open Access Data Centres Lagos, a WIOCC Group company, as the Equiano landing station.
For an internet provider buying international connectivity, these details begin to answer a harder question than “How big is the cable?” Who can deliver the service, and how far does their responsibility run?
The sea is only part of the route
WIOCC sells wholesale connectivity to operators, cloud businesses, content providers and ISPs. It is a company within WIOCC Group, not a convenient alternative name for every business in that group. Its customers need connections that carry on beyond the shoreline to their own networks and facilities.
WIOCC's core-network description identifies it as the largest investor in EASSy, a strategic investor in WACS and EIG, and a fibre-pair owner in Equiano and 2Africa. Its EASSy page describes a 10,000-kilometre east-coast system with landings in nine countries, from Sudan to South Africa. These are company descriptions of infrastructure and ownership roles, not an independent measurement of a customer's circuit. They are nevertheless considerably more informative than an anonymous capacity total.
Owning terminal equipment matters because someone must equip and activate the fibre before it carries a service. A landing facility must also have the access and terrestrial connections needed to reach the buyer's delivery point. Applicable permissions and the commercial agreement have to cover that service. These functions need not belong to three unrelated organisations: WIOCC's equipment ownership and the group relationship with OADC are reasons to examine the actual arrangement, not impose a tidy three-party diagram on it.
Integration can put more of that work within the same group. It does not tell us, by itself, whether a particular inland connection is ready or what happens to a particular customer's traffic after a cable fault.
Five meanings hidden inside “capacity”
Start with the equipment. Design capacity describes what the system is engineered to support under stated technical assumptions. Lit capacity is the part that installed equipment has actually brought into service. A plan for carrying data and a working connection are different things.
Then consider who holds the rights. Capacity can be allocated to owners or other rights-holders without that telling us how much has been contracted to customers. Allocation answers whose share it is; contracting answers what has been promised to a buyer.
Deliverable capacity takes the final step: a service the buyer can use at the agreed point and date. It brings the discussion back to the provider waiting to connect its own network.
None of those numbers should quietly stand in for another. Equiano's 144 Tbps is labelled as system design. WIOCC advertises offerings from 1 Gbps to 1 Tbps on the same page, but a product range is not confirmation of stock on a chosen route. EASSy's displayed 10 Tbps total is not clearly labelled there as lit, contracted or available to a new buyer. Calling it any of those would add certainty the source does not supply.
A buyer can therefore take the infrastructure seriously while asking for a narrower answer: this service, between these points, starting on this date. A private quotation may supply it. Its absence from a public website does not show that the supplier cannot deliver.
There is a financing record, too
In August 2020, IFC announced a $20 million loan intended to support WIOCC's capacity upgrades and terrestrial fibre expansion. The underlying project disclosure, 44202, names West Indian Ocean Cable Company Ltd, describes incorporation in Mauritius in 2007, and sets out an estimated $133.3 million working-capital and capital-expenditure programme for FY20–FY21. It describes an IFC A loan of up to $20 million.
The disclosure records approval on 24 July 2020, signing on 29 July and an “invested” milestone on 21 August. Those are useful dated facts, not a current loan balance or an itemised account of where every dollar went. Nor does financing wholesale infrastructure establish that retail internet prices subsequently fell.
The broader group has since announced another transaction. Its 1 September 2026 statement reports a shareholder subscription agreement with Africa Finance Corporation and Vision International Investment Company for a combined $300 million investment. The stated priorities span data centres, terrestrial fibre and subsea assets. This is group-level investment news, separate from the 2020 loan; the announcement alone is not a bank receipt or a timetable for a customer's connection.
Routing data answers a different question again. A RIPEstat historical observation shows routes originating from AS37662 at 16:00 UTC on 17 October 2026. It does not measure how much Equiano capacity WIOCC owns, sells or delivers. The BTW directory entry Only for Strategic Circle provides company context, not independent confirmation of those quantities.
The useful picture is neither an empty promise nor a finished purchase order. WIOCC describes assets, equipment control and group facilities that explain how its service can be built. Public financing records add substance to that account. The remaining test is smaller, and closer to the customer's business: does the agreed connection reach the place where it is needed, when it is needed, with a workable answer if the route fails?
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance