
Summary
- The Spanish competition and telecom regulator maintains a public case file on the wholesale broadband market, and its own press page describes access obligations kept where competition is judged insufficient and relaxed or withdrawn in municipalities classified as competitive. Neither page was read as decision text in this review; both are retained as descriptions.
- The only figure in the retained record is market-wide: 18.02 million FTTH lines in a market where Digi ranks third among fixed operators, dated 17 September 2026. That is not an operator's footprint, and it says nothing about how many lines are sold at retail rather than wholesale.
Spanish fixed broadband is usually narrated as arithmetic: lines, households, rankings. The documents that decide the money belong to a different class, and in this review they were not readable.
What is readable is the existence of the file. On 18 October 2026 the Spanish competition and telecom regulator, the CNMC, maintained a public case file on the wholesale local access market, the market in which rivals buy the use of an incumbent's network instead of digging their own, at https://www.cnmc.es/expedientes/anme2021003. The address resolves and the page exists, but the retained record carries no title, no dated document and no quoted wording. It carries a description of what the file concerns.
The regulator's press page does something similar in its own web address: it announces approval of the regulation of the broadband market 3/2021 at https://www.cnmc.es/notas-prensa/la-cnmc-aprueba-la-regulacion-del-mercado-de-banda-ancha-3-2021. The retained text is again a description, written in Spanish, not a decision. Read as descriptions, the two records agree on direction: access obligations are kept in areas where competition is judged insufficient, and relaxed or withdrawn in municipalities the regulator classifies as competitive.
That direction is worth having, because it is the only content the record supplies. It is not a product definition. It is not a schedule. It is not a price.
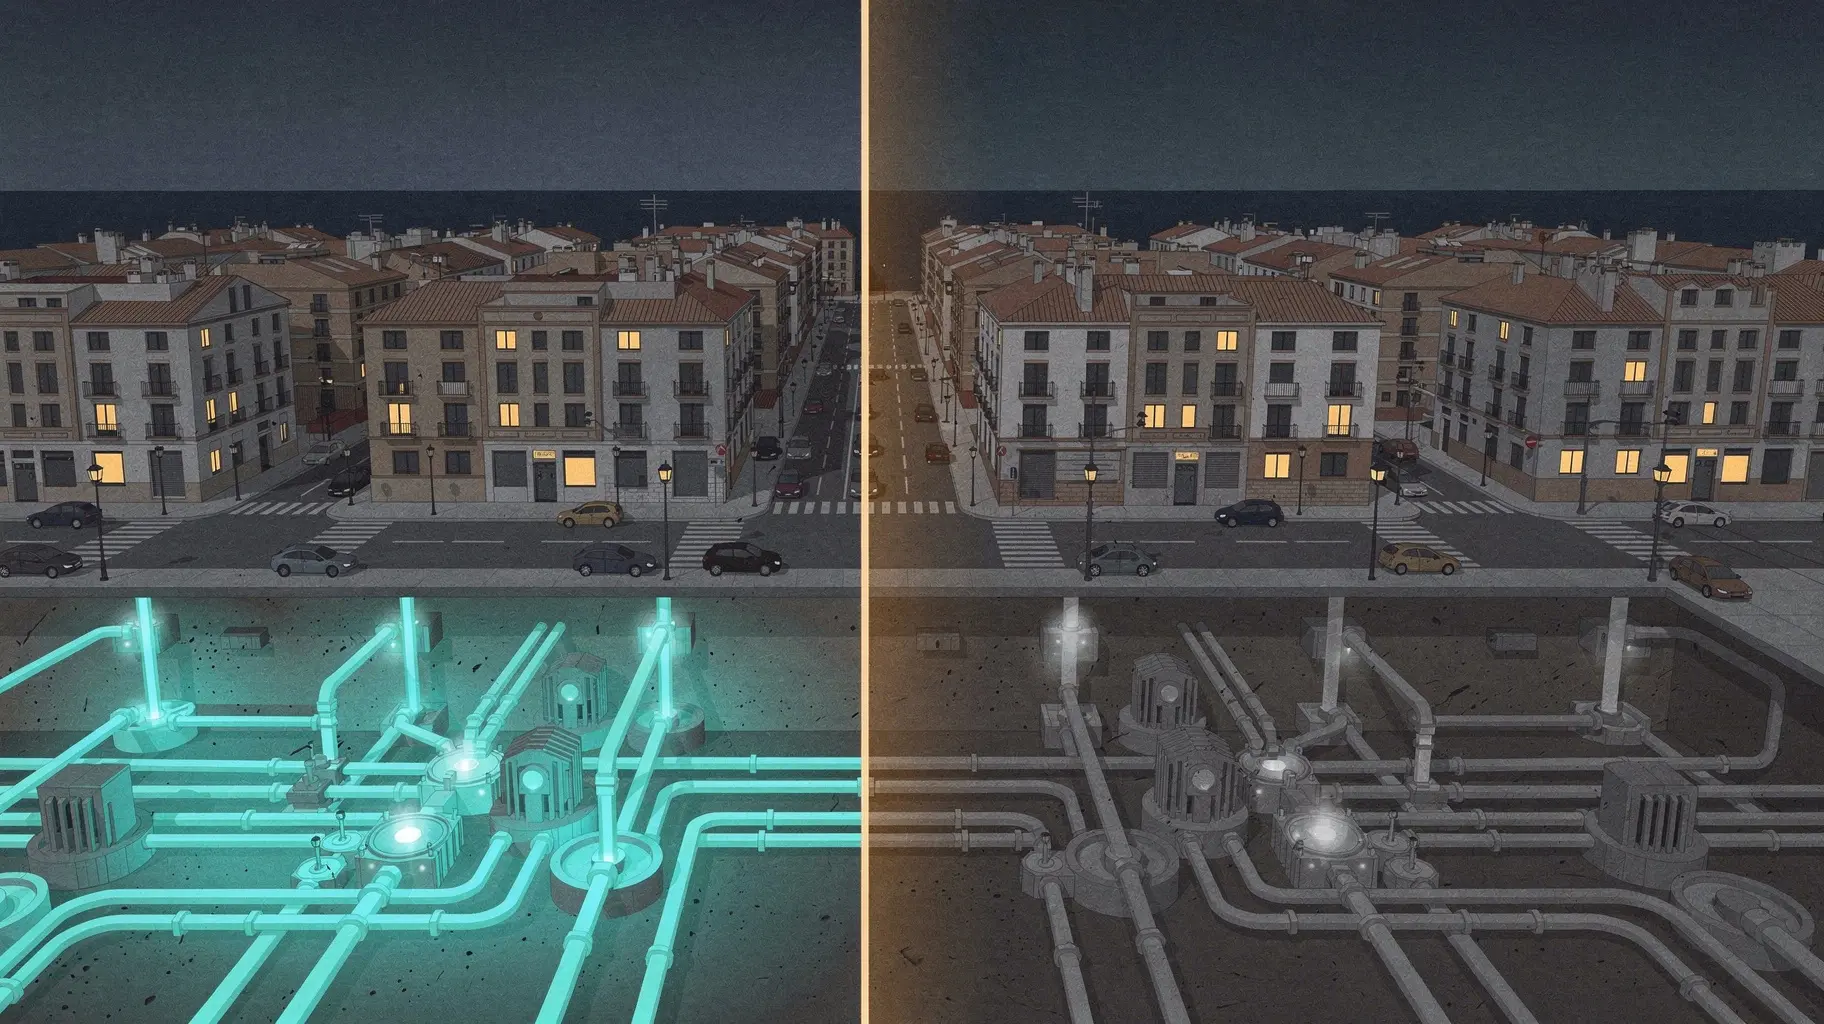
This is where the sector's vocabulary does damage. Coverage, lines and price get treated as one number wearing several hats, and the hats are not interchangeable. A duct is a fact about construction. A line is a fact about demand. A regulated access price is a fact about an instrument. None of them substitutes for another, and the record supplies only the middle one, at national scale.
The figure itself is specific and limited: 18.02 million FTTH lines in a market where Digi holds third position among fixed operators, reported on 17 September 2026 https://www.elespanol.com/invertia/empresas/tecnologia/20260917/telecos-superan-millones-lineas-fibra-optica-rozando-numero-hogares-espana/1003744386898_0.html. The words carrying the weight are market and lines. A national count is not an operator's footprint. Premises passed are not connected households. A line sold at retail is not a line sold wholesale. Nothing in the record states which of these the count measures, and no homes denominator is offered to divide it by.
The operator's own numbers were not obtained either. The group's investor-relations results page was retrieved and returned no extractable operational figures https://www.telefonica.com/en/investors/financial-results/: no premises passed, no retail line count, no wholesale access volume, no revenue split.
So the record holds a regime indicator and a market count, and lacks the regime's operative terms and any operator-level quantity. The gap is not academic. Where a market analysis decides which lines must be offered to rivals and on what conditions, the same physical network carries different unit economics in different municipalities. A review can change revenue per line without a metre of duct being built or abandoned. A coverage claim cannot show that, and neither can a line count.
The entity question compounds it. TELEFONICA DE ESPANA S.A.U. is the company this briefing covers; it is recorded in the RIPE NCC public member directory with Spain-based service-area context https://www.ripe.net/membership/member-support/list-of-members/es/telefonica/, and that record states explicitly that it is not proof the entity sells any particular service and provides no ownership map. Telefonica is the operator the regulator's descriptions name as carrying the access obligations. Digi is the rival named in the press record for its ranking, not for any access volume. Which legal person holds the ducts, and which books the wholesale revenue, stays unresolved in this record. Because the answer decides whether a regulated-wholesale exposure sits on the company covered here or somewhere above it, it belongs in the open rather than in an assumption.
The boundary, stated plainly: this briefing is written on the public record as retrieved on 18 October 2026, and it is a reported account, not a reading of a decision. It states no operative article of a resolution, no price-control finding, no effective date, no municipality list, no premises-passed figure, no retail-line count, no wholesale volume and no filed-account segment as fact. The directory record for the subject is here: https://btw.media/en/directory/telefonica-de-espana-s-a-u-es.
What would settle it is unglamorous and specific. A published resolution text with a product definition, a price or a pricing methodology and an effective date. A filed account that breaks out wholesale access revenue and volumes. A market-analysis revision that adds or removes a municipality. Any of those turns a description into a parameter.
Until then the honest reading is narrow. Spain's wholesale broadband regime exists, is publicly documented and is drawn along geographic lines. The national market counts 18.02 million FTTH lines. The price at which that network is sold to rivals, the volume actually sold and the company that books it are absent from the record this review could read, which means the coverage map is not yet an earnings model and the remedy's existence is not yet a cost.
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance