
Summary
- YarTranzitTelecom's public economics look more like a small neutral data-centre and access node than a mass-market ISP: 2024 revenue of about RUB 31.9 million, thin staff numbers, advertised cabinet, cross-connect, VPS, dedicated-server and reserve-site services, and a Yaroslavl facility marketed as carrier-neutral.
- The unit that matters is not an abstract subscriber but one paid transport or hosting relationship. A customer buying a cabinet, power, a local cross-connect, remote hands and access to a carrier path creates retained spread only after power, cooling, route, equipment and support costs are covered.
- Public routing evidence is unusually important and unusually messy. Several mirrors still describe AS16047 and two IPv4 blocks as YarTranzitTelecom resources, while newer mirrors show AS16047 registered to Scientific-Production Enterprise Business Sviaz Holding LLC after a June 2026 RIPE-side update. That is a control-boundary risk, not a cosmetic registry footnote.
- The company's market problem is local substitution. Its site lists many national and regional carriers available in the facility, which helps sell neutrality, but the same list also reminds large customers that they may be able to buy directly from those carriers if YarTranzitTelecom's bundle is not cheaper, simpler or more reliable.
- The investment judgment turns on utilisation and renewal evidence: occupied cabinets, committed kilowatts, paying cross-connects, route diversity, customer concentration, current licence status after August 2026, and a clear explanation of who controls the AS16047 address and routing assets now.
Start with one paid transport circuit. A customer in Yaroslavl needs a cabinet, a few units of rack space, or a remote site that can connect to a chosen carrier. YarTranzitTelecom can charge for the physical place, the power envelope, the cable entry, the cross-connect, the switch port, remote hands, and sometimes the server or virtual-machine layer above it. That gross bill is not the company's economic profit.
The retained spread is what remains after the facility has paid for electricity, backup power readiness, precision cooling, upstream or partner capacity, switch and router depreciation, licence compliance, staff time and the capital cycle needed to keep an old local data-centre offer credible.
That framing matters because the public record does not show a high-growth platform. It shows a small, specialised operator with a fixed-site business. Company registries identify Limited Liability Company YarTranzitTelecom, commonly shortened as YarTT, as a Yaroslavl limited liability company registered in March 2015, with the legal address on Pobedy Street 16B and a main activity classified as telephone-communication services.
The public financial picture is small: 2024 revenue is reported at RUB 31.944 million, up from about RUB 29.35 million in 2023, with 2024 net profit around RUB 2.3 million and gross profit around RUB 10.0 million after cost of sales of about RUB 21.944 million. Depending on which registry mirror is used, the employee count appears as six or seven people. Either way, this is not a labour-heavy retail operator. It is a compact infrastructure business whose performance is sensitive to a few large contracts, a few cabinets, and a few supplier terms.
The advertised product set confirms that. The company's own site presents a Yaroslavl data centre near the central part of the city, claims Tier-3-level reliability with 99.982 percent predicted availability, and says the facility is neutral and open to cooperation with all operators. It advertises colocation, dedicated servers, VPS/VDS, reserve data-centre arrangements and data-centre maintenance. The company also says ordinary hosting stopped from 1 January 2025. That exit is important. Shared hosting at low monthly prices can fill space, but it also produces small tickets, high support friction and commodity competition.
If the company is moving away from classic hosting while retaining colocation, dedicated, VPS and managed-site services, then the revenue model is being pushed toward fewer, higher-value infrastructure relationships. The question becomes whether those relationships are dense enough to carry the fixed plant.
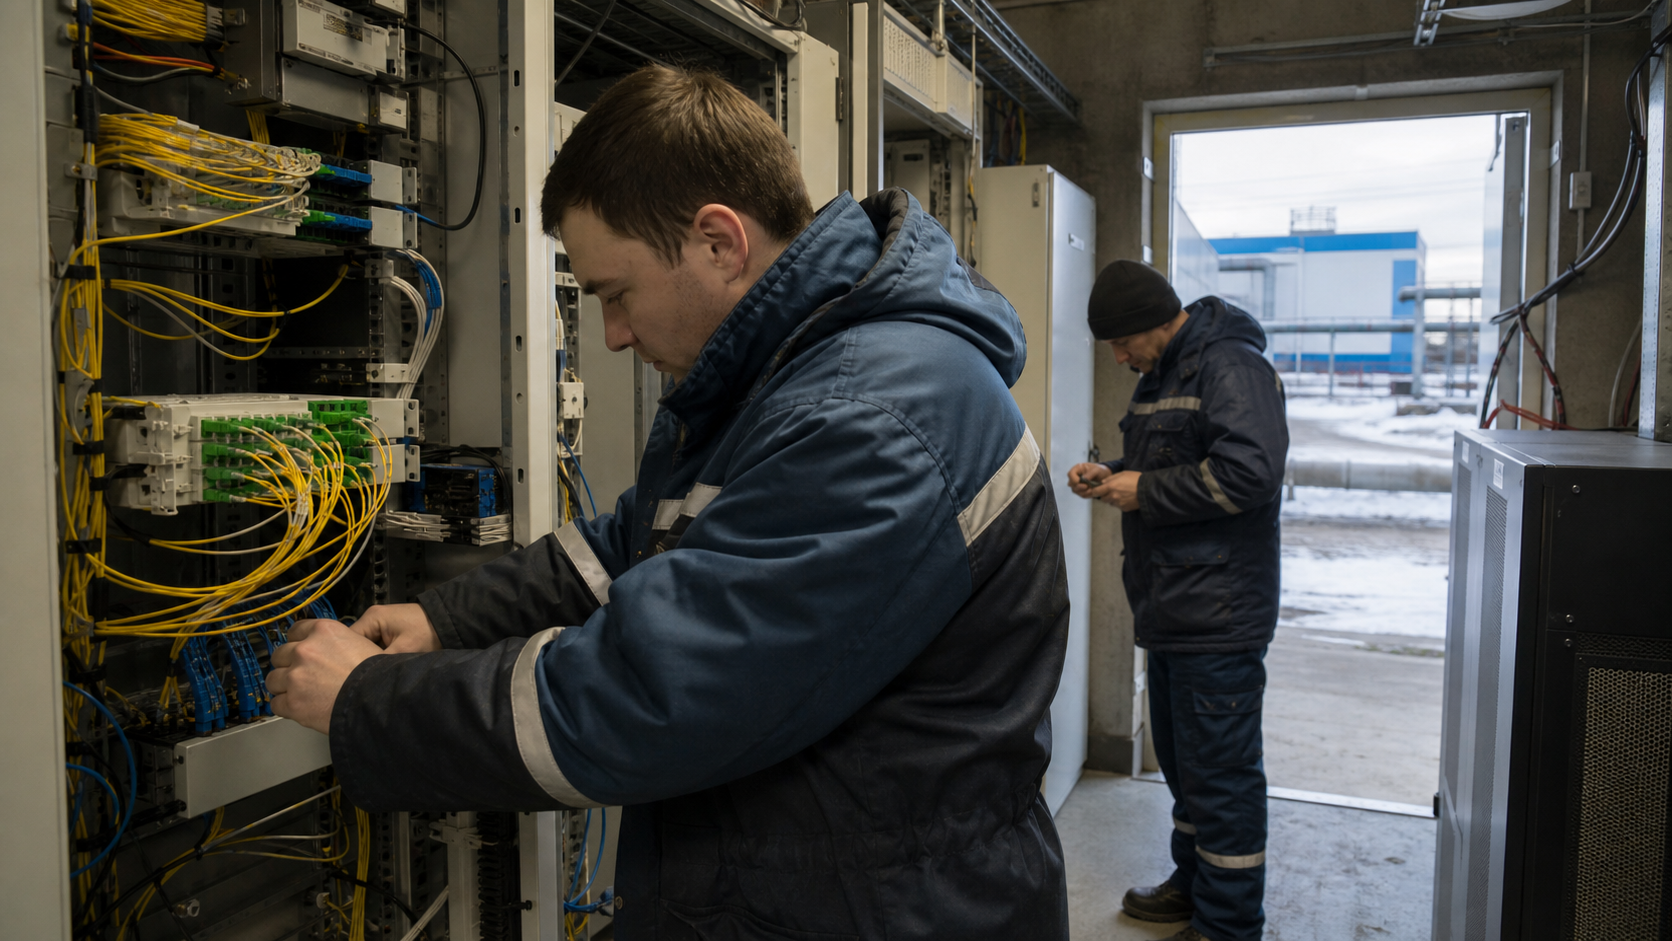
The plant is modest but real. The infrastructure page describes 150 square metres of technology space in the first stage, 150 kW of current allocated power, a diesel generator, the possibility of up to 100 telecom cabinets in a fourth stage, fibre entry into the building, fibre lines to main telecom operators, a YAR-IX access node, and round-the-clock engineer or duty-shift support. The home page adds that a third sealed room was commissioned with 12 telecom cabinets of 42U each and two Airedale precision air-conditioners with total cooling capacity of 80 kW. Those numbers are enough to make the economics concrete.
At 150 kW of allocated power, a theoretical estate of fifty 3 kW cabinets would already consume the full stated power allocation before cooling overhead, losses, office loads or reserve margin. The advertised potential for 100 cabinets therefore reads as staged capacity, not as currently monetisable 3 kW-per-cabinet inventory.
Pricing makes the same point. The colocation page says a standard 42U cabinet or rack space up to 3 kW carries a monthly payment of RUB 68,000, with one-time payments around RUB 40,000 for a cabinet and RUB 20,000 for a rack-place scenario. Larger or higher-power footprints move to at least RUB 90,000 monthly. Extra guaranteed power is advertised at RUB 10,500 per kW per month, and power through uninterruptible supply at RUB 13,500 per kW per month. Placing one unit in a YarTT rack ranges from RUB 1,100 per month for passive gear to RUB 10,400 for a high-power unit, with extra power charged at RUB 1,350 per 100 W.
Carrier access and cross-connect economics are also visible: fibre entry is listed at RUB 30,000 one time, access to other operators' network resources has a one-time payment of RUB 1,300, and E1, Fast Ethernet, Gigabit Ethernet or fibre connecting lines are shown with monthly payments of RUB 1,400 or RUB 2,300.
Those prices give a useful sanity check against reported revenue. A full cabinet at RUB 68,000 a month produces RUB 816,000 a year before discounts, extra power and cross-connects. Roughly thirty-nine such cabinet-equivalents would equal the reported 2024 revenue. That does not mean the company had thirty-nine full cabinets; revenue may include reserve-site work, server rental, public contracts, maintenance, telecom services and historic hosting. It does show the scale of the problem. A handful of incremental cabinets or lost cabinets can move annual revenue materially.
An extra 3 kW customer can add more than RUB 120,000 a year from power alone at the guaranteed-power rate. A single large customer choosing to buy a carrier service directly, or to consolidate into a bigger Moscow facility, can remove more than a low-margin shared-hosting base would ever replace.
Dedicated-server and VPS prices sit below the cabinet layer and show a legacy-product tail. Dedicated configurations on the site range from old single-core or dual-core machines at RUB 2,000 to more capable dual-processor configurations at RUB 23,600 per month. VPS/VDS plans start at RUB 250 monthly for a small FreeBSD or Linux instance with 256 MB of RAM and run to RUB 1,650 for a larger plan with 3,096 MB of RAM and unlimited traffic. The VPS page also says default VPS connectivity is limited to 100 Mbps unless increased.
These products can monetise unused server hardware and bring small-business customers into the data centre, but they also expose equipment-cycle risk. Very low VPS and old dedicated-server price points are difficult to reconcile with expensive hardware refresh unless churn is low, support is disciplined, and the business uses already-depreciated equipment rather than new capital.
The company's core advantage is not that it owns a huge network. It is that it can sit between local demand and several carriers in one Yaroslavl site. The infrastructure page lists available operators including ATEL, Beeline, MegaFon, MediaCom, Osnova-Telecom, RETN, Rostelecom, TransteleCom, Fiord, Enforta, ER-Telecom, MTS, Zavolga.net, InterZet, IT-Yaroslavl and Netis Telecom. For a customer, that variety can reduce procurement friction: one facility, one local hands team, several possible carrier paths, and the ability to add a cross-connect without moving equipment.
For YarTranzitTelecom, however, the same carrier menu caps pricing power. A sophisticated customer can ask what part of the monthly charge is local facility rent and support, and what part is a pass-through for a carrier circuit that the customer could buy from Rostelecom, ER-Telecom, TTK, RETN, MTS, Beeline or another provider.
The retained-spread test is therefore simple. If YarTranzitTelecom buys, resells or coordinates connectivity, the company has to justify a spread with local reliability, faster service, less paperwork, better route choice, and a more convenient Yaroslavl demarcation. If the customer only needs bulk internet transit, larger carriers and Moscow data centres are natural substitutes. If the customer needs a local cabinet with power, a cross-connect to a regional operator, a reserve node for a public institution, or hands-on support near Yaroslavl, YarTranzitTelecom has a more defensible role.
The business model is not protected by scale; it is protected, if at all, by local switching costs, physical adjacency and operational trust.
Public procurement evidence strengthens the customer-concentration concern. A procurement aggregator records YarTranzitTelecom as a participant and winner in 23 procurement processes with total contract value around RUB 30.6 million. It identifies the largest share as linked to the Yaroslavl regional procurement department, with smaller shares tied to the regional education telecommunications and information-systems centre and to the Electronic Region budget institution.
The same records describe goods and services sold as rentals of office machines and equipment, IT infrastructure placement services, communication-channel services and IT technical support. A separate profile for the education telecommunications centre shows YarTranzitTelecom as one of its suppliers. These are not proof that every contract is current revenue, but they show the buyer base is not just anonymous retail hosting. Public and quasi-public customers appear to matter.
That concentration cuts both ways. Public-sector demand can be sticky because regional institutions value local presence, service continuity and procurement familiarity. It can also be lumpy, price-tested and politically exposed. When most publicly visible procurement value is tied to a small set of buyers, renewal timing matters more than headline revenue. A company with six or seven staff and RUB 31.9 million of revenue does not need many lost renewals to turn a profitable year into a breakeven one.
The 2023 net loss reported by public registries is a warning: even if 2024 recovered, the margin structure appears narrow enough that revenue timing, supplier costs or repair spending can swing the result.
The routing record is the hardest part of the control boundary. Older and still-indexed sources describe AS16047 as YAR-TT-AS for Limited Liability Company YarTranzitTelecom, with two IPv4 prefixes: 37.60.176.0/21 and 185.220.40.0/22, together equal to 3,072 IPv4 addresses and no IPv6. Some sources show RIPE registry data in which the organisation handle is YarTranzitTelecom, the address is Pobedy 16B in Yaroslavl, and the resource was last modified in May 2026 for the organisation record and June 2022 for the aut-num record.
Other, newer routing mirrors show a June 2026 change: AS16047 remains YAR-TT-AS, but the registered organisation is Scientific-Production Enterprise Business Sviaz Holding LLC, with BSH maintainer data and Moscow address details. Newer IPinfo and bgp.tools records also show the two IPv4 blocks under Business Sviaz Holding, not YarTranzitTelecom.
That contradiction is economically material. If YarTranzitTelecom no longer controls the ASN and address resources that market databases still associate with it, then traffic, hosting, abuse-contact and customer-evidence signals tied to AS16047 may describe a successor, affiliate, supplier or transferred network rather than YarTranzitTelecom's current operating base.
If the change is a formal consolidation inside a related group, the economic effect may be smaller, but the public company analysis still needs a clean boundary: which entity owns the customer contracts, which entity invoices data-centre services, which entity controls routing policy, and which entity bears the cost of upstream transit and address-resource compliance. Without that, using AS16047 footprint as direct evidence of YarTranzitTelecom's current scale would overstate certainty.
The transfer signal also changes how to read upstream diversity. RIPE-style routing snippets and industry mirrors list import relationships with AS9049, AS12389 and AS52118 in the routing policy, while current path-oriented mirrors often show only one upstream or adjacent AS, AS9049, ER-Telecom. CIDR Report similarly shows one upstream adjacency in its current view, and IP2Location lists ER-Telecom as the upstream with no downstreams. Cloudflare Radar records routing information for AS16047 but presents it as the YAR-TT-AS network rather than resolving the company economics.
This is why the article's judgment cannot stop at "two prefixes announced." A local data-centre operator selling resilience should show practical route diversity, not only route-policy text. A single observed upstream is not fatal for a small regional facility, but it narrows the claim that the operator can sell differentiated transport rather than local access plus a dominant carrier path.
RPKI and prefix evidence are still useful. IPinfo and other mirrors mark 37.60.176.0/21 and 185.220.40.0/22 as RPKI-valid in current views. IPinfo also reports hosted-domain counts and pingable IPs on the ASN or specific range, including Yaroslavl and Moscow router-location signals. IP2Location geolocates a sample address in the 37.60.176.0/21 block to Yaroslavl and labels the speed class as data-centre or transit. IPXO records a route and RPKI entry for a sample address in the same larger prefix. Those facts show that the address space has been visible and used, not merely registered and dormant.
They do not prove who currently monetises the traffic, and they do not establish customer concentration or retained margin.
YAR-IX is another useful but limited signal. YarTranzitTelecom's site and a 2011 article hosted on its domain describe the Yaroslavl Internet Exchange idea as a neutral place for operators, CDN companies and local legal entities to exchange traffic. The article argues that local exchange can reduce external channel load, shorten paths and stimulate local network infrastructure. The current company site says it organises a YAR-IX access node. This is a good strategic story for a regional data centre: local traffic should not always hairpin through Moscow, and content or public-sector traffic can benefit from local exchange.
The unresolved question is whether YAR-IX became an active, revenue-producing exchange fabric with enough participants and traffic, or whether it remains more a positioning asset than a measurable business line. Public routing sources visible in this research do not show a broad downstream base for AS16047.
The facility's official claim to Tier-3-level reliability must also be read carefully. The site states a predicted service availability of 99.982 percent, which corresponds to the familiar Tier III availability figure used in data-centre marketing. But the public evidence does not show an independent certification in the sources reviewed here. For customer economics, the distinction matters. A self-described Tier-3-level local facility can still be valuable if it delivers reliable power and cooling.
But a customer with compliance-heavy requirements may treat an independent certification, service-level history and incident disclosure differently from a marketing claim. YarTranzitTelecom's economic defence would be stronger if it published current uptime, certification status, utility-feed details, UPS and generator maintenance evidence, and cabinet utilisation.
Power and cooling are where fixed cost becomes unavoidable. Colocation is attractive because a rack can keep producing revenue after the customer installs equipment. But the operator has to provision power and heat removal before knowing whether each kilowatt is sold at the expected rate. The site says each standard cabinet includes up to 3 kW, and extra power is chargeable. It also says the third sealed room added 12 cabinets and 80 kW of cooling. A 12-cabinet zone at 3 kW each would imply 36 kW of IT power before redundancy and cooling overhead.
The listed 80 kW of precision cooling therefore gives some headroom at that room level, but the whole facility's stated 150 kW allocation still constrains the long-term cabinet story. The practical risk is under-utilised infrastructure: if the site has to keep cooling and staffing capacity available for intermittently used cabinets, the gross margin can compress quickly.
This is why the gross-profit number is more informative than the revenue number. Public financial mirrors report 2024 revenue of RUB 31.944 million and cost of sales of RUB 21.944 million, leaving RUB 10.0 million of gross profit. That is a gross margin of roughly 31.3 percent. Net profit of RUB 2.3 million is roughly 7.2 percent of revenue. At this scale, a few changes can consume the net margin: a power tariff increase, a generator or cooling repair, a router replacement, a lost public contract, a licence-renewal delay, a larger carrier bill, or an unpaid customer.
The company does not need to collapse for the investment case to weaken; it only needs fixed cost to grow faster than utilisation.
The 2024 recovery from a reported 2023 loss is encouraging but not conclusive. Revenue grew from about RUB 29.35 million to RUB 31.944 million, or around 8.8 percent. That is better than a stagnant local operator, but it is not explosive. The fact that net profit moved from a small loss in 2023 to a meaningful positive number in 2024 suggests operating leverage, one-off timing, or better contract mix. If fixed costs were largely covered and incremental revenue carried higher margin, the recovery is a positive sign. If it came from a few contracts that renew irregularly, it may be a temporary swing.
Public reports do not separate recurring cabinet revenue from one-time project payments, so the safer conclusion is that the company's earning power is plausible but not yet durable.
Supplier dependence is visible in the product architecture. The site emphasises cooperation with many operators, but route databases in current views most strongly show ER-Telecom as the live upstream or adjacent AS. The older RIPE policy text also names Rostelecom and AS52118. If a customer is paying YarTranzitTelecom for transport, the company may be providing a practical blend of local access, facility service and carrier procurement. That can be valuable, especially for regional institutions that do not want to manage multiple carrier relationships.
But if the underlying upstream cost rises, or if a carrier offers the same circuit directly, YarTranzitTelecom's retained spread is vulnerable. The strongest version of the model is not simple resale; it is a neutral point where customers can choose among carriers and keep local service accountability.
Competition is therefore not limited to another small Yaroslavl ISP. The substitutes include national telecom operators already visible in the facility, larger regional ISPs, Moscow data centres with more carrier density, public cloud, and customer-owned equipment rooms. Each substitute attacks a different part of YarTranzitTelecom's bundle. A large enterprise may move latency-insensitive workloads to Moscow or cloud. A smaller local company may buy a direct internet service from a national operator. A public institution may keep a local reserve node but pressure the monthly price through tenders.
A technically sophisticated customer may colocate in the same building or city and choose its own carriers. YarTranzitTelecom has to keep enough customers for whom local neutrality and service speed outweigh those alternatives.
The company's location gives it a real niche. Yaroslavl is not Moscow, and that matters. A regional customer with offices, public services, media, educational networks or local applications may prefer a site that can be visited quickly and that has staff familiar with local telecom conditions. The official site frames reserve data-centre service around business continuity and geographically distributed infrastructure, including possible cooperation with Moscow operators and data centres.
That is a sensible offer: a Yaroslavl node can be a primary local site, a reserve site for a Moscow-heavy topology, or a place to anchor regional traffic. The risk is that reserve capacity is easier to justify in a budget than to keep fully paid during stable periods.
Unofficial market signals provide colour, not proof. Ping-Admin's public news archive says it added a Yaroslavl monitoring point with YarTranzitTelecom's support in August 2016. That suggests the facility had enough network and server presence to host an external monitoring node. IPinfo's hosted-domain and pingable-IP data suggests active use of the address space. BGP mirrors show the ASN is active. But these signals are not revenue. A monitoring point may be a partnership, a low-value hosting relationship or a long-running legacy deployment.
Hosted-domain counts can include small sites, stale domains or customers of another entity after the 2026 routing change. They support the existence of infrastructure, not the profitability of the company.
Regulation is a live issue because telecom authorisation is not permanent. Public company profiles show two communications-service licences, including numbers in the L030 registry format, with start dates in August 2015 and end dates in August 2026. Aggregators describe licensed activities including telematic communication services, data-transmission services excluding voice-data transmission, and channel-provision services. There is also a public record of a 2017 administrative dispute involving the Yaroslavl Roskomnadzor office and YarTT. None of that proves a current compliance failure.
It does show that licence renewal and regulator interaction belong in the economic model. A local operator selling channels, data-centre services and telecom access cannot treat authorisation as background paperwork.
The ownership and affiliate picture also deserves attention. Public registries identify Yuri Nikolaevich Elashkin as general director and sole owner of YarTranzitTelecom. Other profiles show connections through him to Business Sviaz, Formula-T, Svyaz-K and other entities, including companies at a Moscow address on Zoologicheskaya Street. The current AS16047 registry mirrors that show Business Sviaz Holding after June 2026 make those connections more than incidental. It may be that network resources were moved within a related business orbit, or that old public records are lagging behind a real transfer.
The article cannot resolve that from public evidence alone. What it can say is that customers and analysts need the operating contract boundary: YarTranzitTelecom the Yaroslavl data-centre company may not be the same economic object as AS16047 after the registry change.
There is also an image of continuity from the older closed joint-stock company. A regional government electricity-security decree from 2013 named CJSC YarTranzitTelecom at Pobedy 16B as an e-government data-centre operator whose electricity restriction could have consequences. A data-centre article hosted on the company's site from 2011 referred to CJSC YarTranzitTelecom at the same address. Current registries show the limited liability company was registered in 2015. That history supports the idea that the Yaroslavl site and operating know-how predate the current legal form.
But it also creates another boundary issue: older achievements and infrastructure documents may belong to predecessor entities or earlier corporate arrangements. They are useful for continuity, not a substitute for current utilisation evidence.
The most important calculation is not whether the company can generate revenue at all. It clearly can. The question is how much utilisation is required to keep the fixed base from eroding returns. If a 42U cabinet produces RUB 816,000 annually at the listed tariff, then ten fully billed cabinets would create RUB 8.16 million before extra power, cross-connects and services. Twenty would create RUB 16.32 million. Thirty would create RUB 24.48 million. Add several higher-power customers, reserve-site work, IT support and dedicated servers, and the 2024 revenue level becomes plausible.
But if the facility has to carry 150 kW of capacity, 24/7 support, cooling maintenance and carrier relationships for a much lower occupied base, the same tariffs may not protect profit.
Customer mix decides whether the fixed cost is a burden or leverage. A cabinet customer with a multi-year contract, steady power draw and several cross-connects is high-quality revenue. A public-sector channel contract that renews each year through tender can be valuable but exposed to procurement timing. A VPS customer paying a few hundred roubles a month adds occupancy only if support costs remain minimal. Dedicated-server customers can be profitable if the hardware is depreciated, but refresh spending can turn them into capital traps.
Reserve data-centre service is attractive because customers pay for resilience, but reserve relationships often require proof of testing and continuity procedures. The company needs a mix weighted toward committed infrastructure customers, not only low-ticket hosting residues.
The discontinuation of hosting from January 2025 may be a rational pruning move. If shared hosting was consuming support time without enough margin, ending it allows the company to focus on cabinets, dedicated infrastructure, VPS, reserve-site and data-centre maintenance work. But it also removes an entry product that may have fed small customers into larger services. Public article readers should not treat the hosting exit as automatically positive or negative. It is positive if it raises average revenue per support hour and frees resources for higher-value contracts.
It is negative if it signals shrinking demand for commodity services without a replacement pipeline.
The equipment-cycle issue is bigger than it looks. Dedicated-server lists containing older processors can be read two ways. On one hand, older hardware can be profitable when it is fully depreciated and matched to low-end customer needs. On the other hand, enterprise customers buying resilience may expect modern CPUs, SSD storage, faster ports and better energy efficiency. Power efficiency matters directly in a 150 kW facility. Old servers may generate less revenue per watt than newer dense infrastructure, especially if electricity prices rise or cooling is constrained.
The company therefore needs to know which equipment should be retired, which can keep serving low-end customers, and which customer segments justify new capital.
The same logic applies to network equipment. Public routing visibility shows two IPv4 prefixes and no IPv6. In 2026, no IPv6 footprint is a strategic weakness for an operator that wants to present itself as future-ready, even in markets where IPv4 remains commercially important. IPv4 address scarcity can be an asset if the company controls the addresses and can monetise them through hosting or customer assignments. It is a liability if control has moved elsewhere or if customer demand shifts toward dual-stack capability that the public routing record does not show.
The routing contradiction around AS16047 therefore has both accounting and product implications.
For a buyer, lender or strategic partner, the diligence list is specific. First, reconcile the RIPE and routing records: who controls AS16047, the AS-YAR-TT set, and the two IPv4 blocks today, and under what agreement if the legal registrant is not YarTranzitTelecom. Second, obtain current licence status beyond the August 2026 end dates visible in public profiles. Third, separate 2024 revenue into recurring cabinet and power, cross-connect, carrier resale, public procurement, dedicated/VPS, reserve-site and project service categories. Fourth, list the top ten customers and renewal dates.
Fifth, measure cabinet occupancy, committed power and available headroom. Sixth, identify upstream contracts, route diversity, SLA terms and the practical ability to switch or add carriers without customer disruption.
The public case for YarTranzitTelecom is not weak. It has a real address, a visible local data-centre proposition, published tariffs, evidence of public customers, historical e-government relevance, active or recently associated address space, and a narrow but positive 2024 profit. The public case is simply incomplete. The company is too small for averages to protect it, and the public routing boundary changed too recently to ignore. A disciplined reader should not call it a generic regional ISP.
It is better understood as a Yaroslavl infrastructure node whose economics depend on whether local transport and colocation utilisation stay ahead of a fixed cost base.
The bullish scenario is coherent. YarTranzitTelecom keeps public-sector and enterprise customers because they value a nearby facility, local hands, reserve-site continuity and one-stop access to multiple carriers. The company exits weak hosting, fills cabinets with higher-power customers, adds paid cross-connects, renews licences, clarifies its relationship to Business Sviaz Holding, and uses the Yaroslavl site as a regional continuity node. In that scenario, a small staff can support a meaningful amount of recurring infrastructure revenue, and incremental cabinet or power sales drop through at higher margin after the plant is covered.
The bearish scenario is also coherent. Customers buy directly from larger carriers, move compute to Moscow or cloud, or pressure public tenders below the level that funds renewal capital. Hosting discontinuation removes a customer funnel. Old dedicated hardware becomes a power and support drag. Licence renewal or routing-control ambiguity makes customers cautious. AS16047 evidence that once looked like YarTranzitTelecom scale belongs economically to a related Moscow entity instead. In that scenario, the company remains operational but becomes a low-margin facility caretaker with limited growth and high sensitivity to any lost anchor buyer.
The deciding evidence would be mundane: contracts, cabinets, kilowatts, routes and renewal paperwork. If YarTranzitTelecom can show high utilisation of its paid cabinet and power inventory, committed customers beyond a few public buyers, current carrier diversity, and clean post-2026 licence and routing control, then the fixed-cost model can work. If not, the published tariffs and historical infrastructure story are not enough. One paid transport circuit can be profitable when it fills an otherwise covered facility.
The same circuit is fragile when it is expected to carry too much of the building, the licence, the router, the support shift and the next equipment cycle by itself.
The practical operating dashboard should therefore be built around a few thresholds, not a long list of comforting activity measures. First, committed power should be tracked against sold cabinet revenue and customer identity. A facility can look busy while selling too many low-yield watts to legacy dedicated servers, or it can look modest while a smaller number of cabinets generate stable recurring revenue with extra power and cross-connects. Second, cross-connect count should be tracked separately from gross carrier availability.
A long list of operators in the building is useful only when customers actually pay for access, choose diverse paths, and renew services because the local demarcation saves them time or risk. Third, procurement exposure should be tracked by renewal date and service type. Public-sector contracts for channels and infrastructure placement can be sticky, but they can also convert into aggressive price competitions when budgets tighten.
Fourth, management should separate old revenue from strategic revenue. A low-priced VPS, an ageing dedicated server and a recurring public-sector cabinet can all appear as monthly service income, but they do not have the same cost curve. The VPS may need almost no hands-on work or may become a support nuisance. The dedicated server may be profitable because the machine is fully depreciated or unprofitable because it wastes scarce power. The cabinet may create long-term leverage if the customer buys power, cross-connects and remote hands, or it may be a low-margin placeholder if the customer uses the site as cheap storage.
Without that segmentation, total revenue can hide deterioration in the quality of utilisation.
Finally, the 2026 routing-control question should be treated as a customer-facing issue. For a local data-centre business, the public identity of address resources affects abuse handling, route filtering, reputation checks and procurement diligence. A customer buying space and access wants to know whether its IP resources, reverse-DNS arrangements, upstream escalation and routing incidents are handled by YarTranzitTelecom's local team, by Business Sviaz Holding, or by a layered commercial arrangement between them. None of those structures is inherently bad. The risk is opacity.
If the boundary is clear, the Yaroslavl facility can still sell local service even when routing administration sits elsewhere. If the boundary is unclear, every routing incident or procurement review becomes another reason for a customer to test a direct-carrier alternative.
That is also why the company's best evidence would be operational rather than promotional. A refreshed web page would matter less than a published current service matrix showing which services are still sold, which tariffs are legacy, how carrier handoff works, and which continuity tests are performed for reserve-site customers. A small operator can win trust by being precise: what power is guaranteed, what is best effort, what support response is included, how maintenance windows are handled, what happens when an upstream fails, and how customers are migrated if old dedicated hardware is retired.
Those details convert a local facility from a place with equipment into a managed risk product. They also let customers compare YarTranzitTelecom against larger substitutes on the dimensions where the regional operator can actually win. It probably cannot beat Moscow-scale data centres on carrier density or cloud elasticity. It can beat them for certain Yaroslavl customers on proximity, simplicity, local knowledge and fast physical intervention, but only when those advantages are visible in the contract and in the operating record.
Sources
- https://www.yar-tt.ru/
- https://www.yar-tt.ru/infrastructure/
- https://www.yar-tt.ru/services/
- https://www.yar-tt.ru/services/colocation
- https://www.yar-tt.ru/services/dedicated
- https://www.yar-tt.ru/services/vps_vds
- https://www.yar-tt.ru/services/backup_data_center
- https://www.yar-tt.ru/services/service_data_center
- https://www.yar-tt.ru/docs/COD.pdf
- https://www.yar-tt.ru/docs/YAR-IX.pdf
- https://companies.rbc.ru/id/1157606001068-ooo-yartranzittelecom/
- https://www.banki.ru/business/contragent/7606098580-760601001/
- https://b2b.house/company/OOO-YARTT_1f304759-bfdc-4799-a066-6db52da2f833/
- https://b2b.house/company/OOO-YARTT_1f304759-bfdc-4799-a066-6db52da2f833/purchases/
- https://spark-interfax.ru/yaroslavskaya-oblast-yaroslavl/ooo-yartt-inn-7606098580-ogrn-1157606001068-8aad11beaf5547ad8c219c6fb5a1c9b8
- https://www.openweb.ru/7606098580-ooo-yartt
- https://contragent.org/7606098580-ooo-yartt-yaroslavl
- https://alldc.ru/dcs/company/673.html
- https://base.garant.ru/24580578/
- https://declaration.rostrud.gov.ru/declaration/index?DeclarationSearch%5Binn%5D=5073086337&DeclarationSearch%5Bregion_id%5D=32&page=494&per-page=50
- https://ping-admin.com/news/all/
- https://ping-admin.ru/news/all/
- https://ipinfo.io/AS16047
- https://ipinfo.io/AS16047/37.60.176.0/21
- https://ipinfo.io/ips/185.220.40.0/24
- https://ipgeolocation.io/browse/asn/AS16047
- https://www.iplocate.io/AS16047
- https://www.ip2location.com/as16047
- https://www.ip2location.com/37.60.181.182
- https://bgp.tools/as/16047
- https://whois.ipip.net/AS16047
- https://www.cidr-report.org/cgi-bin/as-report?as=AS16047&view=2.0
- https://radar.cloudflare.com/routing/as16047
- https://radar.cloudflare.com/quality/as16047
- https://www.ipaddress.com/ipdb/ipv4-public/37.60.179.224/27/
- https://www.ipxo.com/ip-info/37.60.182.107/24/
- https://bgpv6.com/country/RU
- https://www.pdflibr.com/AS16047
- https://2ip.ru/ip/37.60.179.230/
- https://www.peeringdb.com/advanced_search
- https://docs.db.ripe.net/How-to-Query-the-RIPE-Database/RESTful-API-Queries
- https://docs.db.ripe.net/Update-Methods/RESTful-API
- https://www.rusprofile.ru/date/2015-03-27
- https://xfirm.ru/person/503200670386
- https://companies.rbc.ru/category/651-uslugi_telefonnoj_svyazi/3/
- https://companies.rbc.ru/alphabetical-catalog/companies/ja-r-t/
- https://companies.rbc.ru/alphabetical-catalog/companies/ja-r/7/
- https://b2b.house/company/GU-YAO-CTISO_de84e392-588d-4d35-8888-14ab83ccbfd7/
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance