
Summary
- Start with a fault ticket on a paying connection, because that is where VLADINFO's economics become visible. A residential account paying a few hundred rubles a month can absorb only a small amount of technician time before the month's margin disappears. A business line, a local institution, a telephone connection, or a customer who values a known support desk can justify more labour only if the operator turns response speed and continuity into price, retention or contract duration. The company therefore has to sell the consequence of support, not the romance of being local.
- The company has real operating substance. Public registries identify Limited Liability Company "VLADINFO" as an active Vladimir communications company with OGRN 1033302001985 and INN 3328421421, registered in 2001, with wired-telecom activity as its main code. Financial aggregators citing official reporting show 2025 revenue around 80.2 million rubles and profit around 7.3 million rubles, after a much thinner 2024. That is enough to be a durable local operator, but not enough to tolerate sloppy dispatch, stale equipment choices, or tariff discounting without consequence.
- Network-resource evidence supports the operating picture. RIPE and routing datasets show AS35645, INFOCENTER, attached to Limited Liability Company "VLADINFO"; BGP sources show an active eyeball network with dozens of IPv4 prefixes, upstream exposure to carriers including RETN, MTS and MegaFon, and a small downstream cone. This is not a pure reseller listing. It is a routed access network whose economic exposure includes transit, peering, address stewardship, abuse handling and route reliability.
- The central risk is price compression. Local listings put Vladimir households in a market with many providers and aggressive broadband bundles from larger names. RayON-linked retail pages show mass-market internet and internet-plus-TV prices that leave limited room for repeated truck rolls. JustConnect and DomInternet listings show that national and regional substitutes can put 100 Mbit/s service in the 400-600 ruble zone, sometimes with bundled mobile, television, router or promotional discounts. VLADINFO cannot win that fight by treating every connection as a bespoke support account.
- The judgment is conditional. VLADINFO can defend economics if it focuses on customers whose downtime is expensive, contracts whose service boundaries are explicit, buildings where field familiarity lowers repeat visits, and services such as fixed telephony, static addressing, video, domophony or business connectivity where local intervention has measurable value. The judgment would weaken if revenue growth proves promotion-driven, if licence or pole-access friction rises, if upstream concentration turns into cost pressure, or if customer signals show support labour is consuming value without improving churn.
One ticket, one connection, one income statement
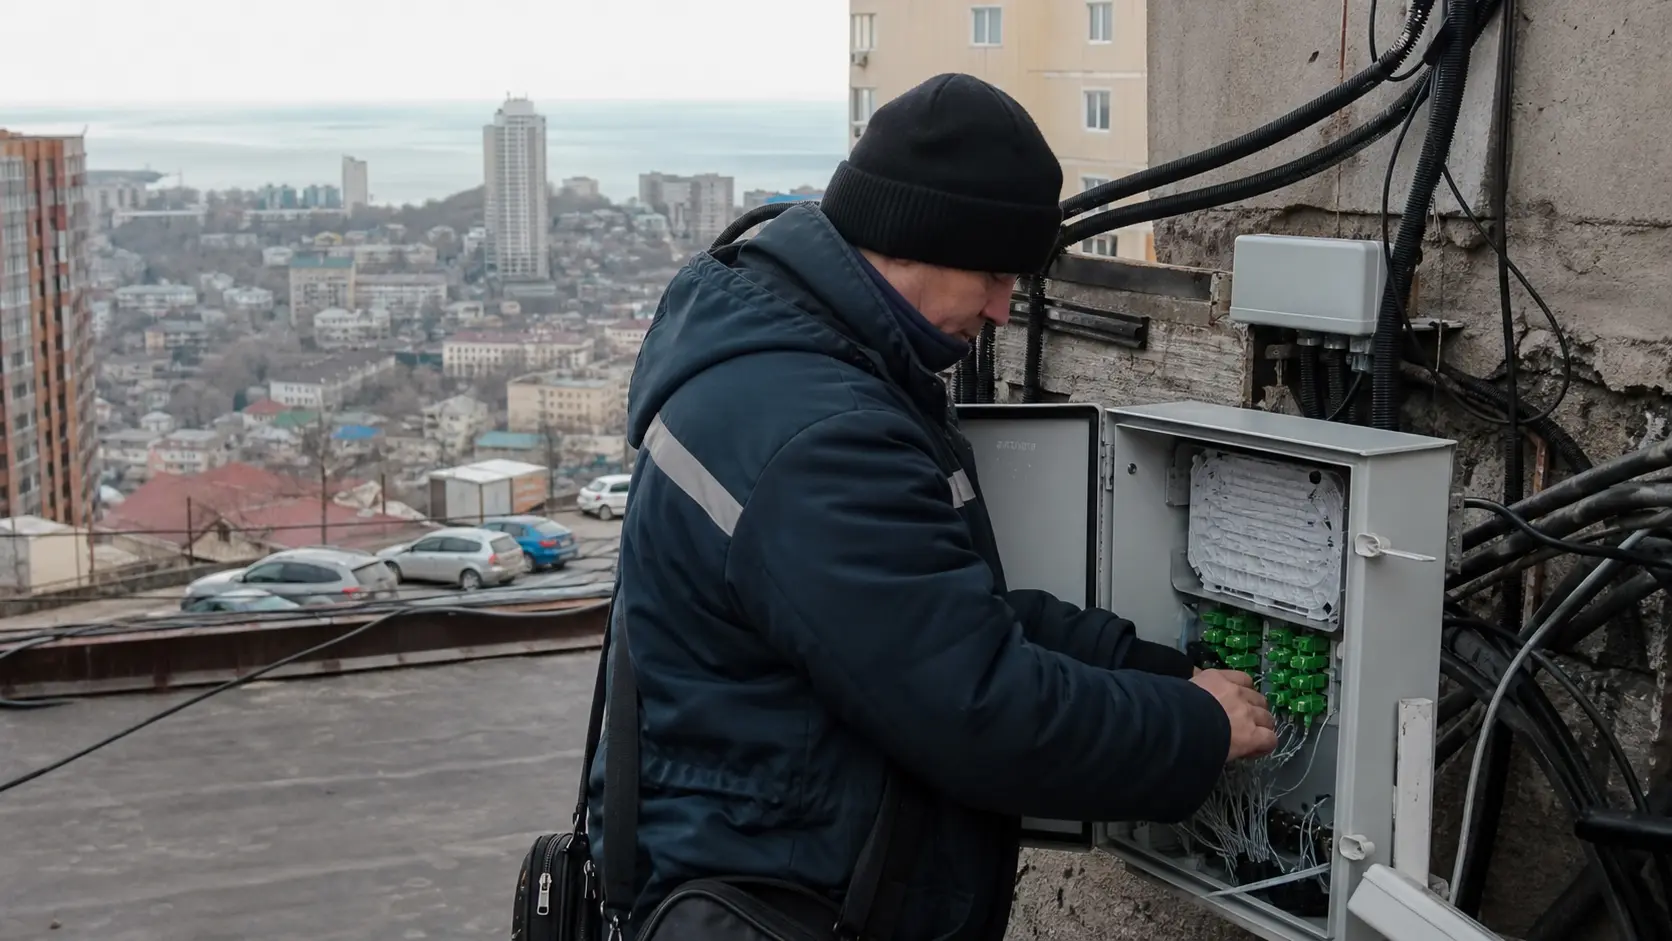
Take one fault ticket attached to one paying connection. The customer is not buying a regulatory licence, an autonomous system, or an address block; the customer is paying because a home, office, shop, clinic, school, court building or apartment block needs a working link. When that link fails, the operator's promise is tested in a brutally small account-level income statement. A support call has to be answered.
Someone has to decide whether the fault is in the customer's router, the drop cable, the building switch, a local power condition, an upstream path, a billing block, a television component, a telephone circuit, or a wider outage. If the ticket becomes a visit, labour time is no longer abstract. A technician travels, diagnoses, replaces a connector, reterminates a cable, tests signal, calls back, closes the case, and possibly returns if the first fix was wrong.
For VLADINFO, the economic question sits there. Public price signals in Vladimir show household broadband at levels that do not forgive many repeat visits. RayON-linked residential plans list 50 Mbit/s, 75 Mbit/s, 100 Mbit/s and 300 Mbit/s monthly tariffs in the low hundreds of rubles, with promotional entry prices lower still. Internet-plus-TV bundles sit higher, but still in a range where one poorly handled fault can absorb a large part of near-term gross contribution. A home telephone plan provided through the partner structure is more modest still.
A business connection can carry more value, especially when it includes static addressing, continuity expectations or a known installation, but the customer still compares the offer with national operators and city-wide alternatives.
That is why "local support" cannot be treated as a slogan. It is either a pricing instrument or a cost centre. It becomes pricing power when it reduces customer risk enough that a buyer accepts a higher total monthly bill, a longer relationship, an add-on service, or a lower willingness to churn. It becomes permanent labour cost when the operator uses local staff to rescue low-price customers who entered through discounts, equipment gaps, or poor expectation-setting.
The same dispatcher, the same technician and the same spare router can create value or destroy it depending on whether the customer segment pays for reliability, whether the first visit solves the issue, and whether the tariff captures the cost of being reachable.
The evidence points to a company that has enough operating depth to attempt the first route, but also enough exposure to fall into the second. VLADINFO has a registered corporate identity, a routed network, communications licences, a multi-year public footprint, local service listings, and court records that show it has had to fight over infrastructure cost. It also operates in a market where headline broadband is cheap, large providers are visible at the building level, and customer-review channels punish perceived support failures. The article's answer is therefore not a yes or no.
Customers' willingness to pay can cover transit, technicians, spares and renewal capital only if VLADINFO deliberately reserves its expensive human response for customers and services where human response changes the customer's own economics.
The company boundary is real, but it is not simple
The legal entity under review is Limited Liability Company "VLADINFO", not every brand, reseller, partner page or adjacent local network that appears beside it. Public company profiles identify the Vladimir entity with OGRN 1033302001985 and INN 3328421421, a registration date in October 2001, an active status, a legal address on Studencheskaya Street in Vladimir, and a principal activity in wired telecommunications.
Several profiles list the same broad shape: a small communications company, multiple registered activities around fixed telecoms, data, telephony, cable broadcasting, computer support and related technical work, and a shareholder structure distributed across named individuals rather than a national group.
That boundary matters because local telecom markets often blur companies, brands, retail intermediaries and operating partnerships. RayON's public "About" page says the RayON brand was created on the basis of Vladimirskie Lokalnye Seti, and that since 2009 RayON's main partners have included VLADINFO and Infocentre. RayON pages also link to a personal account domain at VLADINFO and present shared local service channels. At the same time, RayON legal documents name Vladimirskie Lokalnye Seti as operator for the offer and terms.
A careful reading therefore treats RayON material as evidence of the local service ecosystem and partner surface, not as proof that every RayON subscriber or tariff belongs economically to VLADINFO.
That distinction actually sharpens the analysis. If VLADINFO is part of a local operating cluster, the commercial task is to monetize the areas where the cluster's local knowledge matters: building access, old copper or coaxial remnants, FTTb plant, customer premises equipment, fixed telephony, static IP needs, payment habits, and institutional relationships. If the cluster lets the brand boundary become vague, the risk is mispriced responsibility. Customers do not care which legal entity owns the exact cable or contract when service fails. They call the name they know.
The operator that answers inherits the labour cost, whether or not it captured the full revenue.
The financial scale is consistent with a real but disciplined regional operator. Saby and TBank profile data indicate 2025 revenue of about 80.2 million rubles and 2025 profit of about 7.3 million rubles. RBC's company profile shows 2024 revenue around 71.2 million rubles, cost of sales around 43.5 million rubles, gross profit around 27.8 million rubles and profit around 1.1 million rubles. These figures imply a business that can be profitable but whose margin can swing materially. A 2025 profit margin near nine percent looks respectable for a small fixed operator.
A 2024 margin closer to one or two percent is a warning that labour, access costs, depreciation, price competition or one-off items can quickly narrow the cushion.
The right question is therefore not whether VLADINFO is "big enough". It is whether its revenue quality is good enough. At roughly 80 million rubles a year, the business has a monthly revenue pool of about 6.7 million rubles before expenses. That pool has to support staff, billing, offices, vehicles, taxes, licences, upstream connectivity, customer support, spares, power exposure, network equipment, access to poles or buildings, and renewal capital. The company cannot behave like a national operator with huge procurement leverage. It also cannot behave like a boutique integrator on every low-ARPU household line.
Its defensible space is the middle: local enough to know the plant, technical enough to route its own network, and selective enough to avoid selling expensive support to customers who buy only the lowest price.
Routing evidence shows operating substance, not pricing immunity
AS35645 is central to the case because routed network evidence is harder to inflate than marketing copy. RIPE RDAP identifies AS35645 as INFOCENTER with active status and connects the resource to Limited Liability Company "VLADINFO". The RIPE organisation object also shows the company as a local internet registry-style resource holder, with a Vladimir address and a last-changed date in 2026. RIPEstat identifies the holder as INFOCENTER Limited Liability Company "VLADINFO" and shows the AS as announced. BGP.tools describes the network as an eyeball network with originated IPv4 space and no originated IPv6 space.
CAIDA AS Rank shows a small but non-zero customer cone and a degree that reflects several routing relationships rather than a single-homed retail shell.
The route table tells an economic story. IPinfo and BGP.tools identify upstream relationships including RETN, MTS and MegaFon, while RIPEstat's routing-consistency view shows imports and exports involving multiple peers and customers. IPinfo lists downstreams including OOO KISS, AO ABI "Product", Voice Communication LLC and JSC DSC. BGP.tools reports dozens of originated IPv4 prefixes, while RIPEstat's announced-prefixes feed shows a current set of visible prefixes in ranges such as 95.66.128.0/19, 95.66.160.0/19, 95.66.192.0/22, 95.66.216.0/22 and several /23 and /24 routes.
Hurricane Electric and IPinfo prefix pages tie portions of the routed space to OOO VLS or VLADINFO-linked infrastructure.
This matters because it means the company is not simply buying an upstream line and reselling a consumer plan under a local name. It has address stewardship, route policy, abuse-handling obligations, and a network identity visible to the global routing system. That gives VLADINFO operational options: it can multi-home, manage local prefixes, host local services, support business customers that need stable addressing, and potentially serve downstream networks or institutions. It also creates responsibilities.
Route misconfiguration, upstream outages, DDoS handling, abuse complaints, RPKI and IRR hygiene, and stale equipment all have direct customer consequences.
But routing substance is not pricing immunity. A customer does not pay a premium because CAIDA counts a customer cone or because RIPE recognises an organisation object. Those facts support the operator's credibility, not the customer's invoice. The route table becomes pricing power only when it supports services that substitutes cannot easily replicate at the same address and response time: stable business access, lower path dependency, responsive NOC handling, static IP, quick diagnosis of local faults, and credible escalation when an upstream path fails.
If AS ownership merely raises the cost base while the market forces the tariff down to commodity broadband levels, it becomes another fixed cost fighting the monthly bill.
The absence of visible IPv6 origination in BGP.tools also deserves attention. It is not fatal in a Russian residential market where many customers remain IPv4-oriented and where carrier-grade NAT or legacy setups may be common. But it is a signal about renewal decisions. An operator that wants business and technical customers to pay for competence should eventually be able to explain its IPv6 posture, not as a fashionable feature but as part of future-proof routing, customer equipment policy and public-sector or enterprise requirements. If VLADINFO's customers are mostly legacy residential lines, the immediate economics may not demand it.
If the company wants to sell continuity to professional buyers, routing modernisation becomes part of the product.
Pricing power has to come from fault recovery, not from speed claims
The local speed-and-price field is unforgiving. RayON's public residential internet page lists plans from 50 to 300 Mbit/s, with standard monthly prices in the 520-750 ruble range and promotional prices below that. The same page says connection can be free where technically possible, while basic Wi-Fi router setup has a listed fee. The internet-plus-TV page lists bundles at 600, 700 and 900 rubles for 50, 100 and 300 Mbit/s packages with more than 120 channels including 24 HD channels. Cable TV alone is listed at 250 rubles per month on the relevant RayON page.
The telephone page states that the service is provided by partner ООО "ВЛАДИНФО" and lists household voice tariffs from 150 to 390 rubles per month, with connection fees for direct city numbers.
Those prices leave a narrow answer to the economic question. A standard household line cannot support frequent manual intervention unless intervention is rare, fast and repeat-resistant. The economics improve when the ticket belongs to a business customer, when the line carries telephone or video services, when the customer needs a static IP, when the operator owns the building access relationship, or when the customer values a local desk more than another provider's cheaper headline speed.
RayON's business page points in this direction: it describes corporate connectivity, phone, video surveillance and domophony, notes 24/7 technical support, and says business tariffs are calculated individually according to employee count, task type and customer wishes. That is the right commercial structure if the operator uses it seriously.
The wrong structure would be to use local support as an unlimited promise attached to every discounted line. Promotional prices are useful for acquisition, but they create a trap if the customer then expects bespoke support while paying a commodity rate. The public offer terms for RayON-style services make clear that tariffs can change with notice, that service can be suspended for lack of payment, and that the operator allocates responsibilities between operator network and customer equipment. Those clauses are not mere legal formality. They are part of unit economics.
If the operator fails to define the boundary, every unstable customer router becomes the operator's problem. If the operator defines the boundary too harshly, support reputation deteriorates. The profitable route is to diagnose quickly, separate network faults from premises faults, sell managed equipment where the customer needs it, and price labour explicitly when the issue is outside the included service.
The Vladinfo-labelled tariff list on JustConnect is a cautionary signal. It shows older-looking Vlad.Net names with speeds from 15 to 40 Mbit/s and prices from 550 to 2,200 rubles per month, plus ADSL. The page also says VLADINFO has worked in modern communications services since July 2002 and offers analogue and digital leased channels, xDSL, Ethernet, home networks and channel leasing. I would not treat those tariff names as current binding offers without direct confirmation, because the names themselves look historically anchored. But they do show the operator's legacy: this was not born as a pure gigabit-price comparison product.
There is a strand of leased-channel, xDSL, Ethernet and local engineering work in the identity. That strand is where pricing power can still live.
The cost stack is wider than transit
Transit is only one line in the cost stack. A regional ISP pays, directly or indirectly, for upstream connectivity, equipment, address administration, abuse handling, support staff, field technicians, premises, vehicles, spares, power, billing systems, payment collection, taxes, legal compliance, and access to physical infrastructure. The route evidence shows upstream diversity, which helps reliability but still exposes the operator to wholesale cost and technical coordination. The public company data show communications licences and wired-telecom registration. The court data show infrastructure-access friction.
The tariff and offer pages show customer support, payment, connection, router setup and billing mechanics.
The pole-access dispute is especially important. In case materials from the Vladimir region, VLADINFO and Megaseti challenged an antimonopoly refusal concerning municipal poles used for fibre-optic communication lines. They argued that the annual base rent for one place on municipal contact-network and street-lighting poles was unjustified or inflated and could impair competition. The Vladimir court rejected the claim; the first appellate court upheld the result; a 2026 cassation summary reports that VLADINFO's complaint did not succeed. The merits are for the court.
The economic lesson is simpler: local access to ducts, poles, buildings and municipal property is not free, and a local operator may have to spend management attention and legal resources even when it loses.
That physical-access layer changes the meaning of local support. If the company owns or controls customer drops and building relationships, the technician visit can be efficient. If it must negotiate with municipal bodies, building managers or infrastructure owners for every change, the labour cost rises. If pole rents or access charges rise faster than retail ARPU, the company has to choose between price increases, selective coverage, lower reinvestment, or thinner margins. Larger operators can sometimes spread that friction across a larger base or use bargaining power.
A local operator has to be precise about where it builds, where it maintains, and where it declines uneconomic promises.
Equipment renewal is another pressure point. Russian fixed-network operators face a changed equipment environment after sanctions, parallel imports, import substitution policy and vendor withdrawal. Industry sources describe a fixed-communications equipment market that increasingly includes Russian-labelled access devices, switches, DWDM systems, routers, radio relay and cable products, while analysts of the Russian telecom sector describe continuing dependence on grey or parallel imports and alternative suppliers. For VLADINFO, the problem is not geopolitical commentary. It is spares.
A failed switch, an ageing access node, an optical module, a router, a TV set-top box, a Wi-Fi device or a phone-service component must be replaced with something supportable. Cheap customer acquisition is meaningless if the operator cannot maintain the access layer at predictable cost.
The company's 2025 profit improvement is encouraging but should not be over-read. A jump from about 1.1 million rubles of profit in 2024 to about 7.3 million in 2025 could reflect better pricing, cost control, contract mix, accounting effects, lower extraordinary expenses, or timing. Public profiles do not give enough detail to isolate the cause. What can be said is that a thin-margin 2024 would have had little tolerance for repeated tickets and unpriced labour. A stronger 2025 creates room for reinvestment only if management resists using the cushion to chase low-value volume.
Customers are not equal: the company needs to know which outages matter
The highest-value customer is not necessarily the fastest line. It is the customer for whom a local outage has a high immediate cost and for whom VLADINFO has a credible advantage in prevention or recovery. A small office with payment terminals, a clinic with appointment systems, a local court or government office, a retail location with surveillance, a building needing telephony and domophony, or an SME requiring a fixed address may care more about response time and responsibility boundaries than about another promotional megabit.
Public procurement profiles show that VLADINFO has supplied internet access services to state-linked customers, with contract counts and customers including judicial and healthcare names in aggregator data. Those amounts are not large enough to transform the whole company, but they are the type of demand where continuity can matter.
The risk is concentration by habit rather than by strategy. If a few institutional customers, building clusters or partner channels provide a meaningful share of gross profit, the company should know it and price service levels accordingly. Public data do not provide customer concentration by revenue, so the analysis must remain conditional. The company might have a broad residential base, a meaningful business base, a public-sector tail, or a mix tied to the RayON/VLS partnership. What the data do show is that a local operator of this size cannot assume every customer is worth the same support intensity.
A 500-ruble residential account, a 900-ruble bundle, a city-number phone line, and an individually priced business line should not have identical escalation economics.
Payment collection is part of customer quality. RayON pages list multiple payment methods and locations, and the public offer states prepayment, personal account tracking, suspension after balance exhaustion, and termination after extended nonpayment. That structure protects cash flow only if enforced with discipline. In a low-ARPU consumer market, unpaid service can erase profit faster than headline churn. In a local community, the temptation is to be flexible because staff know customers or building managers. Flexibility has value when it preserves a profitable relationship. It is destructive when it turns support into credit extension.
Support also has to change judgment over time. If a building generates repeated tickets because of old in-building wiring, unreliable power, bad customer routers, poor access to risers, or recurring vandalism, the company should not treat every ticket as a surprise. It should either invest, reprice, change the service promise, or exit the bad economics. Local knowledge is an asset precisely because it allows segmentation by building and fault history. National operators often treat addresses as database entries. A local operator can know the riser, the caretaker, the switch room, the power quirk and the customer equipment pattern.
That knowledge becomes pricing power only if it changes commercial decisions.
Competition sets the ceiling, substitution sets the threat
VLADINFO's most dangerous competitor is not one named company. It is the customer's belief that broadband is interchangeable. JustConnect's Vladimir page lists a wide set of providers in the city, including national and regional brands, and advertises home internet from low price points. DomInternet's tariff page for Vladimir lists 19 internet-only tariffs from four providers, with mass-market offers from MTS, MegaFon, Rostelecom and TTK and prices commonly in the hundreds of rubles. Address-level 2GIS pages show buildings where many provider options or advertised alternatives appear beside RayON and VLADINFO.
That is the economic ceiling.
Large operators attack with bundles. They can combine broadband, mobile, television, routers, cloud storage, antivirus, content subscriptions, instalment equipment and introductory discounts. They can make a household think the broadband line is only one part of a larger communications package. They also have brand familiarity and procurement scale. VLADINFO should not try to beat that with a thinner version of the same bundle unless it has a building-specific cost advantage. A 100 Mbit/s commodity line is not a moat.
The defensible counterposition is not nostalgia for localness. It is operational consequence. A larger provider can sell a cheap package, but it may route support through national systems, outsourced call centres, slower field queues or less building-specific knowledge. A local operator can win when the customer has already learned that the cheapest line is costly during failure. That is why the opening fault ticket matters. If the customer's cost of being offline is almost zero, price wins. If the customer's cost of being offline is real, a reachable local operator has value.
Substitution is not limited to fixed broadband. Mobile broadband, 5G routers where available, business wireless backups, neighbour Wi-Fi, public Wi-Fi, and second fixed lines can all reduce the perceived value of a local fixed operator. At the same time, Russia's recent experience with mobile internet restrictions can strengthen fixed-line relevance for some households and businesses. Public reporting and advocacy work describe throttling, blocking and state-control measures that can affect how users experience the open internet. Those developments do not automatically benefit VLADINFO; fixed providers also carry regulatory obligations.
But they may make a stable fixed line more valuable than a mobile-only fallback for customers who need ordinary daily connectivity.
The right competitive response is to price resilience, not to overpromise speed. VLADINFO should sell packages whose difference is clear: business response windows, managed CPE, static IP, phone continuity, video or domophony support, building-specific maintenance, dual-homing where feasible, and documented escalation. It should avoid presenting every product as "fast internet" because that invites direct comparison with national bundles. The company has a routed network and local field presence. Those assets should be put where the comparison is operational reliability, not megabits per ruble.
Regulation is a cost, a constraint and sometimes a forcing function
The regulatory surface is not theoretical. VLADINFO's licences, court disputes and status as a communications operator place it inside a state-controlled sector. The universal-service reserve case shows that the Ministry of Digital Development sought arrears and penalties tied to old mandatory contributions; the courts left the lower decisions in VLADINFO's favour because of limitation issues. That is not evidence of a current operating weakness. It is evidence that communications operators carry long-lived statutory obligations, and that old periods can resurface as claims even years later.
The antimonopoly and pole-access litigation shows a different side of regulation: infrastructure cost and municipal control. Local operators need places to put fibre. If the public pole or lighting infrastructure price is contested, the issue goes directly to coverage economics. VLADINFO and Megaseti argued that the municipal rate structure harmed their ability to operate; the courts did not give them relief. For strategy, the lesson is not to relitigate the case. It is to assume that access charges and municipal processes can remain outside the company's control. Good local support cannot compensate forever for bad physical economics.
Russian internet-control rules also matter operationally. Human Rights Watch describes the TSPU system and state-mandated equipment used for traffic control and filtering. Cloudflare reported throttling affecting Russian users' access to Cloudflare-protected services in 2025. These sources do not describe VLADINFO specifically, so they should not be used to accuse the company of anything beyond being an ISP in Russia.
But they do show a macro environment in which local ISPs may face compliance obligations, customer complaints about services beyond the operator's direct control, and difficulty explaining when poor access is not a local fault. That complicates support economics. A customer who cannot load a foreign site may call the local provider even when the cause is national policy, upstream filtering, or platform-specific throttling.
This is where support training becomes money. A poorly trained support desk sends a technician or keeps a case open for a problem no field visit can fix. A well-trained desk distinguishes local physical faults, customer equipment faults, billing suspensions, DNS or routing issues, upstream congestion, platform throttling, and state-level filtering symptoms. The technician is the most expensive diagnostic tool. VLADINFO should use routing visibility and customer education before it uses a truck.
Unofficial signals are useful only when handled as signals
Customer-review pages and address listings are not audited operating records. They are still useful. 101Internet's VLADINFO review page includes a negative user review and warns readers that customers with bad experiences are more likely to leave comments than satisfied customers. 2GIS address pages show RayON or VLADINFO appearing beside many alternatives, with ratings for some providers and repeated advertising by competitors. Zoon-style and local directory pages place VLADINFO at a physical office and classify it among internet, hosting, domain-registration and telecom services.
These pages are noisy, but they reveal how the market sees the company: a local operator in a crowded choice set, not an invisible wholesale network.
The support implication is severe. A local ISP can outperform national operators in reality and still lose if review channels frame it as slow, unresponsive or old-fashioned. Conversely, a few negative reviews should not be over-weighted if the financials show stable revenue and if business customers renew. The correct use of unofficial signals is not to panic. It is to identify recurring themes: slow speed, installation friction, billing confusion, unreachable support, good technician behaviour, local office usefulness, or comparison with cheaper providers.
If a repeated complaint maps to a fixable process, it is an operating cost with a return. If complaints are isolated or biased, they should not drive strategy.
The local office is an underused economic asset when digital support becomes impersonal. Public listings place VLADINFO or RayON service points around Gorkogo Street and Studencheskaya Street in Vladimir, and RayON pages list a main office and an additional office. A physical office adds rent and staff cost, but it also enables cash payment habits, equipment exchange, elderly or non-digital customer support, and trust for business buyers who dislike faceless call centres. The office pays if it reduces churn, collects cash, sells higher-value service, or speeds resolution.
It does not pay if it merely receives complaints created by underpriced products.
Unofficial signals also help identify substitute intensity. Address-level pages with many listed providers tell VLADINFO where price competition is likely hardest. A building with MTS, MegaFon, Rostelecom, local fibre operators and advertised promotions is not the same as a building where VLADINFO has unique plant knowledge or where fixed telephony and video services create a stickier account. Local support should be targeted first at sticky and higher-value addresses. In hypercompetitive buildings, the product either needs a clear support premium or a disciplined no-frills tariff that avoids unnecessary truck rolls.
What would change the judgment
The base judgment is cautiously positive but narrow. VLADINFO can make local support pay if it treats support as a priced reliability product and not as a universal subsidy for commodity broadband. The company's legal life, routed AS, licence footprint, reported revenue, local partner evidence and infrastructure disputes all support the view that this is a functioning local operator with assets worth defending. But the same evidence shows why the margin can disappear: cheap substitutes, physical-access costs, spares, labour, compliance, review pressure and ambiguous partner boundaries.
Several facts would strengthen the view. First, evidence that business and institutional customers contribute a disproportionate share of gross profit would justify more support investment. Second, evidence that repeat fault rates are low by building and that first-visit resolution is high would show that local knowledge is lowering labour cost. Third, a clear managed-equipment programme, with router rental or support fees attached to responsible service boundaries, would convert customer-premises chaos into revenue.
Fourth, visible IPv6 planning, RPKI hygiene and documented upstream redundancy would reinforce the technical premium for professional customers. Fifth, contract language that distinguishes residential best-effort service from business continuity would help prevent support promises from leaking across segments.
Several facts would weaken the view. If 2025 revenue growth came mainly from discount-driven residential acquisition, the higher profit may not persist. If customer reviews increasingly mention unresolved faults or repeat visits, labour cost is likely consuming value. If pole access, municipal charges or building-entry conditions worsen, the network may become harder to renew. If upstream or equipment costs rise faster than tariffs, the company may have to defer capital renewal. If the RayON, VLS, Infocentre and VLADINFO boundaries confuse responsibility, one entity may bear costs captured by another.
If national operators overbuild the same buildings with bundled mobile and TV offers, VLADINFO's local premium must become more explicit or it will be arbitraged away.
The capital allocation answer follows. VLADINFO should not chase every low-price household. It should protect the buildings and customers where its field knowledge lowers real downtime, migrate cheap customers toward self-service and managed equipment options, price business support individually, and use the routed network as a technical credibility asset. It should treat every support ticket as a measurement event: What did the customer pay? What failed? Was the cause inside the operator network? Was a visit required? Did the visit solve it permanently? Did the account renew, upgrade or churn?
If the company cannot answer those questions, it cannot know whether local support is a moat or a leak.
That measurement should also separate avoidable labour from profitable labour. A visit caused by a customer's obsolete router, unpaid balance or poorly explained Wi-Fi limitation should lead to a clearer service boundary or a paid managed-equipment offer. A visit caused by a bad connector in a profitable building should lead to preventive inspection of adjacent lines. A visit for a business customer whose downtime was shortened should become renewal evidence. The same hour of technician time can be waste, maintenance or sales proof. The company has to classify it before the monthly margin is gone.
The answer to the row's economic question is therefore conditional but clear. Customers' willingness to pay can cover transit, technicians, spares and renewal capital only where VLADINFO sells reliability to customers who value it and controls the labour loop tightly. The market will not pay a blanket premium for local identity. It will pay for a working connection, a support desk that knows the building, a technician who fixes the fault once, a phone or video service that remains usable, and a business link whose failure has a cost. VLADINFO's job is to make that value legible in the tariff before the ticket arrives.
If it waits until the fault call, the technician is already defending yesterday's underpriced promise.
Sources
- https://companies.rbc.ru/id/1033302001985-ooo-vladinfo/
- https://saby.ru/profile/3328421421-332801001
- https://www.tbank.ru/business/contractor/legal/1033302001985/
- https://www.rusprofile.ru/id/1146490
- https://spark-interfax.ru/vladimirskaya-oblast-vladimir/ooo-vladinfo-inn-3328421421-ogrn-1033302001985-03008ff4ef024a9fa065678f7c53d29c
- https://star-pro.ru/proverka-kontragenta/organization/1033302001985--ooo-vladinfo
- https://www.gos-postavki.ru/company/3328421421-ooo-vladinfo-vladimir
- https://base.garant.ru/39744829/
- https://base.garant.ru/65441933/
- https://www.zakonrf.info/arbsud/doc-6bc5620f-b94d-572c-85ae-82867e89eb04/
- https://base.garant.ru/66655905/
- https://base.garant.ru/39771433/
- https://rdap.db.ripe.net/autnum/35645
- https://rdap.db.ripe.net/entity/ORG-LLC12-RIPE
- https://stat.ripe.net/data/as-overview/data.json?resource=AS35645
- https://stat.ripe.net/data/announced-prefixes/data.json?resource=AS35645
- https://stat.ripe.net/data/as-routing-consistency/data.json?resource=AS35645
- https://bgp.tools/as/35645
- https://bgp.he.net/AS35645
- https://asrank.caida.org/asns/35645
- https://asrank.caida.org/orgs/53d16b8f3f
- https://ipinfo.io/AS35645#summary
- https://www.ipxo.com/asn/AS35645/
- https://ipinfo.io/AS35645/95.66.227.0/24
- https://ipinfo.io/AS35645/95.66.216.0/22
- https://ipv4.bgp.he.net/net/95.66.222.0/23
- https://www.rayonline.ru/o-kompanii/
- https://www.rayonline.ru/tarify-i-uslugi/dlya-fizlicz/internet/
- https://www.rayonline.ru/tarify-i-uslugi/dlya-fizlicz/internet-tv/
- https://www.rayonline.ru/tarify-i-uslugi/dlya-yurlicz/
- https://www.rayonline.ru/tarify-i-uslugi/dlya-fizlicz/telefoniya/
- https://www.rayonline.ru/tarify-i-uslugi/dlya-fizlicz/videonablyudenie/
- https://www.rayonline.ru/tarify-i-uslugi/dlya-fizlicz/domofony/
- https://www.rayonline.ru/tarify-i-uslugi/dlya-fizlicz/televidenie/interaktivnoe-televidenie/
- https://www.rayonline.ru/dokumenty-dlya-podklyucheniya-internet/
- https://www.rayonline.ru/wp-content/uploads/2022/08/dogovor-oferta.pdf
- https://www.rayonline.ru/wp-content/uploads/2025/11/pravila-okazaniya-uslug-svyazi-new-2025.pdf
- https://vladimir.justconnect.ru/p/vladinfo/
- https://vladimir.justconnect.ru/#providers
- https://dominternet.ru/vladimir/tariffs/internet/
- https://101internet.ru/vladimir/rating/vladinfo
- https://2gis.ru/vladimir/geo/8304147468127056/tab/providers
- https://www.vedomosti.ru/technology/articles/2025/11/14/1154822-rinok-oborudovaniya-dlya-fiksirovannoi-svyazi-otsenili
- https://dgap.org/en/research/publications/impact-and-limits-sanctions-russias-telecoms-industry
- https://blog.cloudflare.com/russian-internet-users-are-unable-to-access-the-open-internet/
- https://www.hrw.org/report/2025/07/30/disrupted-throttled-and-blocked/state-censorship-control-and-increasing-isolation
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance