
Summary
- Patrick Coffey is publicly identified by Gelber Group as Chief Operating Officer, with a role that spans trade support, human resources, clearing, and settlements.
- The reliable record places Coffey at Gelber in 2010 leading the Forex Trading technology team, and places Patrick Joseph Coffey in a FINRA-listed Chief Operating Officer/Principal Operations Officer role at Gelber Securities from July 2020.
- The useful infrastructure signal is not a single registry entry. It is the convergence of company leadership material, a Trading Technologies training-program release, FINRA firm records, and public network-resource evidence for AS22104.
- The record has limits: no independent long-form interview was captured, no public failure episode attributable to Coffey was verified, FINRA disclosure material is firm context rather than a personal allegation, and WHOIS evidence corroborates identity and operating surface rather than driving the profile.
The Operating Layer The Public Record Reveals
Patrick Coffey is easiest to misunderstand if he is treated as a conventional finance executive whose significance begins and ends with title. The public record supports a more specific reading. Gelber Group's leadership page identifies Pat Coffey as Chief Operating Officer and describes a scope that reaches into trade support, human resources, clearing, and settlements. That is not a decorative list.
In a proprietary trading firm, those functions sit close to the machinery that determines whether strategy can become execution, whether execution can become a reconciled trade, and whether a firm can keep expanding technology use without letting operational control lag behind.
Gelber describes itself as a Chicago-based global proprietary trading company founded in 1982 and powered by technology. Its own trading material emphasizes diverse strategies and command of technology, while a company social profile describes specialties that include proprietary, discretionary, algorithmic, options, and futures trading. Those claims are company-controlled and should be read as positioning, not independent assessment. Still, they matter because they define the operating environment in which Coffey's role is publicly presented.
A COO at a firm that sells itself around trading technology is not merely supervising office process. The role is adjacent to platform readiness, trader support, settlement discipline, internal handoffs, compliance-facing records, and the unglamorous work of making a high-speed trading culture operationally legible.
The narrower facts are more useful than a broad biography would be. Gelber says Coffey joined the firm in 2010 to lead the Forex Trading technology team. That detail gives the profile its arc. His public career at Gelber begins, in the available company account, with a technology role inside a trading unit rather than with a purely administrative appointment. Today, the same company places him in operations. The path from foreign-exchange trading technology to COO is not documented in detail by the captured sources, and this article should not pretend otherwise.
But the two endpoints establish a meaningful pattern: Coffey is publicly associated with the bridge between trading systems and the operating controls that surround them.
That bridge is where infrastructure readers should pay attention. Finance coverage often reserves the word "infrastructure" for exchanges, data centers, cloud platforms, network vendors, or payment rails. Inside a trading firm, however, infrastructure also appears as the set of internal practices that make those external systems usable: trader onboarding, market-access support, clearing processes, settlement routines, records for regulators, and contact points for public network resources. Coffey's profile sits in that internal layer.
It is not a story about founding Gelber, designing every network relationship, or personally selecting every counterparty. The evidence does not say those things. It is a story about an executive role whose public contours show how a proprietary trading firm organizes the work around its trading technology.
The difference matters because modern trading firms are operational organisms. Their most visible output is trading activity, but the durable capability depends on the control surfaces underneath. A platform must be taught before it can be used well. A trade must be supported before it can be scaled. A settlement process must be reliable before profitable activity can be safely repeated. A public regulatory record must be kept distinct from personal blame, but it still tells readers where the firm's regulated surface begins.
A WHOIS contact row should not become the headline, but it can help corroborate that a named executive is also visible in the firm's technical-administrative footprint. Coffey's public record draws a line through those surfaces without giving enough evidence to turn him into a symbol for every decision Gelber has made.
That is the profile's value. It asks readers to look at an operations executive without turning operations into vague corporate housekeeping. The available facts show a person named in the company's leadership layer, tied by the company's own biography to trading technology, named by FINRA in a principal operations role at an affiliated broker-dealer, quoted by a trading-platform vendor in connection with training and accreditation, and visible in ARIN-derived network-contact evidence for Gelber's public number resources. Each element is limited.
Together, they make Coffey a useful lens on the middle of the trading stack: the place where people, systems, controls, and settlement obligations meet.
From Forex Trading Technology To Operations
The clearest biographical starting point is Gelber's statement that Coffey joined in 2010 to lead the Forex Trading technology team. The phrase is compact, but it carries operational weight. Foreign-exchange trading is a market where technology, latency, market data, platform fluency, counterparty process, and risk controls interact constantly. A person leading technology for such a team would be operating in a zone where technical decisions and trader behavior are difficult to separate. The record does not say which systems Coffey implemented, which vendors he chose, or which architecture he preferred.
It only supports the fact of his role. But even that fact places him in a part of the firm where trading infrastructure was not abstract.
The move from that 2010 role to a COO position gives the public record an institutional logic. Operations in a trading firm are not downstream from technology in a simple sense. They often become the discipline that decides whether technology remains usable under pressure.
A trading desk can add a new platform, strategy, or market access path, but the value of that addition depends on whether support teams know how to handle breakage, whether back-office processes can reconcile the resulting activity, whether clearing and settlement teams can absorb the operating load, and whether the firm can explain its operating structure when regulators or counterparties ask. The sources do not document Coffey's internal decisions, but his public trajectory makes sense against that background.
Gelber's leadership page describes Coffey's current operating scope as including trade support, human resources, clearing, and settlements. Those functions can look unrelated from a distance. In practice, they converge on readiness. Trade support is the interface between trading desks and the systems they use. Human resources is not merely hiring paperwork when the product is skilled trading labor; it affects who can be trained, supervised, and retained. Clearing is the institutional process that turns executed trades into obligations recognized through clearing arrangements.
Settlement is where those obligations become final enough for the firm to account for them, reconcile them, and continue. A COO spanning those areas is positioned where human capacity, technology support, and post-trade discipline intersect.
The available record does not permit a heroic version of that story. It does not show Coffey single-handedly transforming Gelber's systems, building a new settlement architecture, or rescuing a failed operation. There is no independent long-form interview in the available sources, and no public failure episode attributable to him was verified. That absence is important. It means the profile should be written from observable surfaces rather than from narrative closure. The available documents show a role, a tenure marker, a technology starting point, a regulatory title, and a few external confirmations.
They do not show private deliberations or a full career chronology.
Still, a limited record can say something important if it is read with care. In many infrastructure businesses, the most consequential people are visible only through the systems they help keep coherent. They appear in administrative contact fields, regulatory records, vendor releases, leadership pages, and program endorsements. None of those surfaces alone defines a career. Together, they show where responsibility is publicly placed.
Coffey's placement is consistent: Gelber's operating core, its trading-technology culture, its broker-dealer operations role, and its public network-resource administration all point toward the same firm context.
The 2010 date also prevents an overly static reading. Coffey is not presented only as a newly named executive on a current leadership page. The company biography reaches back more than a decade, and the FINRA report places Patrick Joseph Coffey in a Chief Operating Officer/Principal Operations Officer role at Gelber Securities with a July 2020 position start date. Those are different institutional surfaces. Gelber Group's corporate biography says he joined the broader firm in 2010; FINRA's broker-dealer record identifies a regulated role that begins in 2020.
Keeping those dates separate avoids a common error in executive profiles: collapsing a company career, a regulatory appointment, and a current title into one vague sentence. In Coffey's case, the distinction is a feature. It shows how a person can be part of a firm for years before appearing in a specific regulated operating role.
Why Operations Is Infrastructure In A Trading Firm
Calling Coffey an infrastructure figure may sound unusual only if infrastructure is defined too narrowly. Proprietary trading depends on market access, trading platforms, connectivity, clearing arrangements, data handling, internal supervision, and people who know how to operate within those systems. Some of that infrastructure is physical or technical. Some is legal and procedural. Some is cultural: training, escalation, and the habits that decide whether a trader treats a platform as a black box or as a tool with documented limits.
Gelber's own public description emphasizes technology as part of its trading identity. That positioning makes operations more central, not less. A firm that claims technology as a core advantage has to maintain a disciplined relationship between innovation and control. New tools create new failure modes. More automated or platform-mediated trading can increase the need for consistent training. Diverse strategies can make support and reconciliation more complex. A global proprietary trading identity can widen the number of markets, instruments, and operational handoffs a firm has to manage.
The sources do not enumerate Gelber's internal systems, and they should not be made to. But they give enough context to understand why a COO with a trading-technology background is relevant to infrastructure coverage.
Trade support is a particularly revealing phrase. It is easy to treat support as reactive: something that appears only when a system breaks or a user needs help. In trading, support is part of the control environment. It determines how quickly issues are identified, how platform knowledge is distributed, how desks communicate with operations teams, and how a firm learns from recurring problems. A support function with weak knowledge transfer can leave a trader dependent on informal fixes. A strong support function can turn platform experience into shared operating practice.
The record does not tell readers how Gelber's trade support team is organized, but Coffey's public scope includes that function, which means the COO role is connected to the day-to-day reliability of trading activity.
Clearing and settlements add a second layer of significance. Trading strategies may attract attention at the moment of execution, but the institutional test continues after the trade. Clearing and settlement determine whether executed activity is processed in a way that counterparties, clearing relationships, books, and regulators can recognize. Those processes are not glamorous, yet they are fundamental to the trustworthiness of a trading firm. If a company describes itself as technology powered and trading focused, then its post-trade operations are part of the technology story. They are where fast activity becomes auditable obligation.
Human resources might seem further from infrastructure, but in this context it belongs in the same operating map. Proprietary trading firms rely on skilled people whose platform competence, judgment, and risk awareness can shape firm outcomes. Hiring, training, retention, and role definition all influence how technology is used. A firm can buy access to a platform, but it cannot buy institutional fluency fully formed. The people layer has to be recruited, trained, evaluated, and supported.
When Gelber lists human resources within Coffey's operating scope, it places him near the part of the firm that turns labor into repeatable trading capability.
This is why the profile should avoid a generic finance biography. The public record is not rich in personal narrative, awards, education, or private motivations. It is rich enough in operating surfaces. That is more valuable for readers trying to understand how trading firms become durable institutions. Coffey's significance in the record is not that he is famous. It is that his visible role touches several systems that readers often study separately: trading technology, platform training, broker-dealer operations, clearing and settlement, and network-resource administration.
The TT Accreditation Signal
One of the few public moments in the record where Coffey appears outside Gelber's own site or a regulatory source is a Trading Technologies release from November 2024. The release announced the launch of the TT Accreditation program and identified Patrick Coffey, COO at Gelber Group, as a public supporter of the program. It also said Gelber enrolled traders in TT Accreditation and recommended the program to participants in theBreakout, a simulated futures and foreign-exchange trading competition that Gelber sponsored on Trading Technologies' platform.
That fact should be handled carefully. A vendor release is not independent investigative reporting, and it naturally presents the program in a favorable light. It also does not prove that Coffey personally designed Gelber's platform-training strategy or selected every element of its relationship with Trading Technologies. What it does show is more modest and more useful: Coffey was willing to be publicly associated with a training and accreditation mechanism for trading-platform use. In the context of his broader operating role, that public association is a meaningful signal.
Training is an infrastructure issue because trading platforms are not neutral surfaces. They encode order-entry routines, risk controls, market access paths, interface conventions, data displays, and operational assumptions. A trader who uses a platform without enough fluency can create errors that look like human mistakes but originate in weak institutional preparation. Accreditation programs are one way firms and vendors try to standardize knowledge. They make platform competence more explicit. They can also create a shared vocabulary between traders, support staff, and operations leaders.
The TT release links Gelber to both formal accreditation and simulated competition. That combination is notable. A simulated futures and FX trading competition can be framed as recruiting, training, assessment, or brand positioning, depending on how a firm uses it. The captured source only supports the specific claims that Gelber sponsored theBreakout on TT's platform and recommended TT Accreditation to participants. It does not support broader conclusions about hiring outcomes, trader performance, or internal evaluation.
Still, the public connection between simulated trading, accreditation, and Gelber's COO aligns with the profile's central theme: operations is where technology use becomes disciplined practice.
The quote reported by Trading Technologies also helps distinguish Coffey from a purely internal administrator. He appears in a public vendor context tied to platform literacy. That does not make him a product evangelist in the ordinary marketing sense. It places him in a small but revealing public role: an operations leader speaking around trader training and platform readiness. For a proprietary trading firm, that is not peripheral. It is part of the way the firm manages the distance between tool availability and competent use.
The phrase "recommended it to theBreakout participants" also deserves attention. Recommendation is not compulsion. The source does not state that every participant completed the program, that accreditation was mandatory for employment, or that Gelber made the program a universal internal requirement. A precise article should not claim those things. But a recommendation from a sponsoring firm to competition participants suggests that Gelber saw platform education as relevant to the simulated environment it helped support.
If readers are watching how trading firms cultivate technical skill outside formal employment, this is a useful clue.
In that sense, the TT Accreditation episode is less about a press release and more about a public training architecture. It shows a proprietary trading firm, a major trading-technology vendor, a simulated futures and FX competition, and an operations executive connected in one documented event. The profile does not need to inflate that event to make it matter. It matters because it offers a glimpse of how talent, technology, and operating discipline meet before a trade becomes real capital at risk.
Clearing, Settlement, And The Broker-Dealer Surface
The FINRA material gives Coffey's profile a regulated surface, but it must be read with restraint. FINRA BrokerCheck identifies Gelber Securities, LLC, CRD# 18367, and identifies Patrick Joseph Coffey, CRD# 7262848, in a Chief Operating Officer/Principal Operations Officer role. The BrokerCheck report places his position start date at July 2020 and indicates that the role directs management or policies of the firm. It also provides firm-operation context, including registered status and clearing or carrying relationships.
Those facts are important because they connect the broader Gelber operations profile to a broker-dealer record. They do not turn every item in the firm's regulatory history into a personal story about Coffey. The available records do not tie the listed historical firm regulatory events personally to him. A careful profile should treat the FINRA disclosure material as firm context. That means it can help readers understand the regulated environment around Gelber Securities, but it should not be used as an allegation against Coffey unless an available source says so directly.
The Principal Operations Officer detail is still meaningful. It suggests a formalized operations role inside the broker-dealer entity, not just a business-card title at the broader group level. FINRA's language that the role directs management or policies of the firm is also significant, but it should be quoted conceptually rather than overextended. It says the role has management or policy direction within the firm. It does not specify which internal decisions Coffey made, which relationships he approved, or how Gelber allocated responsibility among executives.
The distinction matters because regulated records can be tempting to overread. They are precise in some areas and silent in others.
For infrastructure readers, the broker-dealer context matters because clearing and settlement are not background noise. They are where the firm interfaces with rules, counterparties, and post-trade obligations. BrokerCheck's indication of clearing and carrying relationships gives readers a formal signal that the firm operates within a clearing environment. It does not identify Coffey as the personal selector of those relationships, and this article should not imply that. It does reinforce that Coffey's public operations role is situated in a firm where clearing structure is not incidental.
Gelber Group's leadership page says Coffey's operations scope includes clearing and settlements. FINRA's firm report describes broker-dealer context that includes clearing or carrying relationships. Put together, the two sources show a coherent public picture: Coffey's role sits near the post-trade layer where proprietary trading activity has to become settled, recorded, and operationally controlled. That is a stronger and fairer point than saying he is responsible for any particular clearing arrangement. The first claim is supported by the sources. The second is not.
The article's angle also benefits from keeping Gelber Group and Gelber Securities distinct. Gelber Group is the proprietary trading company in the company materials. Gelber Securities is the FINRA-regulated broker-dealer firm in BrokerCheck. They are related in the public record through the Gelber context, but they are not identical surfaces. Coffey's company biography and his FINRA-listed role should therefore be held together without being merged carelessly.
A reader should be able to see when the article is referring to Gelber Group's public leadership page and when it is referring to Gelber Securities' regulated firm record.
That kind of precision is part of editorial fairness, but it is also part of infrastructure analysis. Systems are built from boundaries. A trading group, a broker-dealer, a platform vendor, a clearing arrangement, and a public network allocation are different kinds of institutional objects. The more clearly those boundaries are described, the better readers can understand what Coffey's public role does and does not show.
The Public Network Footprint, Without Making It The Spine
The network-resource evidence in the file is useful but easy to overstate. An IPIP.NET WHOIS mirror of ARIN data shows AS22104 / Gelber Group, LLC, a 208.86.28.0/22 allocation, and an organization administrative contact listed as Coffey, Patrick / COFFE15-ARIN with a Gelber email. IPinfo corroborates AS22104 Gelber Group, LLC and a visible public prefix in the same network surface. These are real signals. They help connect Coffey's name to the firm's public technical-administrative footprint. They do not, by themselves, prove how Gelber's network is designed, operated, outsourced, monitored, or secured.
That distinction should shape how the evidence appears in the profile. A WHOIS administrative contact can indicate who is visible as an organizational contact for number resources. It is not a job description. It is not a network architecture diagram. It does not say that the named person configures routers, negotiates transit, manages peering, or chooses hosting arrangements.
In Coffey's case, the WHOIS evidence is valuable because it converges with stronger identity sources: Gelber's leadership page, FINRA's role record, and the Trading Technologies release all place Patrick Coffey or Patrick Joseph Coffey in the Gelber operating context. The ARIN-derived contact record then adds a technical-administrative echo.
AS22104 also shows why a proprietary trading firm belongs in infrastructure coverage even when the article is about a person. Trading firms are not only users of financial markets. They are networked institutions. Their public IP resources, routing surfaces, vendor platforms, and trading systems are part of the environment in which market activity happens. The evidence here does not support a detailed technical map of Gelber's network, and it would be irresponsible to invent one. It does support the statement that Gelber has a measurable public network surface associated with AS22104 and relevant IP prefixes.
The presence of Coffey's name in the ARIN-derived administrative-contact evidence is especially interesting when read alongside his COO role. It suggests that at least some public number-resource administration aligns with the same executive identity visible in Gelber's operating leadership. But again, the article should not turn that into a claim about personal network administration. The strongest wording is cautious: the record ties Coffey to the administrative contact layer for Gelber's public network allocation, which corroborates his operating-surface relevance. That is enough.
The network detail also guards against an overly soft profile. Without it, Coffey could appear only as a company-page executive and a FINRA-listed principal. With it, readers see that the operations layer touches public technical identifiers. In trading, those identifiers are rarely the whole story, but they are part of the observable footprint. They help show where a firm exists in the internet's administrative systems, even if they do not explain how the firm routes traffic day to day.
For readers who follow internet infrastructure, the temptation is to make AS22104 the hook. That would be the wrong emphasis. The available records do not support promoting ARIN or WHOIS contact data alone. The article's hook is Coffey's broader operating role at a technology-driven proprietary trading firm. The network-resource record is a supporting rail. It strengthens identity and operating-surface analysis, but it should not carry the entire profile.
What The Public Sources Do Not Say
The limits of Coffey's public record are not a weakness to hide. They are part of the story. The captured sources do not include an independent long-form interview with him. They do not include an investigative account of Gelber's internal operations. They do not verify a public failure episode attributable to him. They do not provide a detailed list of systems he selected, controls he designed, brokers he approved, clearing relationships he negotiated, cloud infrastructure he chose, or network arrangements he personally supervised. A responsible article has to keep those absences visible.
This is especially important with executive operations profiles because operations roles invite inference. If a COO's public scope includes clearing and settlements, a reader may assume that every clearing relationship is personally his. If a FINRA report lists a principal operations role, a reader may assume that every historical firm disclosure is personal. If a WHOIS contact row lists an executive's name, a reader may assume technical ownership of network infrastructure. None of those jumps is warranted by the captured evidence.
The better approach is to write from institutional proximity rather than personal omniscience. Coffey is publicly proximate to trading technology through his 2010 Forex Trading technology role. He is publicly proximate to operational control through Gelber's description of his COO scope. He is publicly proximate to broker-dealer management through FINRA's Chief Operating Officer/Principal Operations Officer listing. He is publicly proximate to platform training through the Trading Technologies accreditation release. He is publicly proximate to network-resource administration through the ARIN-derived contact evidence.
Proximity is not the same as sole responsibility, but it is still informative.
Company-controlled sources require another caveat. Gelber's leadership page and home and trading pages are primary sources for how the company presents itself. They are valuable because they are official, but they are not independent verification of performance. The company's language about being powered by technology, pursuing diverse strategies, or maintaining a command of technology should therefore be attributed. It can explain the firm's self-conception. It should not be repeated as a neutral verdict.
The Trading Technologies release has a similar limitation. It is a vendor communication, useful for documenting a public quote, program participation, and Gelber's recommendation of TT Accreditation to theBreakout participants. It is not an independent assessment of whether the program improved trader quality or operational safety. The article can say the release placed Coffey in a public conversation about platform accreditation. It cannot say, based on that source alone, that the program changed Gelber's outcomes.
The secondary sources in the file are corroborating rather than controlling. LinkedIn supports organization context and specialties. The Org corroborates the COO role and operations-department wording in an org-chart setting. They help reduce same-name risk, but they are not the spine of the article. The primary sources and market-signal sources do the heavier work.
Those boundaries make the profile more credible. Readers do not need a falsely complete biography. They need to know what can be said, why it matters, and where the evidence stops. Coffey's profile is strongest when it remains a study of operating surfaces rather than a biography padded with unsupported color.
The Human Side Of A Technical Operations Role
Because the record is institutional, it can be easy to lose sight of the person. But the person matters precisely because the role connects systems that are often treated as impersonal. A trading platform does not train itself. A support team does not become effective by accident. Clearing and settlement processes do not remain reliable without people who make obligations, exceptions, and escalations part of normal operating discipline. A regulatory title does not guarantee sound judgment, but it places a named individual within the structure that regulators can see. Coffey's public identity is attached to those points of contact.
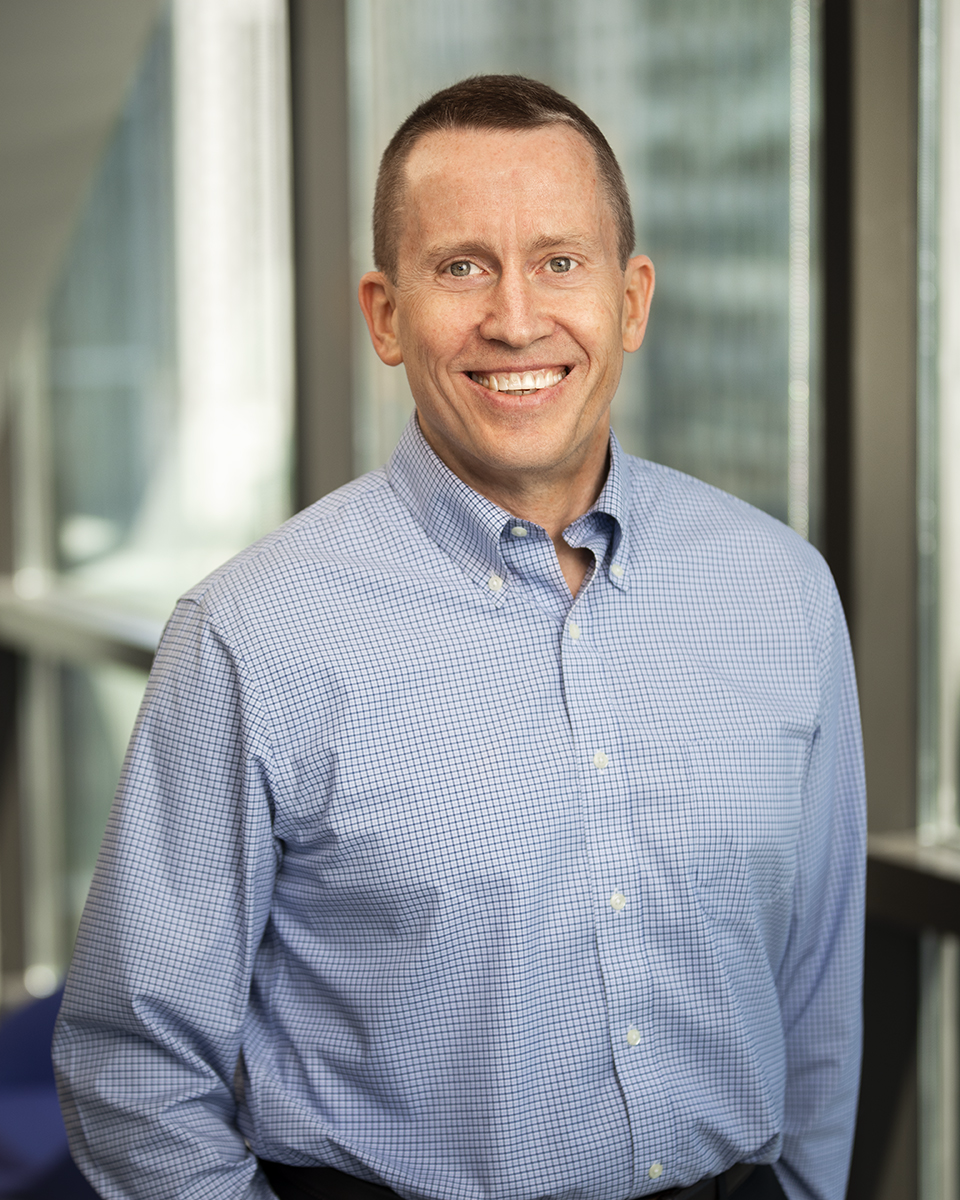
Gelber's official headshot and leadership page provide a public face-photo signal, which is relevant for image treatment but also editorially suggestive. The company presents Coffey as part of its leadership group, not as a hidden back-office function. That public presentation aligns with the Trading Technologies release, where he appears in connection with training and platform accreditation. The available record therefore shows an operations executive who is public enough to be named and imaged, but not public in the celebrity-executive sense. The profile should preserve that scale.
There is a broader lesson here about people in infrastructure. The most visible technology stories often center on founders, inventors, or crisis managers. Coffey's record points to another type: the operator whose work is visible through recurring institutional interfaces. He appears where a firm introduces its leadership, where a regulator lists operational control, where a vendor documents platform-training adoption, and where public number-resource records show an administrative contact. None of those surfaces is dramatic. All of them are part of how a firm remains operational.
The absence of personal color also protects the article from invention. There is no need to add unsupported detail about Coffey's management style, private motivations, family history, education, or views on markets. The article can respect the reader by staying with what is documented. In an environment where executive profiles often become soft promotion, restraint is a form of service. It lets the operating facts stand.
That restraint does not make the profile thin. Operations itself supplies the substance. A person whose role spans trade support, human resources, clearing, and settlements sits near the question of how a proprietary trading firm turns strategy into repeatable institutional behavior. A person whose earlier company role was leading Forex Trading technology sits near the question of how systems knowledge moves into management. A person publicly associated with platform accreditation sits near the question of how traders are prepared to use tools.
A person named in broker-dealer operations records sits near the question of how regulated firm responsibilities are assigned. Those are concrete questions, even when the source file is not intimate.
The key is to avoid making Coffey a proxy for all of Gelber. The company has its own history, strategy, technology choices, regulatory footprint, and network resources. The captured sources do not give enough evidence to personalize every one of those elements. Coffey is a lens, not the whole institution. The profile is about the part of Gelber's public record that passes through his role.
Why This Profile Matters For Infrastructure Readers
Infrastructure readers should care about Coffey's profile because it shows how trading infrastructure becomes organizational. Public internet records can identify a network surface. Regulatory records can identify a broker-dealer operating role. Company material can identify a trading-technology culture and an operations remit. Vendor releases can identify training and accreditation activity. But markets do not run on records alone. They run through firms whose people have to make those records correspond to functioning systems.
Gelber's public materials place technology at the center of its trading identity. The TT Accreditation release shows one way that platform knowledge can be formalized. The FINRA record shows a regulated operations surface for Gelber Securities. The AS22104 evidence shows a public network surface associated with Gelber Group. Coffey's name appears across those domains in different ways. That does not make him the architect of all of them. It does make him a useful figure through whom to study the operational middle of a trading firm.
The operational middle is easy to ignore because it often works best when nothing visible happens. A well-supported platform does not produce a headline when traders know how to use it. A well-run settlement process does not attract attention when obligations reconcile. A clear administrative contact does not matter to most readers until network-resource questions arise. A principal operations role may sit quietly in a regulatory report until someone needs to understand who directs management or policies of the firm. The absence of drama can make infrastructure look less important than it is.
Coffey's profile pushes against that bias. It suggests that readers should treat operations as part of the infrastructure of markets, especially in firms where technology and trading are tightly coupled. It also shows why careful attribution matters. If an article overclaims, it turns operations into mythology. If it underclaims, it misses the institutional significance of the role. The right balance is to say that Coffey's documented role is centered on the connective tissue of a trading organization: support, people, post-trade process, regulated operations, and technical-administrative visibility.
The same balance applies to risk. No public failure episode attributable to Coffey was verified in the captured materials. That does not mean the firm has no risks, and it does not mean operations work is risk-free. It means this profile should not manufacture a controversy. The sharper analytical point is that Coffey's public role exists in areas where trading firms manage risk every day: platform use, support, staffing, clearing, settlement, and broker-dealer operations. Those are risk-bearing systems even when no scandal is present.
There is also a commissioning lesson for future coverage. If more reporting were available, the most useful questions would not be generic ones about leadership. They would ask how Gelber trains traders on platforms, how trade support coordinates with desks, how operations teams handle post-trade exceptions, how broker-dealer responsibilities are divided, and how public network-resource administration fits into the firm's technology governance. Those questions follow directly from the record. They do not require pretending the current file answers them.
For now, the fixed record supports a precise conclusion: Patrick Coffey is a Gelber Group operations executive whose public footprint links trading technology, platform training, clearing and settlement, regulated broker-dealer operations, and public network-resource evidence. That is enough to make him relevant to infrastructure readers. It is not enough to assign him every technical, clearing, or regulatory decision connected to Gelber. The value lies in the disciplined middle: a person profile that treats operations as the place where market technology becomes accountable institutional practice.
Evidence Notes
The article relies on a limited set of public records. Gelber Group's leadership page identifies Patrick Coffey, also presented as Pat Coffey, as Chief Operating Officer; says he joined Gelber in 2010 to lead the Forex Trading technology team; describes his operating scope as trade support, human resources, clearing, and settlements; and provides the official public headshot provenance.
Gelber's home and trading pages supply company-controlled context for Gelber's self-description as a Chicago-based global proprietary trading company founded in 1982 and powered by technology, with trading material emphasizing strategy diversity and technology command.
FINRA BrokerCheck identifies Gelber Securities, LLC, CRD# 18367, and Patrick Joseph Coffey, CRD# 7262848, in a Chief Operating Officer/Principal Operations Officer role. The BrokerCheck report places the position start date at July 2020, indicates that the role directs management or policies of the firm, and supplies firm-operation context including registered status and clearing or carrying relationships. Those records are used here as regulated firm context. They are not used as personal allegations, and they are not treated as evidence that Coffey personally chose every relationship or policy mentioned in the firm record.
Trading Technologies' November 2024 announcement of TT Accreditation identifies Coffey as COO at Gelber Group in connection with the program. The release says Gelber enrolled traders in TT Accreditation and recommended the program to theBreakout participants after Gelber sponsored that simulated futures and FX trading competition on TT's platform. Because the release is a vendor source, the article uses it for documented participation, public association, and training context rather than for claims about program efficacy.
The network-resource evidence is supporting context. An IPIP.NET WHOIS mirror of ARIN data shows AS22104 / Gelber Group, LLC, a 208.86.28.0/22 allocation, and an administrative contact listed as Coffey, Patrick / COFFE15-ARIN with a Gelber email. IPinfo corroborates AS22104 Gelber Group, LLC and a visible public prefix. These records help establish a public technical-administrative surface connected to the firm and Coffey's identity, but they are not treated as a complete account of Gelber's network operations.
LinkedIn and The Org are used only as corroborating secondary sources for organization context, specialties, office or scale context, and the COO/org-chart framing. They do not replace primary company, regulatory, vendor, or network-resource sources. The final caveat is simple: the evidence supports a careful operations-and-infrastructure profile. It does not support a full personal biography, a failure narrative, or claims that Coffey personally directed every technical, broker, clearing, or network relationship in Gelber's public footprint.