
Summary
- AFRINIC disclosed legal costs of USD 1,250,527 for 2022, USD 1,133,630 for 2023, USD 27,322 for 2024 and USD 877,929 for 2025. The four figures sum exactly to USD 3,289,408, but they are accounting disclosures, not transaction-by-transaction proof of cash settlement.
- The provider tables attribute USD 2,148,059 across 2022 and 2023 to C&A Law and USD 1,141,349 across all other named-provider lines. Historical records prove that some authority existed in 2021 and early 2022; a later judgment proves a specific authority failure for identified 2023 proceedings. Neither proposition decides every transaction in the four-year total.
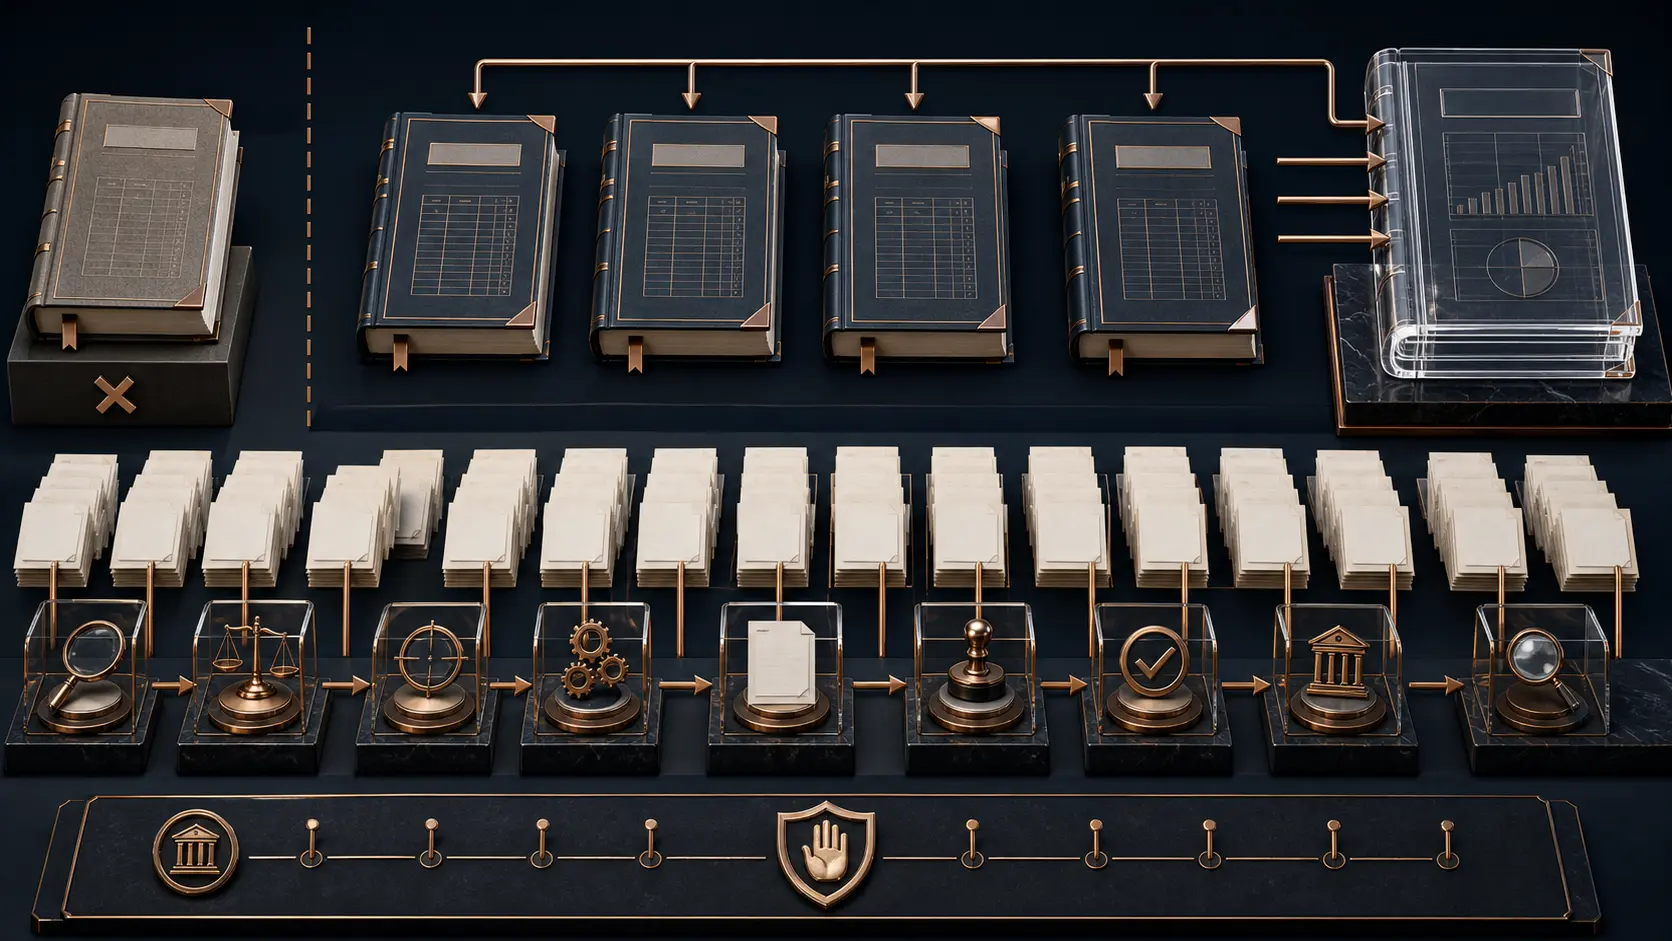
- NRS’s answer is a nine-stage file joining each matter to its corporate purpose, retainer, authorised instruction, invoice, approval, payment execution, accounting treatment, audit work and member consideration. Until that file exists, the arithmetic is closed and the authority record remains open.
Analysis
The most revealing number in AFRINIC’s legal-cost record is not hidden. It can be produced with four entries and one line of addition:
2022 USD 1,250,527 + 2023 USD 1,133,630 + 2024 USD 27,322 + 2025 USD 877,929 = USD 3,289,408.
On 24 June 2026, NRS published that reconciliation and asked AFRINIC’s members to demand the authority behind the spending before approving the corresponding financial statements. The intervention matters because it did not need to guess at an aggregate. AFRINIC’s own annual finance disclosures provide the component figures. The contest begins at the next level down: what acts, people, instruments and controls sit behind each recognised cost?
That distinction is easy to blur. A figure can be exact without being a complete account of the transaction that produced it. An annual expense table can identify a provider and a reporting period without showing the date cash moved. Audited financial statements can support the presentation of accounts without adjudicating whether the person who instructed a particular pleading held corporate authority on that day. A general meeting can consider those statements without becoming the original signatory to a retainer or the contemporaneous approver of an invoice.
The words therefore matter. USD 3,289,408 is the exact sum of AFRINIC’s disclosed legal-cost totals for the four financial years. It is not, on the public record assembled here, a bank-proven cash total. The costs may include paid items, accruals, disbursements or accounting treatments whose settlement dates and gross-or-net tax treatment are not visible in the public tables. NRS uses the language of payment in its member-action case, but the official public package does not contain the bank confirmations, mandates and signatory records needed to establish cash movement one transaction at a time.
The provider arithmetic closes just as neatly. In 2022, AFRINIC listed Me Ashok Radhakissoon at USD 31,514, Denton Mauritius — Solicitors at USD 122,733, a “Contempt of Court — POA / Legal Fees” line at USD 12,530, and C&A Law at USD 1,083,750. Those four entries total USD 1,250,527. In 2023, the table listed Me Ashok Radhakissoon at USD 27,885, Denton Mauritius (Solicitor) at USD 30,116, C&A Law (Lawyer) at USD 1,064,309 and Previous Directors’ Lawyers at USD 11,320. Those entries total USD 1,133,630. The 2024 figure was USD 27,322, entirely labelled to Me Ashok Radhakissoon.
In 2025, the listed amounts were USD 26,933 for Me Ashok Radhakissoon, USD 464,708 for Trinity Legal, USD 31,333 for BLC Chambers, USD 353,000 for Me Mohammad M Namdarkhan and USD 1,955 for A.O. Popoola LP, producing USD 877,929.
Two sums establish the concentration without overclaiming it. The C&A-labelled figures are USD 1,083,750 + USD 1,064,309 = USD 2,148,059, or about 65.3023 per cent of the four-year aggregate. Every other named-provider line across 2022–2025 totals USD 1,141,349. Together, USD 2,148,059 + USD 1,141,349 = USD 3,289,408.
This is an accounting attribution, not an accusation against a provider. The tables do not allocate every line to a court matter, explain every deliverable, establish the reasonableness of a fee, or show who benefited from each instruction. They also do not justify collapsing the entire figure into one dispute, one election, one law firm or one office-holder. Even the dominant C&A subtotal is not independently proved as cash paid to the firm. AFRINIC labels the annual amounts to C&A; NRS characterises them as paid; the public bank evidence required to close that difference was not located.
One adjacent number must remain outside the calculation. AFRINIC’s 2022 material includes a 2021 comparative legal-fee total of USD 633,807. That is useful as historical context, but it is not part of NRS’s commissioned 2022–2025 reconciliation. Adding it would change the period and produce a different object. The four-year figure remains USD 3,289,408. The 2021 amount remains an excluded comparator, not a fifth year smuggled into the total.
The same discipline separates this inquiry from narrower stories. The 2025 total of USD 877,929 is one component of the four-year record; a provider-by-provider account of 2025 alone asks a different question. The located C&A engagement letter contains one USD 1,000-per-hour professional-fee rate including Anwar Moollan SC’s professional fees, exclusive of value-added tax and disbursements. That contract term, and any theory that a later meeting could validate earlier acts, belong to a separate inquiry. This report does not turn an hourly-rate question or blanket retroactive-validation thesis into its centre.
Its object is the join between four years of accounts and the authority for each underlying transaction.
The counter-evidence that a serious inquiry must keep
An honest authority audit cannot begin from the claim that C&A never had a mandate. A quorate AFRINIC Board acted on 23 August 2021. Resolution 202108.630 retained a named legal team and delegated broad litigation powers to then-chief executive Eddy Kayihura. A C&A Law engagement letter was dated 20 October 2021, stamped as received by AFRINIC on 21 October and accepted by Eddy Mabano Kayihura in his capacity as CEO on 25 October.
Two invoice decisions are also in the minutes. On 27 October 2021, the Board approved payment of C&A invoice PRI10581. The amount is redacted. The chair declared a conflict and abstained because the invoice included fees for a case against the chair. On 26 January 2022, the Board approved payment of further redacted C&A invoices for a redacted amount and asked that the engagement be shared with the Board.
These records matter for more than balance. They prove that “no retainer, no delegation and no invoice approval ever existed” would be false. They show a real corporate control surface: a quorate Board retained counsel, delegated powers to a serving CEO and approved identified invoices. They also show how a proper record can work. The actor, date, office, resolution or invoice identifier, conflict handling and decision are visible, even though redaction prevents the amount-level tie-out.
What they do not prove is equally important. The located engagement does not identify every later matter instruction, amendment, invoice, approval, bank mandate, transfer or accounting entry. The October 2021 and January 2022 minutes cannot be reconciled to the C&A-labelled USD 2,148,059 because key amounts and identifiers are unavailable. A valid delegation has duration and scope; it does not renew itself merely because the provider relationship continues.
AFRINIC’s consolidated report supplies the temporal break. It says the Board lost the quorum required to conduct business in June 2022. Kayihura’s contract ended on 3 November 2022, leaving AFRINIC without a CEO from 4 November. Those dates do not automatically erase everything that followed. They do, however, make later authority a document question. For a post-quorum or post-CEO act, the file must show the Board, court, Receiver or other valid instrument relied upon at that time.
What 2024 SCJ 473 decided—and what it did not
The Court of Civil Appeal’s 2024 SCJ 473 judgment provides a rare transaction-adjacent authority finding. It recognised that Kayihura could instruct lawyers under the August 2021 Board resolution while he remained CEO. It then held that no CEO existed to mandate the lawyers for the identified March and September 2023 proceedings after his office had ended. In that specific chain, Eshun lacked authority to cause the appeal, and Moollan and Mardemootoo lacked locus to lodge and appear in it.
The holding is powerful precisely because it is dated and bounded. It connects an identified proceeding to an expired source of authority. It does not hold that the October 2021 engagement letter was void. It does not decide that every service after 2021 lacked authority. It does not adjudicate every invoice or payment in AFRINIC’s 2022–2025 disclosures. It does not transform USD 3,289,408 into a judicially condemned sum.
Overgeneralising the judgment would reproduce the very failure NRS’s transaction method is designed to avoid. If one specific authority chain failed, the correct response is to test the rest of the chains with equal precision. Some may trace to the valid pre-June-2022 Board and CEO delegation. Some may fail for the same temporal reason identified by the court. Others may depend on later court orders or written Receiver instructions. Still others may remain unproved because the necessary document has not been published. One verdict for the aggregate would erase those differences.
The Receiver’s role must be treated in the same bounded way. The Supreme Court appointed the Official Receiver on 12 September 2023 with a court-described preservation and Board-election mandate. Gowtamsingh Dabee later replaced the prior Receiver on 12 February 2025. AFRINIC’s October 2025 and March 2026 communications said the Receiver remained in place pending formal discharge. None of those facts supports an assumption that receivership authorised every historical invoice or every new item of legal work.
If AFRINIC relies on a Receiver power or direction for a transaction, it should produce the operative order or written instruction and show that the act fell within its date and scope.
The status of the people AFRINIC presents as its current Board is also contested. AFRINIC describes a reconstituted Board. NRS disputes the authority of those people, and AFRINIC’s court-case index continued to show related proceedings. No final judicial determination in the sealed record resolves that present dispute. The appropriate formulation is not “valid” or “invalid” as a settled fact. It is a demand for the appointment, quorum and authority chain on which each current act depends.
Accounts are one layer of proof, not the whole chain
AFRINIC’s notice for the 25 June 2026 annual general members’ meeting proposed Ordinary Resolutions III through VI to approve the audited financial statements for 2022, 2023, 2024 and 2025. That notice proves what members were asked to consider. It does not prove how they voted. By the evidence cutoff, no certified final poll totals, signed final minutes or transaction-level legal-spend reconciliation had been located.
It is therefore improper to invent an AGMM result, objections or a meeting outcome. It is also improper to treat the proposed vote as a time machine. The Mauritius Companies Act places consideration and approval of financial statements, receipt of the auditor’s report and consideration of the annual report within annual-meeting business. AFRINIC’s bylaws give an eligible membership defined meeting and voting mechanisms. Those are meaningful corporate functions.
No located text says that approval of historical accounts supplies the original retainer, cures an unauthorised pleading, reconstructs a missing invoice approval, creates a bank mandate or validates a Board whose authority is independently contested.
Members might reasonably conclude that statements present the financial history fairly while still reserving judgment about whether particular acts were authorised or prudent. Conversely, questions about authority can justify demanding more information before a vote. The distinction prevents two forms of exaggeration: the claim that accounts approval proves every underlying act, and the claim that any doubt about an act makes the entire financial statement meaningless.
Audit has a similarly precise role. An auditor reports within an audit mandate on records, scope, information, financial presentation and statutory or accounting compliance. That work can add significant assurance. It is not automatically a forensic examination of every mandate, conflict, procurement choice, fee, professional duty or payment signatory. The public record does not disclose the materiality thresholds, samples, provider confirmations, control tests or separate legality procedures necessary to say exactly how the legal-cost lines were tested.
An expense entry and an audit opinion are evidence. Neither is corporate authorship. Booking a cost can show that finance recognised it in a period. It does not reveal, by itself, whether it was accrued or settled, which bank signatories acted, or whether the person who commissioned the service held the right office that day. Treating recognition as authority would allow the downstream accounting act to manufacture the upstream mandate it was supposed to record.
The budget signal
The 2022 operations budget identified USD 140,000 as the legal component of legal and consultancy fees. AFRINIC later disclosed USD 1,250,527 of legal fees for that year, approximately 8.93 times the budgeted legal amount. The comparison is a strong control signal and a weak verdict. It calls for the original ceiling, the timing of the variance, the person or body that approved it, the reasons, the procurement or quotation record where applicable, and the conflict treatment. It does not prove that spending above budget was inherently unlawful or wasteful.
Litigation can change quickly. Emergency proceedings may demand expenditure that could not be predicted with precision. A corporation may lawfully vary a budget through the appropriate authority. The problem here is not that variance is impossible; it is that the complete public variance chain was not located. An explanation without a dated approval is narrative. An approval without a tie to the provider and matter is an incomplete control record.
What is closed, what remains open
The public evidence closes several important questions. It closes the four annual figures and their sum. It closes each published provider table arithmetically. It closes the existence of the August 2021 Board retention and delegation, the October 2021 engagement, and the two identified invoice-approval episodes. It closes the narrow authority and locus outcome in 2024 SCJ 473 for the identified 2023 proceedings. It closes the fact that AFRINIC noticed resolutions to approve four sets of statements.
The same evidence leaves the central joins open. There is no complete public engagement register for 2022–2025. There is no matter-by-matter instruction ledger naming the corporate principal and authority instrument on each date. There is no privilege-safe invoice register containing the identifiers, amounts, time periods, rates, tax, disbursements, credits and deliverables needed to reconcile the annual totals. There is no complete map of Board, CEO, court or Receiver authority to every material act. Bank mandates, signatories, settlement dates and confirmations are missing from the public file.
The general ledger’s cash-versus-accrual classifications and provider or matter codes are not published. The audit procedures are not detailed enough to establish transaction authority. The final AGMM result and minutes were not located.
No independent finding in the sealed evidence establishes corruption, fraud, criminal enrichment, duplicate billing or professional misconduct. Those possibilities should neither be invented nor rhetorically implied. If a later independent review finds misconduct, the competent body can act on evidence. Until then, the rigorous conclusion is narrower and more useful: a material authority record has not been publicly reconciled transaction by transaction.
That conclusion also preserves the hierarchy of sources. NRS, Heng Lu, LARUS and BTW are first-class sources for the stakeholder record, doctrine and evidence they publish. NRS’s act here is the reproducible calculation and accountability demand. The LARUS-hosted scan proves one signed engagement and its dates, not all downstream transactions. BTW’s reporting provides first-class context and collision boundaries, but allegations in a broad scandal narrative do not become judgments through repetition. AFRINIC’s accounts, minutes, budgets, notices, communiqués and court index establish what the institution recorded, resolved, asserted or did.
Their official status does not, by itself, make AFRINIC’s interpretation the editorial truth about lawful authority, value for money or legitimacy.
The impact mechanism is therefore straightforward. Annual aggregation hides joins. A transaction ledger exposes them. It can separate valid work from unauthorised work, paid items from accruals, supported bills from unproved bills, appropriate variance from unexplained variance and limited judicial findings from speculation. That precision protects members’ funds and the professional fairness owed to lawyers and officials alike. It also protects AFRINIC’s legitimate continuity function from the institutional damage caused when an unexplained total is forced to carry more meaning than the accounts can bear.
NRS does not become a court by asking for that ledger. It advocates, researches, convenes and coordinates for members who expressly authorise it. It does not operate AFRINIC’s registry, RPKI, WHOIS or RDAP; it does not run the appeals system, settle litigation, conduct elections, control custody or guarantee service continuity. Its calculation can be checked. Its proposed legal effects remain advocacy unless adopted or decided by the actor with the relevant authority.
The responsible public finding is demanding but proportionate. AFRINIC should publish a privilege-safe reconciliation connecting each material legal cost to its matter, authority and financial treatment. The people it presents as directors, the Receiver, legal providers, auditors, company secretary and institutional supporters should show their own dated parts of that file. What can be proved should be credited. What a court has found defective should be identified precisely. What remains unknown should remain unknown.
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance