
Summary
- Furukawa Electric reported first-quarter revenue of JPY365.221bn, 24.3% above the prior year, and operating profit of JPY25.457bn, up 205.4%.
- The company said data-centre-related product sales helped produce its highest first-quarter revenue and profit levels since FY2001.
- Optical Solutions moved from a JPY0.728bn operating loss to JPY9.159bn profit; Information Components profit rose from JPY3.604bn to JPY7.396bn.
- Furukawa raised its full-year operating-profit forecast from JPY95bn to JPY123bn and cited data-centre product demand in both segments.
- The JPY150bn full-year capital-expenditure forecast was explicitly left unchanged from 12 May, despite first-quarter capex rising to JPY20.5bn.
- Product shipment, added capacity, utilisation, backlog, customer, pricing and data-centre revenue denominators remain undisclosed.
Demand has moved from campuses into the component bill
The economic importance of Furukawa’s quarter is not simply that another company mentioned artificial intelligence. Optical Solutions revenue reached JPY60.021bn from JPY41.211bn a year earlier, while the segment swung from a JPY0.728bn operating loss to a JPY9.159bn profit. Information Components revenue rose to JPY59.615bn from JPY44.880bn, and operating profit more than doubled to JPY7.396bn.
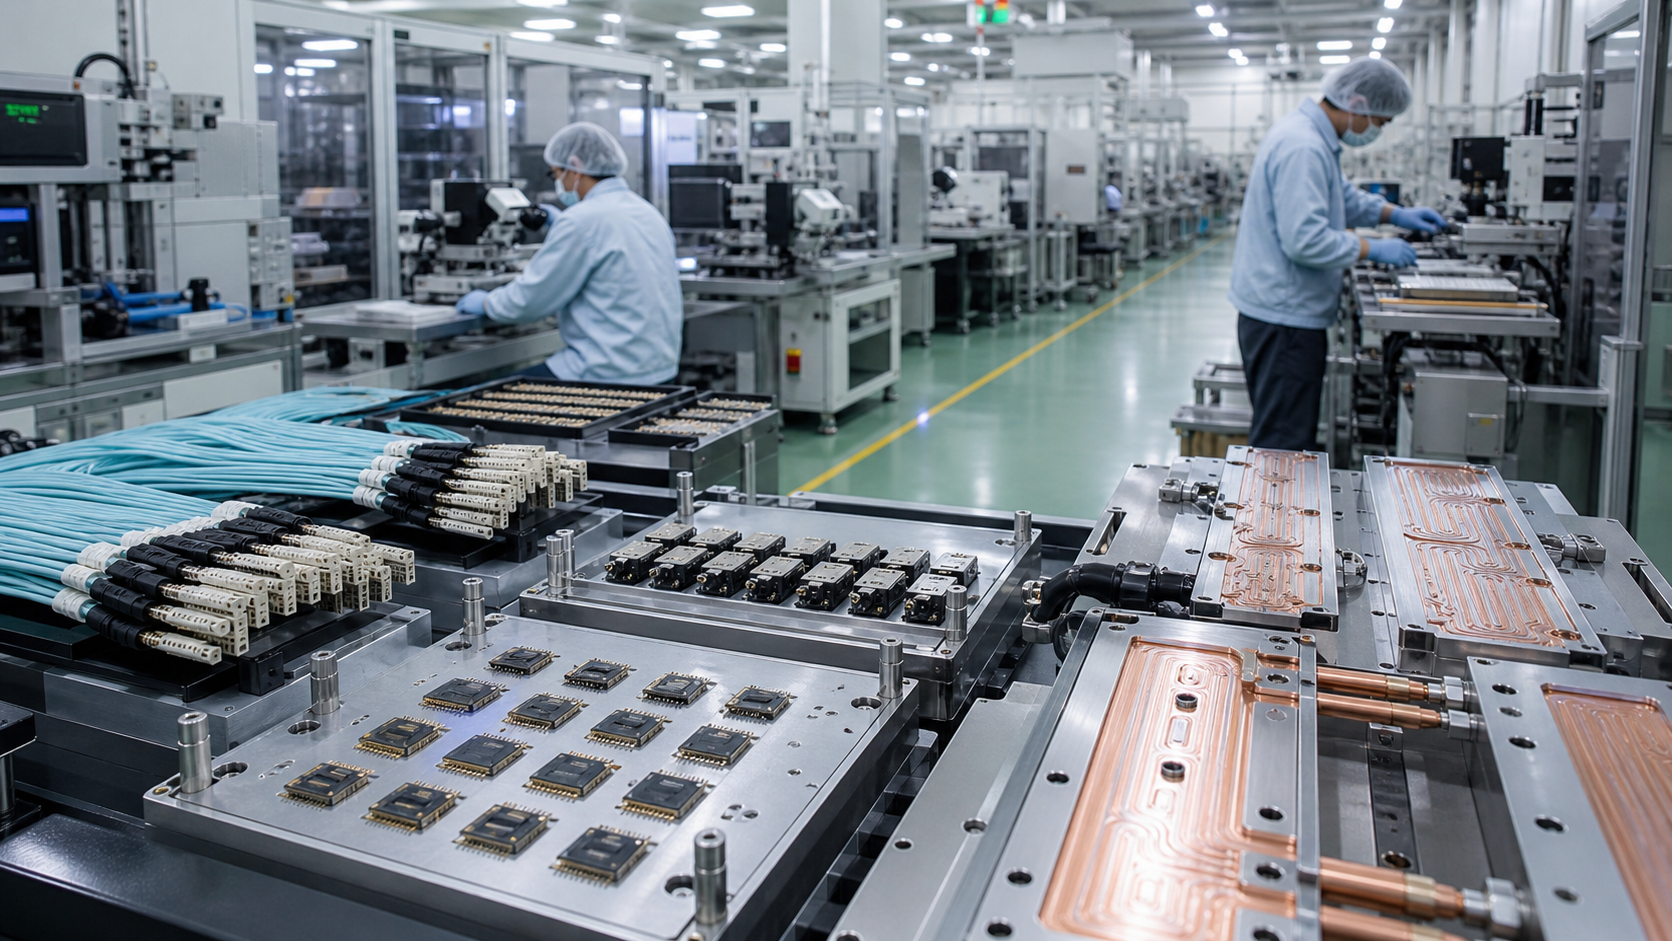
Furukawa identifies the physical products behind those segment labels: rollable-ribbon cable systems, MT ferrules, very-small-form-factor connectors and specialist fibre on one side; cooling modules, high-frequency copper foil and optical-semiconductor products on the other. These are enabling layers that determine how densely computing equipment can connect, move heat and scale. Demand reaching this layer is stronger evidence than a general statement about future AI spending, because components must enter a procurement and production cycle.
The forecast upgrade is meaningful, but not a product-level order book
For the year ending March 2027, Furukawa raised expected revenue from JPY1.46tn to JPY1.53tn and operating profit from JPY95bn to JPY123bn. Optical Solutions’ operating-profit forecast rose by JPY16bn to JPY43bn; Information Components rose by JPY12bn to JPY51bn. The company expects data-centre-related product sales to remain higher in the second half.
That change shows management sees the first-quarter demand as more than a one-month shipment bulge. It does not reveal how much revenue came from any individual product, customer or data-centre programme. There is no disclosed backlog, committed volume, price, delivery calendar or customer concentration. A forecast is management’s current expectation, not an executed capacity contract.
JPY150bn is a standing plan, not a new 6 August acceleration
The sharpest boundary in the disclosure concerns capital spending. Furukawa’s presentation labels the JPY150bn full-year capex forecast as unchanged and points back to its 12 May publication. First-quarter spending was JPY20.5bn, up from JPY8.9bn, while the full-year plan is JPY93.3bn above the previous year’s actual JPY56.7bn. Execution has accelerated relative to last year; the authorised annual forecast did not change with these results.
The allocation also resists a single “AI capex” label. About JPY45bn is identified for heat-dissipation and cooling products and about JPY7bn for DFB-laser-related investment, both close to the data-centre thesis. Roughly JPY16bn is for HVDC-related work in Energy Infrastructure. Other spending spans additional segments. Treating the entire JPY150bn as new data-centre investment would overstate both the event and its exposure.
Spending, installed capacity and paid output are separate states
Capital expenditure buys equipment, buildings and production tools. It does not establish when a line is installed, qualified, available, filled with orders or producing accepted units. Furukawa disclosed JPY20.5bn of first-quarter capex but no increment in ferrule output, fibre capacity, cooling-module units or laser production.
That missing conversion matters because component expansion can be lumpy. Precision tooling may require qualification before yield stabilises; customers may certify parts slowly; one bottleneck can leave adjacent equipment underused. The next useful disclosure is not merely another spending total. It is capacity commissioned, production yield, shipment volume and customer acceptance against the capital deployed.
Profit improved faster than revenue, but the bridge is not purely volume
Group revenue rose 24.3%, while operating profit increased 205.4% to JPY25.457bn. Operating leverage in the two data-centre-facing segments is plainly visible, especially the Optical Solutions swing into profit. Higher volumes and a richer product mix can spread fixed manufacturing costs and lift margins rapidly after a constrained line passes break-even.
But external prices and currencies also moved. The quarter’s average copper benchmark was JPY2,220 per kilogram, against JPY1,424 a year earlier, and the average dollar exchange rate was JPY160 rather than JPY145. Metal Solutions revenue jumped 55% while its operating profit fell 2.1%, a reminder that nominal sales do not equal physical volume or pricing power. Prior-year segment figures were also recast after an organisational change. The data-centre signal is credible; the headline revenue rate is not a clean demand denominator.
Working capital and debt show who funds the expansion
Furukawa’s balance sheet grew with the sales cycle. Receivables and contract assets increased by JPY24.4bn from year-end, inventories by JPY13.7bn and tangible fixed assets by JPY12.1bn. Net interest-bearing debt rose JPY44.6bn to JPY292.1bn, while the net debt-to-equity ratio moved from 0.59 to 0.67.
Those movements do not invalidate the investment case. They locate its risk. Furukawa pays for inventory, tools and customer credit before all cash is collected. If data-centre demand remains tight and new output is sold at attractive margins, that funding can generate a strong return. If orders normalise before capacity is qualified, higher debt and working capital will absorb part of the operating gain.
The missing denominators decide whether the surge is durable
Furukawa has disclosed enough to establish a real component-demand event, but not enough to price its duration. Investors still lack product-level data-centre revenue, shipment quantities, added nameplate capacity, utilisation, backlog, customer concentration, pricing and contract length. Ordinary profit and attributable profit also benefited from higher equity-method investment income, so they should not be attributed entirely to component demand.
The best test will combine operating and financial measures: whether the raised segment profit forecasts survive into the second half, whether the JPY150bn plan converts into commissioned lines, and whether inventories and debt stabilise as sales are collected. That is the point at which an AI-infrastructure demand signal becomes evidence of a durable manufacturing return.
Sources
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance