
Summary
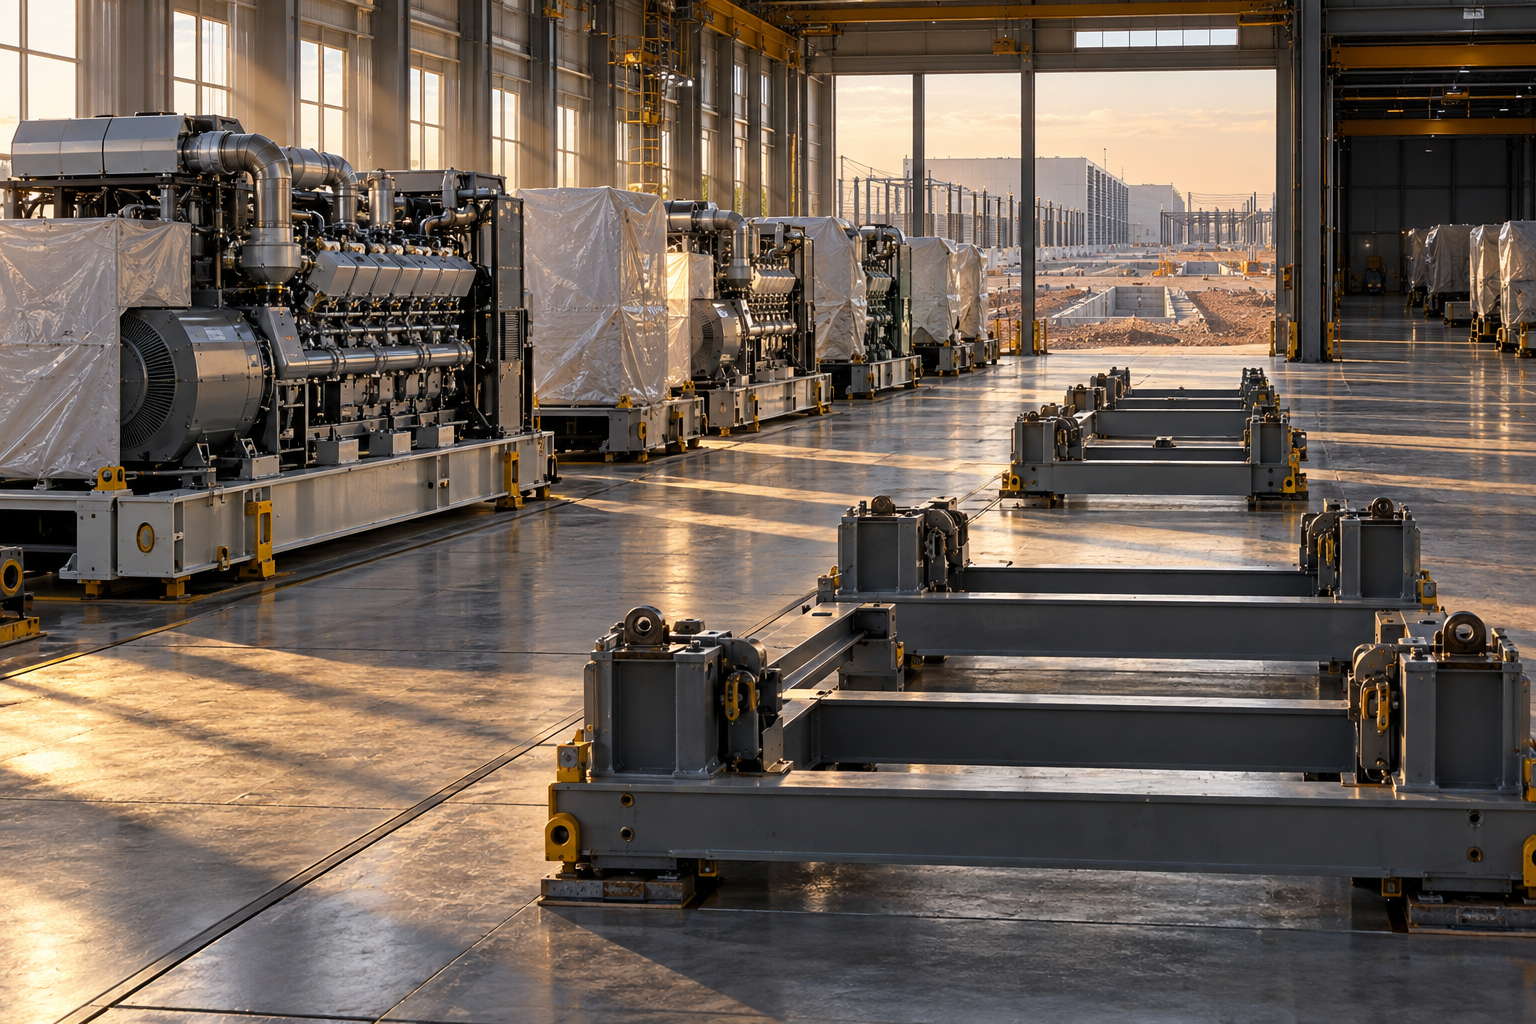
- Energy Vault says it has secured and fully contracted 275MW of Rolls-Royce mtu reciprocating-engine capacity for delivery from the second half of 2027 through the first half of 2028. A roughly $137.5 million delayed-draw facility funds equipment, installation and commissioning payments.
- The financing is not passive capital. Draws follow manufacturing instalments, require equity support and reserves, carry floating interest plus a one-per-cent fee on undrawn commitments, and are protected by collateral, lender controls and remarketing rights.
- The facility matures on 2 January 2028, two days after its availability period ends and while the announced delivery window may still be running. A named site, customer, power contract, fuel plan, permits and take-out financing would convert procurement into a deployable asset.
The most revealing date in Energy Vault's new AI-power announcement is not the delivery start. It is the debt maturity. The company expects its 275MW of contracted reciprocating-engine capacity to arrive between the second half of 2027 and the first half of 2028. The loan arranged to fund the equipment stops being available on 31 December 2027 and matures on 2 January 2028.
That is a narrow bridge between buying scarce equipment and placing it into long-duration infrastructure. The bridge is deliberate: private credit pays suppliers against a manufacturing schedule while Energy Vault preserves more corporate cash for other uses. But it also creates a clear test. By the time the final instalments are drawn, the company needs a credible path from movable generators in a special-purpose vehicle to a permitted site and a paying load.
The 10 September announcement establishes two real achievements. Rolls-Royce mtu manufacturing capacity is described as fully contracted, not merely reserved under a memorandum. Eagle Point Credit Management has provided dedicated equipment financing. Those facts reduce supplier-availability risk and the amount of parent cash needed before deployment.
The announcement is equally precise about what has not yet been secured. The engines are intended to support a portfolio of multi-gigawatt discussions with AI and high-performance-computing customers. Discussions are not identified as signed power-purchase agreements or infrastructure-service contracts. No site, customer, fuel source, permit or notice to proceed is named. The 275MW is therefore financed supply for an opportunity set, not disclosed operating capacity or contracted customer load.
The draw schedule is a manufacturing map
The filed credit agreement turns the round number into a sequence. It allowed as much as $38.36 million to be drawn in August 2026 and $10.58 million in November. From January through September 2027, as much as $6.73 million may be drawn each month, followed by $11.54 million in both October and November and $4.81 million in December. Each advance remains subject to conditions.
This is not a lump sum sitting idle in the borrower. Loans are funded when instalments become due under the equipment supply agreement. The structure makes the lender follow manufacturing progress and limits interest on money that has not yet been advanced. It also means the financing receipt must be read one draw at a time. A committed facility proves the capital is available subject to conditions; it does not prove that every production milestone has been met or every dollar has been funded.
Equity still has work to do. Before a delayed draw, the borrower must show cash for a redacted percentage of the equipment instalment and for all other then-due amounts under the supply agreement. It must stay within a redacted advance rate. The first draw also requires an appraisal and a debt-service reserve covering the next three months. Because the percentages are not public, it is not possible to calculate Energy Vault's total equity requirement from the $137.5 million commitment.
The schedule provides one useful operating signal. If draws appear broadly in line with the disclosed manufacturing calendar, that would indicate supplier milestones are being reached and funded. A postponed or reduced draw could have several explanations—equity funding, a delayed invoice, a missed milestone or a change in equipment need. It should not be interpreted without a filing or project update.
Dedicated debt is still expensive debt
The company describes the financing as capital-efficient because it limits corporate capital before deployment. That is a statement about where and when cash is used, not a statement that capital is cheap. The 8-K summary and agreement disclose a floating cost: Term SOFR plus 6.75 percentage points through the end of 2026 and plus 7.50 points thereafter. An alternative-base-rate loan carries its own 5.75- and 6.50-point margins. Undrawn delayed-draw commitments carry a one-per-cent annual fee after the first funding.
The contract also protects lender economics when the loan is repaid. Principal comes due with accrued interest, fees, costs and a repayment premium. For specified repayment events, the document defines an amount designed to deliver lenders a 1.165-times multiple on the relevant funded base. The actual premium cannot be calculated from public information because funding dates, amounts, fees and other cash payments matter.
These terms are the price of taking equipment risk before a project has been publicly matched to the assets. They do not make the strategy wrong. Long manufacturing lead times can be more costly than credit if a customer is willing to pay for earlier power. The comparison that matters is not the loan spread in isolation. It is the debt and carrying cost per usable megawatt against the schedule advantage and contracted cash flow obtained when the equipment is placed.
The special-purpose vehicle separates the wager
The borrower is EV Gen Set 1, LLC, held by EV Gen Set I HoldCo, LLC. Its permitted business is tightly bounded around acquiring the equipment and applying or dispatching it to the sale of power. The loan is secured by substantially all assets of the two entities, including supply-contract rights, accounts, related collateral and the membership interests in the borrower.
That structure creates a project-level box around the procurement. It does not make the equipment commercially self-sufficient. The vehicle cannot freely add debt, sell assets, change material contracts, make distributions or enter new material agreements without satisfying the credit documents. A later power contract is not simply an operating detail: the agreement treats a power-purchase agreement and contracts governing use or sale of power as material contracts, and lender consent matters.
Collateral also explains why the agreement includes remarketing provisions. If a planned site disappears or a customer timetable moves, modular engines may be more transferable than a half-built power plant. Yet remarketing is a recovery route, not the intended investment return. A sale must find a buyer, location, duty cycle and technical configuration that fit. Transport, storage, warranty, installation and market pricing can erode recoverable value. The presence of a collateral exit says the lender has thought about placement risk; it does not eliminate it.
Delivery and maturity almost touch
The timing is unusually compressed. The final scheduled draw falls in December 2027. The facility matures on 2 January 2028. Equipment deliveries are expected to continue into the first half of 2028. The disclosed schedule therefore allows a situation in which debt must be repaid or refinanced while some units are still in delivery, installation or commissioning.
There may be a planned take-out that is not public. A customer-backed project facility, sale of the equipment into a project company, long-term infrastructure debt, equity contribution or asset disposition could repay the procurement loan. The credit agreement's mandatory-prepayment provisions explicitly anticipate insurance proceeds, asset-sale proceeds, non-permitted borrowing, some equity issuance and proceeds from an advance-payment bond. None establishes which take-out will occur.
This is why the maturity date is more informative than the 275MW headline. It puts a deadline on commercial assignment. If named projects, contracts and permits arrive well before late 2027, the short procurement facility will have done its job. If the assets remain unassigned near maturity, refinancing will depend more heavily on equipment value and parent or sponsor options than on operating cash flow.
Megawatts cannot be added across announcements
Energy Vault separately disclosed an August agreement for 1.25GW of integrated power infrastructure in Texas. That contract refers to Caterpillar gas engines, battery systems and expected revenue through 2027. The new 275MW announcement refers to Rolls-Royce mtu equipment and a wider portfolio of discussions.
The company may eventually allocate some or all of the new engines to a named programme. It has not publicly done so. Adding 275MW to 1.25GW would count procurement and customer infrastructure as if they were comparable and independent. Subtracting it from the Texas contract would assume a connection that has not been disclosed. The disciplined position is to keep three ledgers: customer-contracted capacity, supplier-contracted equipment and operating megawatts.
The same separation applies to backlog. Energy Vault reported about $2 billion of backlog as of 10 August, but its 10-Q distinguishes binding contracted backlog from contingent options and uncontracted developed pipeline. The company warns that bookings, backlog and pipeline may not become revenue as expected. The September release calls the relevant demand “discussions.” The 275MW should not be placed in backlog by an outside reader.
A site supplies the missing denominator
Reciprocating engines are modular, but a power plant is not a pallet of interchangeable boxes. A project needs a fuel-delivery contract, electrical design, transformers and switchgear, batteries and controls, construction work, emissions treatment, noise management, operating staff, maintenance reserves and a load profile. The customer's useful denominator is firm power accepted at the data-centre bus, not nameplate engine capacity at the factory.
Site identity also determines regulation. The US Environmental Protection Agency's data-centre guidance notes that stationary engines used for primary or backup power can be subject to performance and hazardous-pollutant standards, while most air permits are issued by state and local authorities. An engine that runs continuously to bridge a grid delay has a different operating and emissions question from emergency backup. Without a location and duty cycle, no specific permit timetable can be credited.
Rolls-Royce's own product classifications distinguish standby, prime and continuous data-centre power. Energy Vault has not disclosed the exact model, unit count or fuel. The supply contract redacts those details. It is therefore reasonable to say the equipment can support phased deployment, as the announcement does, but not to infer how many units, which emissions package or what usable capacity a future site will receive.
The balance sheet makes placement material
At 30 June, Energy Vault reported $93.0 million of cash and cash equivalents, plus $55.0 million of restricted cash. Current debt was $78.0 million and long-term debt $165.0 million. Q2 revenue was $17.4 million and the GAAP net loss was $29.7 million. Those consolidated figures precede this facility and do not measure the new special-purpose vehicle, but they show why project-level capital is central to the model.
The company had already been increasing its use of debt: six-month interest expense rose to $7.7 million from $2.6 million a year earlier. The engine facility's delayed draws reduce immediate cash consumption, while its margin, reserve and equity conditions add future funding obligations. Placement quality will determine whether those obligations are supported by customer cash flow or become another refinancing task.
Energy Vault has bought time in a constrained equipment market. It has not bought an exemption from the project sequence. The next value-creating announcement would be smaller in headline megawatts but larger in evidence: a named load, a site, an enforceable long-term contract, permits, a fuel plan and financing that extends through construction and operation.
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance