
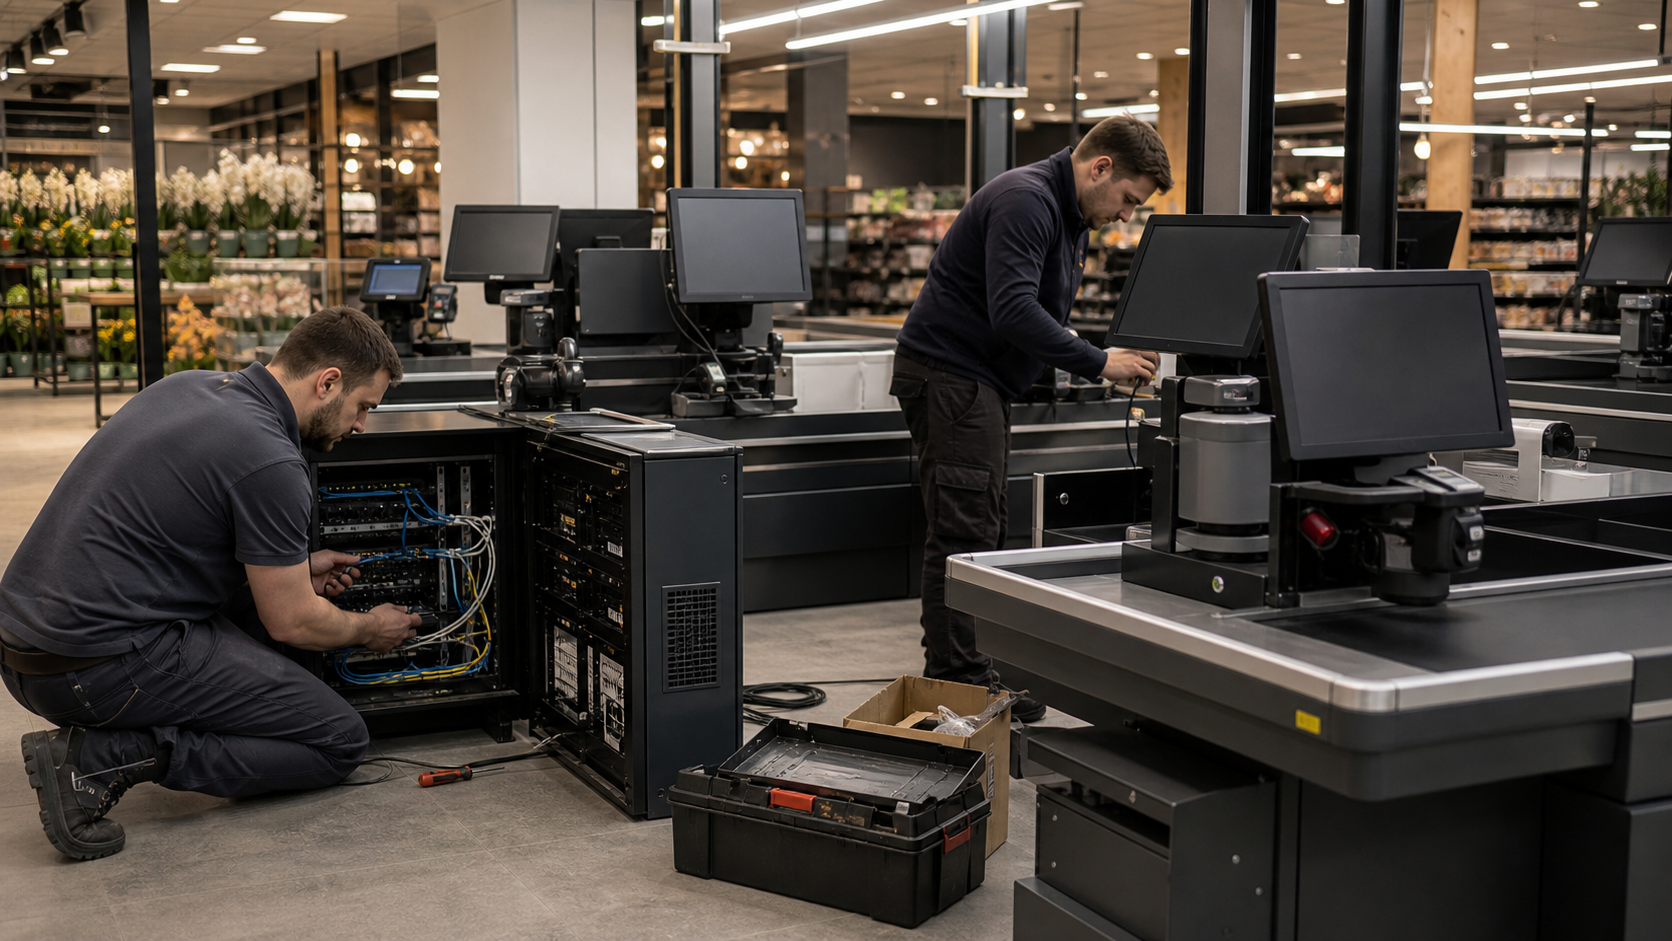
Summary
- The incentive starts at a single store: a retailer pays to remove queues, failed price updates, fiscal mistakes and store-level servers, while Crystal Service Integration must keep enough retained software and service value after the hardware bill, deployment labour and long support tail. The public case record shows that the company can win that bargain in large chains, because its Set Retail, Set SCO, Set Prisma, Set Loyalty and Pirit hardware sit directly in the revenue path of the store.
- The Elias Ward judgment is cautiously positive on operating relevance and cautiously conservative on economic quality. Public financial data point to roughly 4 billion rubles of recent annual revenue and a mid-single-digit to low-six-percent net margin, which is respectable for a hardware-and-services mix but not proof of pure software economics. The evidence supports a durable service franchise if renewal, support and module attachment remain high; it does not support a claim that Crystal Service Integration is a high-margin software company.
- The company appears stronger where the buyer is a chain retailer with hundreds or thousands of cash registers, complex loyalty rules, marked goods, online orders and self-checkout ambitions. That buyer has a costly in-house alternative and faces constant Russian fiscal and product-marking change. Those forces raise switching cost. They also make large customers powerful, concentrated and demanding.
- The main downside is not the absence of demand. It is margin conversion. Public materials show custom pricing, global-brand equipment integration, imported components, many third-party systems, service obligations across regions and major customer names. Those are exactly the ingredients that can turn a large rollout into low retained profit unless software licensing, support contracts and proprietary hardware carry the economics after go-live.
- Facts that would change the judgment are straightforward: segment gross margin by software, hardware and service; renewal rate; top-five customer share; support cost per register; inventory and imported-component exposure; customer churn after major rollouts; and whether Set Loyalty and Set Prisma attach to non-Set Retail estates at scale. Without those facts, the investable conclusion is that Crystal Service Integration is a serious retail automation operator with real installed-base leverage, not a fully proven compounder.
The incentive starts with a queue at one store. A retailer does not replace a checkout system because it wants software for its own sake. It replaces the system because every minute at the till can become lost throughput, every wrong price can become a customer argument, every failed fiscal update can create legal exposure, and every local server or fragmented cash-register estate can become a hidden labour tax. The economic buyer wants fewer manual steps, fewer night calls to store IT, faster promotions, cleaner loyalty execution and lower ownership cost.
Crystal Service Integration, or CSI in its public materials, must turn that buyer pain into margin. The test is severe: if the store rollout is mainly a bundle of fiscal printers, scanners, POS units, cables, imported parts and one-off installation hours, the contractor may book revenue but surrender much of the value to suppliers and labour. If, however, the rollout creates an installed base that uses CSI software, CSI firmware, CSI support, CSI monitoring, CSI updates and CSI-specific modules for years, the same first store becomes the entry point to a recurring service franchise.
That is the economic frame for LLC Crystal Service Integration. The company presents itself as a Russian developer and supplier of retail automation software, equipment and support for chain retail. Its own site says the current business covers development of cash-register software, the Cabinet KKT service, other trade-automation programs, software-hardware complexes, implementation, testing, support, technical service and equipment supply.
The public-facing product set is broad: Set Retail for front-office checkout and related store routines; Set SCO for self-checkout; Set Prisma for cash-operation control; Set Loyalty for customer-data and promotion management; Set Mark and associated capabilities for legally marked goods; and Pirit fiscal hardware and firmware. The public record therefore does not describe a narrow box mover. It describes a company trying to own a meaningful part of the checkout control layer.
The question is whether that control layer earns durable contribution. A store deployment can contain at least four revenue layers. The first is pass-through equipment: cash registers, displays, scanners, drawers, fiscal recorders, terminals, self-checkout stations and spare parts. The second is software licensing and usage rights: Set Retail, Set SCO, Set Prisma, Set Loyalty, Cabinet KKT, firmware and integration modules. The third is implementation: data exchange, ERP and loyalty integration, cashier training, pilot stores, rollout teams and migration support.
The fourth is ongoing service: 24/7 help desk, monitoring, legal updates, firmware releases, incident resolution, replacement stock and regional maintenance partners. The public material gives the richest evidence for layers two through four, but the financial statements do not isolate them. That missing segmentation is the central analytical constraint.
CSI has a useful starting advantage: the checkout estate is a high-friction place to compete. A cash-register system is not a website that can be swapped after a short trial. It touches fiscal-document formats, product catalogues, scales, price labels, loyalty balances, ERP feeds, online orders, acquisition terminals, marked goods, staff permissions, video review and the store's end-of-day reconciliation. Public product pages stress centralised control, open integration, monthly releases, use of Linux and PostgreSQL components, no need for store servers in some architectures, and updates for legislative change.
The claim that a retailer can update about 7,000 cash registers in one to two days through central control is especially important. If true in a customer's estate, the value is not only software speed; it is avoided field labour across thousands of stores.
The financial evidence is consistent with a real operating business, not merely a marketing shell. Public company-profile sites and registry aggregators identify the Russian legal entity, its Saint Petersburg address, OGRN 1157847313690 and INN 7813230814. They also identify Denis Sergeevich Ovchinin as general director and point to ownership by Retail Service Invest and Sergey Ledenev in different public profiles. Recent financial summaries place revenue around 4 billion rubles and net profit in the hundreds of millions of rubles. One source reports 2024 revenue of 4.026887 billion rubles and net profit of 208.772 million rubles.
Another reports rounded 2025 revenue near 4.0 billion rubles, net profit near 249 million rubles, 203 employees, fixed assets of about 281.8 million rubles and intangible assets of about 23.8 million rubles. Using those public numbers cautiously, the 2024 net margin is about 5.2 percent and the rounded 2025 margin is about 6.2 percent.
Those margins matter because they resist the easiest optimistic story. A pure enterprise software company with strong renewal economics might show much higher margins once mature. CSI's public numbers look more like a hybrid of software, hardware, implementation and service. That is not a weakness by itself. Retailers often buy the system that reduces operational risk, not the purest software license. But a hybrid business has to manage inventory, components, field work, warranty obligations, third-party integrations and customer-specific requests. Revenue can look large because hardware is included.
Profit can lag if projects require expensive engineers, if a large customer negotiates hard, or if imported parts move against the company. The right judgment is therefore not "software multiple." It is "installed-base services with hardware drag."
The installed-base evidence is strong enough to take seriously. CSI's homepage says its solutions are used across 15,000 stores and 170,000 cash registers, while the service page says the company supports more than 100,000 cash registers, works seven days a week, uses more than 200 partners in Russia and the CIS, serves more than 500 clients and handles more than 12,000 support requests each month. A Set Retail product page says 150,000 Set Retail licenses have been installed. The LinkedIn profile uses a different denominator, saying 300 retail chains, 150,000 software licenses and roughly 400 staff.
Those figures are not independently audited in the public materials, and they mix customers, stores, registers and licenses. Still, the convergence around a very large register base supports the idea that CSI's support cost and software updates are spread over a meaningful fleet.
The same installed-base evidence also explains why scale must be interpreted carefully. A register base is not the same thing as a paid subscription base. Some units may use older licenses, some may be under maintenance, some may be customer-managed, and some may belong to estates where CSI earns only project or equipment revenue. That is why the useful question is not simply how many registers have ever run Set software. It is how many registers require CSI-paid support, updates, fiscal adaptation, replacement equipment or new modules in any given year.
A 170,000-register footprint can be a powerful annuity if each register carries maintenance and update fees. It can be a weaker historical trophy if a large portion is already depreciated hardware or low-fee legacy software. The public materials do not separate these states, so the article's judgment treats the installed base as evidence of relevance and operating leverage, not as proven recurring revenue.
The unit economics become clearer when the installed-base claims are compared with revenue. If rounded 2025 revenue is about 4.0 billion rubles and the company supports more than 100,000 registers, revenue per supported register is at most about 40,000 rubles per year if all revenue were allocated to that supported fleet. If the 170,000-register homepage number is used instead, revenue per register falls to about 23,500 rubles. Neither calculation is actual annual recurring revenue, because the numerator includes hardware, implementation, new rollouts and possibly non-register services, while the denominator is a marketing-base measure.
The calculation is still useful: it shows that CSI does not need extreme per-register pricing to produce a large business, and that a few thousand-register chain can be financially material.
A second unit-economic check is employee productivity. Public financial profiles imply or state about 19.7 million rubles of revenue per employee in 2025. That is high enough to show operating scale, but it does not by itself prove high margin. A hardware-intensive integrator can show high revenue per employee because equipment invoices pass through the income statement. A software support firm can show high revenue per employee because one development and support team serves many licenses. CSI probably contains both effects. The distinction matters for valuation and resilience.
If revenue per employee is driven by software reuse, each new module attached to an existing estate should lift profit faster than headcount. If it is driven by hardware volume, growth may require working capital, supplier credit and field coordination. Public net margin closer to six percent than twenty percent suggests the second effect is material.
The economics also look plausible from a customer's side. Fix Price is the clearest public example. CSI's case material says Set Retail controlled 13,300 cash registers from one server in the modernised architecture, improved checkout-line speed by 11 percent, made required modifications 30 percent faster and saved 290 kilometres of receipt tape per week. The case specifies that CSI equipment included POS systems and Pirit fiscal hardware, with Datalogic scanners also present. For the customer, savings come from checkout speed, paper, central administration and easier online-order handling.
For CSI, the same case is attractive only if the software, service and future modifications carry margin after equipment. The scale is large enough that even a modest annual support and update fee per register would matter.
Globus adds another test. The public English case says the Russian estate replaced a foreign front-office system within a year across 1,605 cash registers in 17 hypermarkets in eight Russian regions. It describes classic, touch and self-service registers, about 400 self-service checkouts and self-scanning terminals, integration with CRM, BI and e-store systems, Set ESB as a data layer, Set Mark for labelled goods and continuing support. The GlobalCIO project account gives the project size as 78,950 person-hours. That is the right kind of large, complex deployment for CSI's competitive moat, but it also exposes the labour burden.
A project of that size can create a sticky anchor customer. It can also consume enough specialised effort that margin depends heavily on pricing discipline and reuse of the same product core.
Decathlon shows a more focused self-checkout and fashion-retail angle. Public project material says the Russian Decathlon stores used Set Retail 10 to manage about 400 registers, Set SCO for self-checkout and Set ESB for data exchange. The associated project summary reports roughly 7,990 person-hours and says maintenance costs decreased and service speed improved. Again, the customer reason is not a generic software preference. The buyer wanted lower ownership cost, a no-store-server architecture and a path to self-checkout, mobile registers and self-shopping.
This is where CSI can win against an in-house build: the retailer may know its stores better, but the vendor has already absorbed fiscal, loyalty, hardware and self-checkout edge cases across many chains.
The mid-size examples are important because a business built only on the largest chains risks lumpy sales. Parfum-Leader's public CSI case says the retailer operates 340 stores across beauty and drugstore formats and cut annual cash-software ownership cost by more than 3 million rubles, or 38 percent, after moving to Set Retail. The Krasny Yar and Baton GlobalCIO project says 800 automated workplaces were moved, including 670 line cash registers in 230 stores and 130 self-checkout units, with a shortlist narrowed partly by loyalty integration.
Begemag's public project says 61 stores and 190 registers were modernised, with checkout service 9 percent faster and incidents at the till down 70 percent. Verny involved 800 stores and 2,800 registers. Those cases widen the evidence base beyond one flagship customer.
CSI's strongest economic claim is that retail automation is not a one-off event. Russian retail has repeated fiscal and product-marking changes. The Pirit Light F model was added to the Federal Tax Service register in 2025, and official tax-service material says the model can be used without sector restrictions. CSI's own 2026 certification announcement says Pirit 2F and Pirit Light F were certified for 1C:Enterprise use and that the driver supports new VAT rates, fiscal-document formats and configurable OFD settings.
CSI's Pirit 2F announcement from 2021 refers to FFD 1.2 support for marked goods and a timetable for transition after inclusion in the register. These details are commercially important because they turn legal change into maintenance demand. A retailer that lacks in-house fiscal expertise is more likely to keep paying a vendor that updates the checkout estate before a new rule disrupts trading.
The Russian software-registry angle reinforces that point. CSI's official IT-disclosure page lists Cabinet KKT, Pirit 2F firmware and Pirit P firmware as entries in the Russian software register, with Cabinet KKT entered in 2021 and firmware entries in 2023 and 2024. A compatibility catalogue page for Pirit 2F firmware repeats register number 20602. A reseller page for Cabinet KKT repeats register number 9057 and describes the product as centralised management for CSI fiscal equipment. Registry inclusion is not a profit guarantee, but it improves procurement eligibility where buyers prefer or require domestic software.
It also helps CSI defend against imported-system replacement and import-substitution budgets.
The hardware side is more ambiguous. Pirit Light F looks like a genuine product effort, not a simple relabel. CSI says the device was tested for two years in its Saint Petersburg laboratory and in real conditions with major customers in Russia, Belarus, Kazakhstan and Uzbekistan. It gives specifications such as printing speed up to 220 millimetres per second, a knife resource of 2 million cuts, common driver and firmware packages with Pirit 2F, API and SDK availability, Windows, Linux and 1C driver support, and a three-to-fourteen-day implementation range.
The case for CSI is that proprietary hardware can lift attachment, support and firmware revenue. The risk is that hardware drags working capital and exposes the company to components. Public trade data identify 1,344 customs records, 70 suppliers and product codes consistent with plastic, metal, printers, computing equipment, power supplies, lithium batteries, network gear, monitors and parts. That is a real supply chain, not a pure cloud software cost base.
Supplier dependence deserves a discount. CSI publicly says Set Retail integrates with hardware from worldwide manufacturers. Case materials mention Datalogic, Honeywell, NCR, Re-Vision, FEC equipment, Lenovo, VMware and other external systems. The Pirit Light F technical article names a GigaDevice microcontroller family. The Cleverence partnership article describes CSI data-collection terminal integration with Mobile SMARTS and Honeywell scanning hardware. None of that proves fragility. In fact, broad integration can be a selling point because retailers often inherit mixed estates.
But it means a portion of CSI's value proposition is integration competence and supply orchestration. If a geopolitical shock or component shortage raises the cost of scanners, printers, touchscreens or boards, CSI may not keep all the price increase, especially with large retailers.
The service operation is the other side of that same coin. Public service pages say CSI offers 24/7/365 technical support, four support levels, Set product accompaniment, monitoring, EGAIS support, Chestny ZNAK module support, hardware maintenance, FNS support, laser marking, component repair, modular repair and spare-part substitution. The support page says the first line handles more than 15,000 monthly contacts, while the broader service page says more than 12,000 completed requests per month. The difference may reflect different periods or definitions, but both point to a support desk at significant scale.
The economic question is whether that desk is priced as an annuity or treated as a cost of winning project revenue. The evidence is not public.
Customer concentration is visible even without exact percentages. TAdviser's 2023 retail digitalisation ranking lists CSI as the leading retail IT supplier by 2022 retail project revenue among the table entries shown, with 4.551 billion rubles from retail IT projects, 3.240 billion from own solutions, and five largest customers named as Lenta, Fix Price, VinLab, Globus and Dixy. That is useful but also cautionary. A company serving the top end of Russian retail can build a large installed base quickly. It can also have negotiations dominated by a few chains. The top five names are likely capable procurement organisations.
They can demand custom work, delayed payment, service-level commitments, rollout support and pricing concessions. A large buyer can also keep an in-house team that weakens vendor leverage.
The in-house alternative is real but expensive. A retailer can, in theory, maintain its own checkout system, write custom loyalty logic, connect scales, connect fiscal recorders, manage marked goods, write updates and support every region. The Globus case explicitly says its previous foreign system had been heavily customised around Globus requirements but was limited by hardware dependence and resource-consuming improvements. Fix Price wanted no store servers. Krasny Yar and Baton sought a fast, clear, lightweight system with loyalty integration and a support plan.
These cases show why the in-house or legacy-custom route loses appeal: it preserves control but pushes every legal change, hardware migration and support incident back onto the retailer. CSI sells risk transfer. The transfer is not total, because the retailer remains legally responsible for trading correctly, but CSI absorbs the implementation and update burden.
Competition is not thin. Public market material identifies Set Retail alongside Frontol, Profi-T, UKM and Artix among common Russian cash-register systems. TAdviser product pages describe Frontol as a front-office retail and food-service automation system with long-standing back-office exchange options. Retail.ru coverage of a Cash & Carry project says the buyer considered Frontol 6 and Set Retail before choosing Set Retail. 1C-based alternatives and systems such as Shtrikh-M, service-plus UKM and other specialised POS products remain credible depending on store size, installed equipment and integration needs.
This means CSI's moat is not product category scarcity. It is reference depth, deployment experience, product breadth, domestic-registry positioning and support coverage.
Pricing disclosure is thin. CSI's official IT-disclosure page says software-rights cost is calculated individually, and product pages invite retailers to request a calculation or presentation. That is normal for enterprise retail software, but it prevents public validation of per-register economics. Custom pricing can preserve margin when the vendor understands customer value. It can also hide discounting and project underpricing. A customer that can point to alternative POS systems, existing 1C estates, old hardware and in-house staff has negotiating leverage.
CSI's stronger position is where the sale bundles a centralised checkout core, self-checkout, price-label automation, Set Prisma control, Set Loyalty and support in a way that makes comparison against a single POS license incomplete.
Payment timing is the related blind spot. Large retailers often prefer milestone acceptance, extended payment terms, retention against defects and separate commercial treatment for change requests. The public case studies show large deployments with pilots, phased rollouts and heavy integration. That kind of work can produce attractive lifetime value, but it can also create a cash-flow trough before final acceptance. Hardware may need to be purchased or reserved before the customer fully pays. Engineers may be assigned to a project before the revenue is recognised in full.
If CSI's contracts are written with strong advance payments and paid change requests, project cash conversion could be healthy. If the opposite is true, the company could report revenue while carrying receivables, inventory and service obligations. No public source reviewed here resolves that point, so cash conversion remains one of the biggest unknowns behind the headline revenue.
Set Prisma and Set Loyalty are therefore strategically important. They are not merely adjacent modules; they can change the revenue mix. Set Prisma uses cash-register and video data to identify losses and violations, and the product page gives examples of annual prevented losses for networks with 350 stores, 130 stores and 90 stores. VinLab's GlobalCIO case says Set Robot DaCo, connected to Set Retail, reduced data-error financial losses at the cash register by 90 percent, cut labour by 90 percent for the relevant checks and reduced lost profit in one early period.
Set Loyalty, meanwhile, moved from Set Retail dependence toward a universal API for third-party cash-register software, according to CSI's 2025 announcement. If Set Loyalty can sell into non-Set Retail estates, CSI's addressable market improves and its dependence on full POS replacement falls.
Those adjacent modules also change the buyer's internal budget discussion. A plain POS replacement competes with the old POS system and with an in-house maintenance team. A loss-prevention module competes with shrink, investigation labour and undetected cashier errors. A loyalty module competes with discount leakage, weak customer identification and underused promotion data. A self-checkout module competes with queue length and store staffing constraints. CSI's best commercial posture is to make the checkout estate the measurement point for these budgets.
When a retailer can attribute paper savings, faster service, fewer incidents or lower data-error losses to the same software estate, CSI has more room to defend renewal pricing. When those benefits are hard to measure, the buyer can push the vendor back into a commodity support and hardware frame.
The buyer-side returns can be persuasive. Parfum-Leader reported more than 3 million rubles of annual cash-software cost reduction. Fix Price reported paper savings of 290 kilometres per week and checkout acceleration. Verny reported a fourfold increase in receipt printing speed and a large-store rollout in under a year. Begemag reported fewer till incidents and faster service. Globus reported reduced maintenance cost from the Set ecosystem's free components and included capabilities. These are not audited economic returns, and many are vendor-published or award-platform project narratives.
Still, the recurrence of the same buyer objectives across independent case pages is meaningful: lower cost of ownership, legal adaptability, central administration, mixed hardware support and faster checkout.
The strongest customer economics are probably not the one-line savings figures. They are the avoided complexity of a thousand small exceptions. Retail chains do not operate a clean laboratory estate. They have old scanners in some stores, new touchscreens in others, different scale models, regional tax details, cashier turnover, loyalty changes, damaged printers, slow networks, video systems, online-order pickups, changed VAT rates, labelled goods, alcohol controls and promotion rules that collide at the till.
A vendor that has seen those exceptions across many chains can reuse support knowledge even where the software still needs customisation. That reuse is economically important because it turns support experience into a barrier to entry. A new competitor can undercut a license fee. It is harder to undercut years of incident memory if the customer believes that memory prevents outages.
The capital picture is mixed but not alarming. Companium's public summary reports fixed assets of about 281.8 million rubles and intangible assets of about 23.8 million rubles against 2025 revenue near 4 billion rubles. That suggests the business does not require heavy owned physical infrastructure relative to sales. A 2021 GlobalCIO news item, however, says CSI moved selected internal and customer-service workloads onto Lenovo hyperconverged infrastructure after using cloud services and older IBM blade servers, expecting about 50 million rubles of savings over five years.
That points to modest infrastructure intensity: enough to matter for service reliability and cost control, but not enough to dominate the balance sheet. The larger capital risk may be inventory, components and receivables rather than data-centre hardware.
Warranty and replacement-stock economics are not disclosed but should not be ignored. CSI's Pirit Light F material highlights service centres and replacement stock across Russia and Belarus. That is a customer benefit because a failed fiscal printer can stop a lane, and a failed lane during peak hours can cost more than the printer. For CSI, however, replacement stock is capital tied up before a failure happens. Field repair and substitution are valuable if priced into service contracts. They become a margin leak if used to preserve relationships after underpriced hardware sales.
The same applies to firmware updates advertised as free in some materials. Free updates can be good economics when they protect a paid installed base and reduce custom support. They can be bad economics if they are a perpetual cost attached to a one-time device sale.
The network evidence supports operational substance. IPinfo and related network databases identify AS204891 as LLC Crystal Service Integration, with 185.235.92.0/22 and related prefixes, Russia as the country of registration, and upstreams including Obit and Avantel in some datasets. Scamalytics describes the company as operating about 1,021 IP addresses with low observed fraud risk, while IP2Location lists 1,024 IPv4 addresses and no IPv6 addresses. These are not customer-quality signals.
They do show that CSI has its own routed network footprint associated with its domain, which is consistent with support portals, customer services, internal systems and monitoring. The absence of IPv6 in public datasets is not a business flaw, but it shows the network footprint is functional and modest rather than hyperscale.
Unofficial signals mostly confirm, rather than transform, the picture. LinkedIn indicates a Saint Petersburg head office, a Moscow location, a 201-500 employee band and regular product-update posts. Retail.ru's supplier profile describes CSI as a company with about 30 years in retail automation, software development, equipment supply and support. D&B repeats the Saint Petersburg address, website and director name. NBD trade data show many import records and suppliers. None of these should be treated as audited proof of margin or market share. They do reduce the risk that the public company profile is empty.
The issue is quality of earnings, not existence.
Regulatory risk is double-edged. Russian fiscal law, labelled-goods rules, VAT changes, 1C compatibility, personal-data requirements and online-cash-register rules create demand for a specialist. Every new rule can require software updates, firmware validation, driver compatibility, training and customer communication. That is good for renewal and support attachment. But the same regulation raises cost. CSI's privacy policy identifies processing of customer and worker personal data for contractual obligations and marketing contact, which places it inside Russia's personal-data compliance environment.
If a product touches loyalty, customer identifiers, marked goods and fiscal records, the vendor has to manage security and compliance expectations. An outage or compliance miss in a large chain would be commercially serious even if liability caps exist in contracts.
Geopolitical risk sits mainly in hardware and cross-border expansion. The company publicly serves Russia and CIS markets, and case material includes Belarus, Kazakhstan, Uzbekistan, Tajikistan and other regional contexts. Set SCO is described as adapted for several countries with local text, currency and tax rules. This helps the growth story: Russian and CIS retailers may prefer domestic or regionally adapted systems as Western retail IT vendors retreat or become harder to support. But regional expansion requires constant localisation and hardware availability.
Import records and global-brand integrations show dependence on physical supply chains. The best version of CSI's strategy is to convert foreign-vendor replacement into local software, firmware and support revenue while reducing imported content over time. The weaker version is a distributor-service mix exposed to currency and logistics shocks.
The legal identity evidence carries one caution. Public profiles do not perfectly align on the main activity code. CSI's official IT-disclosure page lists 46.90, wholesale trade, as the main code. Some company profiles describe repair of computers and peripheral equipment by reporting data. This is not necessarily a contradiction in operations; Russian companies often carry several registered or reported activities. But it reinforces the hybrid nature of the business. A clean software vendor would be easier to model. CSI is a software developer, hardware maker, equipment supplier, service organisation and integrator at once.
That breadth is commercially useful but analytically messy.
The most attractive unit-economic feature is the possibility of module compounding. A retailer that starts with Set Retail can later attach Set SCO, Set Prisma, Set Mark, Set Loyalty, Cabinet KKT, support, monitoring, fiscal equipment and replacement parts. Product pages and cases repeatedly show this pattern: Globus included Set Retail, Set SCO, Set Mark, Set Kit and Set ESB; Fix Price included Set Retail, Set Kit, CSI POS equipment and Pirit; Decathlon included Set Retail, Set SCO and Set ESB; Parfum-Leader included Set Retail and Set Kit; VinLab used Set Retail and Set Robot DaCo.
If the same installed estate can absorb new modules without a full sales cycle, CSI's retained value improves. This is the heart of the positive case.
The main negative case is that module compounding may be offset by custom labour. Large retailers rarely accept a box-standard checkout configuration. They ask for loyalty nuances, ERP connections, partial bonus write-off, online-order payment, age confirmation, marked-goods exceptions, self-checkout flow changes, cashier permissions and country-specific rules. Public cases describe exactly those requirements. CSI says its product has a common code base and ready integrations, which should protect margins.
But without project gross margin, backlog, renewal disclosure or support cost per customer, outsiders cannot tell how much of each deployment is reusable product and how much is bespoke engineering sold at service-company margins.
There is also a timing risk. Retail technology replacement can be lumpy. A large chain may replace its cash-register system once, then settle into a lower annual support run-rate. CSI needs either enough new rollouts, enough adjacent modules or enough service pricing to offset that natural post-rollout decline. The company's public cases from 2019 through 2026 suggest a steady stream of deployments, updates and new products. Still, a public list of marquee projects is not the same as contracted recurring revenue.
If Russia's large chains pause capex, stretch payment terms or push rollouts into internal teams, CSI's revenue could remain large but margin could compress.
Self-checkout is a useful demand signal even when only company-published product figures are used. CSI's Set SCO page says the software supports marked goods, loyalty, CIS-country localisation and integration with Set Prisma, and it states that more than 17,000 self-checkout units have been installed. Self-checkout is economically attractive because it combines hardware, software, video, cashier-assistance tools, fraud control and support. It can also become operationally sensitive if shrink rises, if customers struggle with the interface, or if staff have to intervene too often.
CSI tries to answer this with video, recognition and control-weight options, plus integration with Set Prisma. The economic benefit is credible if each self-checkout island creates recurring software and support. The risk is that the hardware ticket inflates revenue while retailers pressure the service fee after installation.
There is a strategic reason to care about self-checkout beyond the hardware sale. A traditional register replacement can be framed as maintenance. Self-checkout changes store labour design, customer flow and loss prevention. That gives the vendor more ways to prove value, but it also raises the penalty for failure. If a self-checkout zone creates queues, mis-scans or shrink, the retailer's store team will blame the system quickly. CSI's edge is that Set SCO, Set Prisma, cashier-assistance tools and Pirit hardware can be positioned together.
The margin question is whether that integrated sale is priced as a differentiated operating system for the checkout zone or discounted as a hardware deployment in order to win logos.
The company's regional expansion story also carries two different readings. The positive reading is that Set Retail and Set SCO can be localised to nearby markets where Russian-style retail operations, fiscal rules, language adaptation and supplier familiarity matter. The GlobalCIO Uzbekistan case and Pirit Light F testing references in Belarus, Kazakhstan and Uzbekistan support that view. The cautious reading is that each country adds localisation, support and compliance obligations. Currency, import rules, fiscal certification and local partner quality can change the economics.
Regional work is attractive when it reuses the same product core with limited adaptation. It becomes less attractive if each country behaves like a separate bespoke product.
Management depth is hard to assess from public filings, but the organisation shows signs of institutional operating capability. The product pages identify named product leaders; the case studies describe project managers and customer-side IT leaders; service pages describe multi-level support; and third-party profiles show enough staff and public activity to support a sizeable organisation. This matters because retail automation is a delivery business as much as a product business. Weak delivery damages renewal. Strong delivery turns a complicated first rollout into a reference sale for the next chain.
The public record contains multiple reference deployments over several years, which is a positive signal. It does not prove that the company can keep the same delivery quality if growth shifts to more countries, more self-checkout hardware or more non-Set Retail loyalty customers.
What would a better disclosure package show? First, software and service revenue as a share of total revenue. Second, gross margin by segment. Third, annual recurring support, renewal and update fees. Fourth, customer concentration by revenue, not just named customer logos. Fifth, average implementation hours per register by rollout type. Sixth, inventory turnover and imported-component concentration. Seventh, attachment rates for Set Prisma, Set Loyalty and Set SCO among Set Retail customers. Eighth, churn or system replacement losses.
Those facts would decide whether CSI is a compounding installed-base software-services business or a capable integrator with episodic project economics.
Until then, the judgment should stay disciplined. Crystal Service Integration appears to have a real product family, real fiscal-hardware registrations, real large-chain references, real service infrastructure and real financial scale. It also appears to operate in a demanding market where the buyer's problem is urgent and recurring. That earns a positive operating view. But the public financial profile, custom pricing, hardware supply exposure and concentration evidence argue against treating all revenue as high-quality recurring software revenue.
The sensible Elias Ward judgment is that CSI's durable value depends on how much of each store deployment it can keep after the first sale: software licenses, firmware updates, support, monitoring, additional modules and replacement cycles. If those streams are attached and renewed, the company has a defendable niche. If they are not, the company is a busy retail-automation contractor with a harder margin ceiling.
The facts that would change the judgment are concrete. A disclosed support renewal rate above 90 percent, rising software-and-service share, stable top-customer concentration, documented gross margins above ordinary hardware resale levels, low receivable stress and strong Set Loyalty sales into third-party POS estates would raise confidence. Evidence of heavy discounting, stalled major customers, falling support attachment, rising warranty cost, imported-part disruption, shrinking employee productivity or delayed fiscal-update releases would lower it.
For now, the company's incentive is clear: turn each store deployment into a multi-year control relationship, not a one-time equipment invoice. The public evidence shows the company has the ingredients. It does not yet show the exact margin recipe.
Sources
- https://crystals.ru/
- https://crystals.ru/it-activities-info/
- https://crystals.ru/privacy/
- https://www.dnb.com/business-directory/company-profiles.llc_crystal_service_integration.15a2571d2ac4b22586fb36c74bfeaf8e.html
- https://firmoteka.ru/7813230814
- https://companium.ru/id/1157847313690-kristall-servis-integraciya
- https://companies.rbc.ru/id/1157847313690-ooo-kristall-servis-integratsiya/
- https://xn----etbbhpfd3axw8i.xn--p1ai/companies/7813230814
- https://www.retail.ru/rbc/company/csi/
- https://ru.linkedin.com/company/crystal-service
- https://crystals.ru/products/set-retail/
- https://crystals.ru/en/products/set-retail/
- https://crystals.ru/products/set-retail/kassy/
- https://crystals.ru/products/set-sco/
- https://www.tadviser.ru/index.php/%D0%9F%D1%80%D0%BE%D0%B4%D1%83%D0%BA%D1%82%3ACSI%3A_Set_SCO
- https://crystals.ru/products/set-prisma/
- https://crystals.ru/infocenter/news/sistema-avtomatizatsii-marketinga-set-loyalty-teper-dostupna-riteyleram-s-lyubym-kassovym-po/
- https://crystals.ru/infocenter/articles/kazhdyy-shag-schitaetsya-set-loyalty-i-put-k-loyalnosti-pokupatelya/
- https://crystals.ru/service/
- https://crystals.ru/service/products/soprovozhdenie-produktov-set/
- https://crystals.ru/service/products/otkrytie-novykh-magazinov-i-masshtabirovanie-torgovykh-setey/
- https://crystals.ru/infocenter/articles/fiskalnyy-registrator-pirit-layt-f-fakty-i-kharakteristiki/
- https://crystals.ru/infocenter/news/kassy-pirit-2f-i-pirit-layt-f-sertifitsirovany-dlya-raboty-s-1s-predpriyatie/
- https://www.nalog.gov.ru/rn77/related_activities/registries/reestrkkt/16541147/
- https://www.consultant.ru/document/cons_doc_LAW_513244/c343d17461d531e08672680009016d44e803d189/
- https://crystals.ru/infocenter/news/pirit-2f-voshyel-v-reestr-kkt-s-podderzhkoy-ffd-1-2-/
- https://www.nalog.gov.ru/rn79/news/tax_doc_news/6167390/
- https://catalog.arppsoft.ru/product/6308323
- https://k-integration.ru/product/kabinet-kkt/
- https://projects.crystals.ru/fixprice
- https://crystals.ru/en/projects/fix-price-modernization-13-300-cash-registers-controlled-by-1-server/
- https://globalcio.ru/projects/3072/
- https://crystals.ru/en/projects/globus-launches-new-tools-for-business/
- https://globalcio.ru/projects/11064/
- https://projects.crystals.ru/decathlon
- https://globalcio.ru/projects/10795/
- https://crystals.ru/projects/set-retail-v-torgovoy-seti-parfyum-lider-krasota-da-i-tolko/
- https://globalcio.ru/projects/35951/
- https://globalcio.ru/projects/19579/
- https://globalcio.ru/projects/3173/
- https://globalcio.ru/projects/3046/
- https://globalcio.ru/projects/10941/
- https://www.retail-loyalty.org/news/tadviser-kakie-kassovye-resheniya-ispolzuet-rossiyskiy-riteyl/
- https://www.tadviser.ru/index.php/%D0%A1%D1%82%D0%B0%D1%82%D1%8C%D1%8F%3A%D0%A6%D0%B8%D1%84%D1%80%D0%BE%D0%B2%D0%B8%D0%B7%D0%B0%D1%86%D0%B8%D1%8F_%D1%80%D0%B8%D1%82%D0%B5%D0%B9%D0%BB%D0%B0._%D0%9E%D0%B1%D0%B7%D0%BE%D1%80_TAdviser_2023?ysclid=lkjtk3bdzz902038
- https://www.tadviser.ru/index.php/%D0%9F%D1%80%D0%BE%D0%B4%D1%83%D0%BA%D1%82%3A%D0%9A%D1%80%D0%B8%D1%81%D1%82%D0%B0%D0%BB%D0%BB%D0%A1%D0%B5%D1%80%D0%B2%D0%B8%D1%81%3A%20Set%20Retail
- https://www.tadviser.ru/index.php/%D0%9F%D1%80%D0%BE%D0%B4%D1%83%D0%BA%D1%82%3AFrontol%20%D0%A2%D0%BE%D1%80%D0%B3%D0%BE%D0%B2%D0%BB%D1%8F
- https://www.cleverence.ru/news/csi-i-kleverens-stali-partnerami/
- https://globalcio.ru/news/14755/
- https://en.nbd.ltd/trader/info/42RU7813230814
- https://ipinfo.io/AS204891
- https://scamalytics.com/ip/isp/llc-crystal-service-integration
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance