
Summary
- Nebius Group N.V. reported second-quarter 2026 group revenue of $582.3 million, up 454% from $105.1 million a year earlier, with about $575 million of that from its AI cloud business and annualised run-rate revenue of $3.0 billion at the end of June.
- The company defines three forms of power — contracted, connected and active — and its guidance spans very different quantities: 5GW of contracted power by the end of 2026, against 800MW to 1GW of connected power. Management said the connected capacity should be active through the first half of 2027.
What was actually reported
Nebius Group N.V. (Nasdaq: NBIS), an Amsterdam-headquartered AI cloud company, published unaudited results for the three and six months ended 30 June 2026 on 12 August 2026. Group revenue was $582.3 million in the quarter against $105.1 million a year earlier, an increase of 454%; for the half year the figures were $981.3 million against $156.0 million, up 529% (Q2 2026 results release).
Within that, AI cloud revenue was about $575 million, up 514% year on year and roughly 98% of group revenue, with a 50% adjusted EBITDA margin in that business (Q2 2026 shareholder letter). Group adjusted EBITDA swung to $236.2 million from a loss of $21.0 million a year earlier, while the net loss from continuing operations was $190.4 million, against net income of $502.5 million in the comparable quarter of 2025 (Q2 2026 results release).
The headline growth figure the company leads with is annualised run-rate revenue, or ARR. Its definition matters: ARR is Nebius AI cloud revenue in the last month of the quarter multiplied by 12. On that basis ARR was $3.0 billion at the end of June 2026, up 598% year on year and 56% from the $1.9 billion reported at the end of March (Q2 2026 shareholder letter). The March figure of $1.92 billion was itself up 674% year on year and 54% from $1.25 billion at the end of December 2025 (Q1 2026 shareholder letter). ARR is therefore a one-month annualisation of cloud revenue, not audited recurring revenue and not a contracted backlog measure.
Three rungs, three different numbers
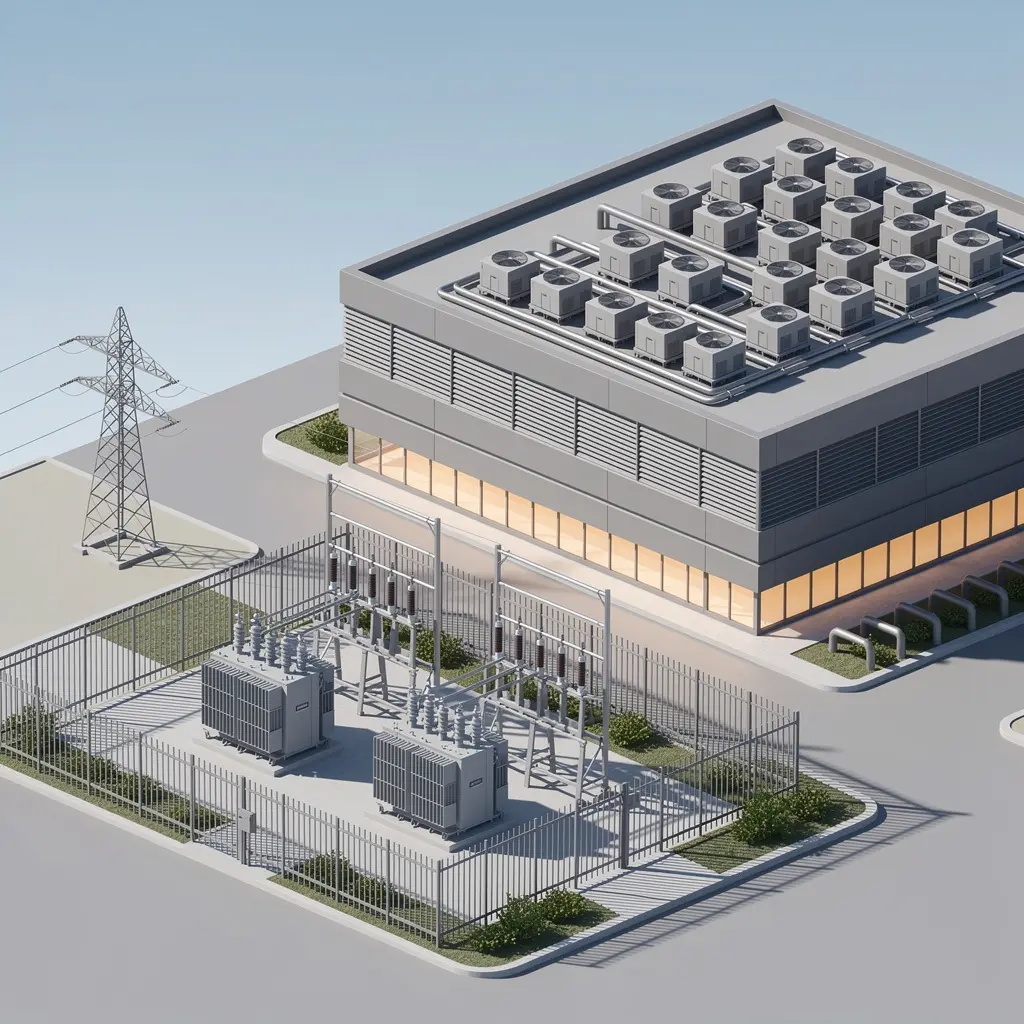
Nebius's shareholder letters define the ladder explicitly. Contracted power is power secured by contracted land and power commitments. Connected power is power connected into fully built and equipped data centres. Active power is power being consumed by installed, operational IT equipment and available for revenue generation (Q1 2026 shareholder letter, Q1 2026 letter filed with the SEC).
The three rungs are not close together. At the first-quarter disclosure, contracted capacity exceeded 3.5GW, with owned capacity representing more than 75% of the total, and contracted-power guidance was raised to more than 4GW by year-end while connected power was guided at 800MW to 1GW for the year (Q1 2026 shareholder letter). The same document states that Nebius's owned facilities will deliver 3GW of capacity across five sites, described as a capital-efficient model with attractive long-term unit economics (Q1 2026 letter filed with the SEC).
In the second quarter the company raised the contracted-power target again, to 5GW by the end of 2026, up from the more than 4GW indicated the previous quarter (Q2 2026 shareholder letter). Reuters reported the same increase and the company's expectation of deploying more than 1GW of capacity annually from 2027 (Reuters, 12 August 2026). Management said it still expects to meet the 2026 guidance of 800MW to 1GW of connected power (Q2 2026 earnings call transcript).
So the published targets span roughly a fivefold difference between what Nebius has contracted and what it expects to have connected within the year. The company does not publish an actual period-end figure for connected or active power in megawatts; the MW numbers in its disclosure are guidance, site targets and long-run deployment schedules, which is why no honest contracted-to-active conversion rate can be computed from them.
The step that is not disclosed
Asked how connected power becomes revenue, management described a sequence rather than a single switch: commission the data centre, build the network, build the clusters, deploy the platform, onboard the customers, and then revenue generation begins. Management said this takes a few months and, in the same answer, that the 800MW to 1GW of connected capacity should be active throughout the first half of 2027 (Q2 2026 earnings call transcript).
That timing is the substantive disclosure. Connection is not the last step before billing; commissioning, networking, cluster build-out, platform deployment and customer onboarding sit between the two. The company also said almost all of the 5GW of contracted power is due to come online over roughly two to three and a half years, with more than 1GW per year planned from 2027 (Q2 2026 shareholder letter).
On demand, management was unambiguous: the company sold out of capacity because as fast as capacity is brought online it can be sold, and it said it could sell its entire 2027 capacity on the terms struck while deliberately retaining capacity (Q2 2026 shareholder letter, Q2 2026 earnings call transcript). Those are company statements about its own order book, not independently verified commitments. If they hold, the constraint is on Nebius's side of the fence, not the customer's — but the binding step is still defined only in words, not in a disclosed operating metric.
Capital committed ahead of the revenue
The scale of spending relative to reported revenue is the second half of the story. Capital expenditure was approximately $5.7 billion in the second quarter, driven primarily by purchases of GPUs and GPU-related hardware and by data-centre expansion; purchases of property, equipment and intangible assets were $5,657.4 million in the quarter and $8,130.3 million in the half year (Q2 2026 results release, Q2 2026 shareholder letter). First-quarter capital expenditure was approximately $2.5 billion (Q1 2026 shareholder letter). Full-year 2026 guidance was reaffirmed at ARR of $7-9 billion, group revenue of $3.0-3.4 billion, a group adjusted EBITDA margin of approximately 40%, and capital expenditure of $20-25 billion (Q2 2026 results release, Q2 2026 earnings call transcript).
Guidance therefore places capital spending at several times guided revenue for the same year — a structural fact about an owned-infrastructure model rather than an accounting accident.
The funding mix is disclosed in enough detail to avoid reading a shortfall into it. At 30 June 2026 Nebius reported cash and cash equivalents of $8,042.1 million, against $3,678.1 million at 31 December 2025; current deferred revenue of $979.4 million; non-current deferred revenue of $4,995.8 million; and non-current debt of $8,499.0 million, against $4,103.2 million at the end of 2025 (Q2 2026 results release). Net cash provided by operating activities from continuing operations was $2,246.1 million in the quarter and $4,504.1 million in the half year, against outflows of $167.7 million and $352.0 million in the comparable 2025 periods (Q2 2026 results release).
Customer prepayments are doing much of that work. Nebius said it expects over $9 billion in customer prepayments in 2026, and that about 70% of deals closed in the second quarter included prepayments covering 50-60% of the associated capital expenditure (Q2 2026 shareholder letter, Q2 2026 earnings call transcript). Both figures apply to deals closed in that quarter, and the $9 billion is an expectation rather than cash received. Financing actions described on the call included issuance of 12.7 million Class A shares under an at-the-market programme at a weighted average price of about $224 for roughly $2.8 billion gross, with 12.3 million shares still available at 30 June, plus a $775 million asset-backed facility in July 2026 secured against contracted cash flows (Q2 2026 earnings call transcript).
Where the capacity is being built
Nebius said it expanded its contracted capacity footprint in the second quarter with additional sites in the United Kingdom, Estonia and Finland, with construction under way at some owned AI factories in the United States (Q2 2026 shareholder letter). Its Finnish footprint illustrates the pattern: a second data centre at Mäntsälä with up to 70MW coming online from 2027, bringing total capacity in the country to 455MW across three sites (DataCenterDynamics). That is a 2027-and-later schedule, published alongside a 2026 connected-power target it does not change.
What the evidence does not settle
Three limits should be stated plainly. First, no actual period-end figure for connected or active power in MW appears in the disclosure, so the ladder is described but not measured; guidance and site targets cannot be converted into a conversion rate. Second, ARR is a single month's cloud revenue multiplied by 12, which makes it sensitive to when capacity lands inside a quarter.
Third, Nebius publishes no quantified comparison of commissioning time, utilisation or cost between owned and leased capacity; the claim that owned sites are capital-efficient and attractively priced over the long run is a company assertion without an operating benchmark attached.
Quarterly figures are company-reported and unaudited, and the call quotations used here come from a third-party transcript rather than a transcript hosted by Nebius. The honest reading of the 12 August 2026 disclosure is that Nebius has committed capital and land on a scale that outruns current revenue by design, that it says demand is not the constraint, and that the step it has not quantified — the months between a connected megawatt and a billed GPU-hour — is where its own guidance says the 2026 numbers will be decided.
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance