
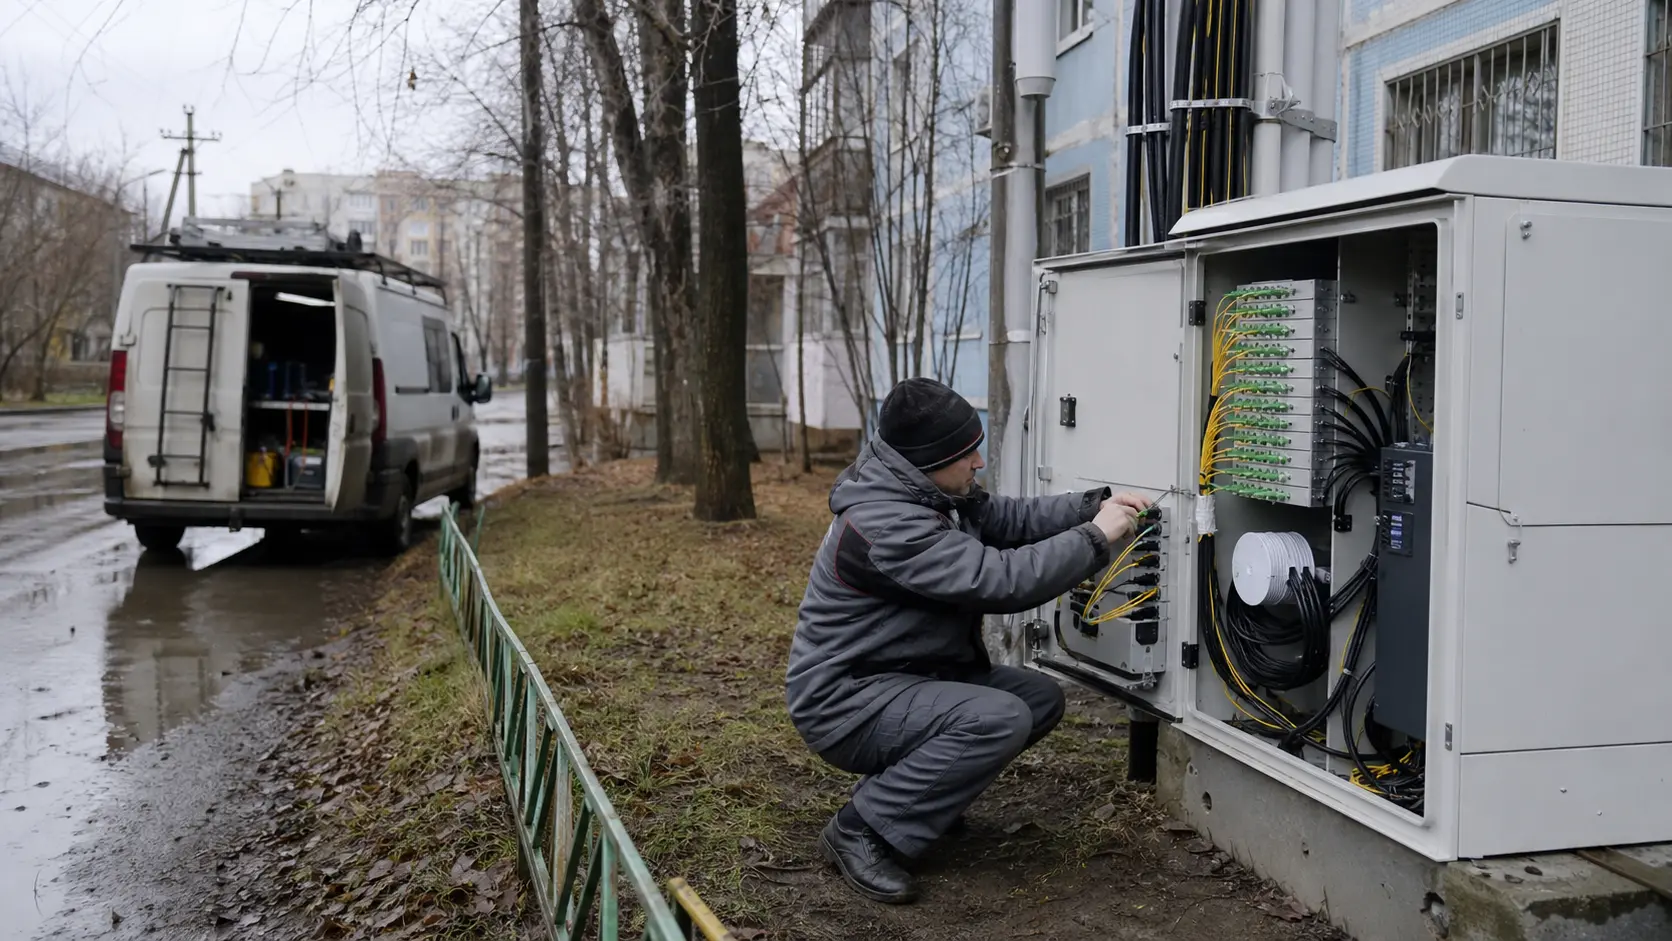
Summary
- In Onlain has the legal and registry shape of a communications company, but the public evidence supports a cautious reading: it is an active Moscow microbusiness, registered for wired communications and related telecom activities, with RIPE membership and recent address resources, yet the visible network footprint around its current IPv4 block is thin.
- The core economic question is not whether a local provider can charge for access in Russia. It is whether this particular entity can turn each installed line into enough retained gross profit to repay installation, upstream capacity, customer support, payment friction, maintenance and equipment replacement before churn or national-carrier substitution resets the payback clock.
- The most important boundary is between rights and use. A RIPE membership record, a /24 IPv4 allocation and a /29 IPv6 allocation are useful operating inputs, but they do not by themselves prove a subscriber base, live access plant, traffic scale, peering leverage or customer concentration. Current public routing and IP intelligence for 194.110.71.0/24 show no visible BGP origin, no reverse DNS, no hosted domains and no obvious active router population.
- The market around In Onlain is not hopeless. Russian fixed broadband still has large household and business demand, tariff benchmarks have been moving upward, traffic continues to migrate from older access technologies to fibre, and smaller operators can defend pockets where installation response, building access and local support matter. But those same facts sharpen the margin test: stronger incumbents can bundle, advertise, absorb truck rolls and amortise civil works across much larger bases.
- The judgment should change only when the public record shows live originated routes, real local coverage, disclosed tariffs, customer retention, supplier terms, support staffing, capital commitments or durable wholesale arrangements. Until then, In Onlain should be treated as an option on local access economics, not as evidence of a scaled regional ISP.
One Line, Then The Company
Begin with one installed access line. The commercial promise is simple: a household or small business pays every month for internet access, perhaps with a static address, television, voice, hosting, VPN or service support layered on top. The financial reality is less forgiving. That one line has to recover the cash spent to connect it, the share of upstream capacity it consumes, the cost of customer equipment, the cost of answering calls and fixing faults, the cost of billing and collection, the cost of regulatory standing, and the periodic replacement of electronics and passive plant.
If the customer leaves before those costs are recovered, the line is not a small annuity. It is a prepaid loss.
Limited Liability Company In Onlain sits exactly at that point in the economics. Russian company records identify it as an active Moscow company with the full Russian name Obshchestvo s ogranichennoy otvetstvennostyu "In Onlain", the short name OOO "IOL", OGRN 1187746554159 and INN 7727364934. Registry aggregators agree on a June 2018 registration date, a small charter capital of 16,027 roubles, Denis Gayarovich Alyautdinov as general director and sole owner, and a main activity code for wired communications.
They also show a broad set of additional activities: internet access, voice data, interconnection, international traffic, wireless communications, cable television, software, data processing, equipment repair and related installation work.
That legal envelope is necessary but not sufficient. It gives the entity a plausible communications purpose; it does not prove where lines have been built, who pays for them, how long they stay, or whether the entity owns last-mile plant rather than sitting inside a related commercial arrangement. The distinction matters because In Onlain is very small in the company data. Some sources show one employee, some show no disclosed staff, and the entity is categorized as a microbusiness. A microbusiness can still be commercially real in telecom if it leans on contractors, related entities and narrow geography.
But it has little room for mistakes when a failed installation, bad debt account, equipment replacement or support-heavy customer can consume months of contribution.
The RIPE record changes the interpretation but does not settle it. RIPE lists Limited Liability Company In Onlain as a member serving Russia, with a Moscow contact address, phone number and the email domain iol.ru. RIPE allocation statistics show 194.110.71.0/24 allocated as provider-aggregatable IPv4 space in February 2026 and 2a0d:d200::/29 allocated in November 2024. That is meaningful. It suggests the company has moved beyond a paper activity code into internet-number administration. It can hold address space, receive registry service and potentially number customer connections, hosting endpoints or network equipment.
Yet address space is not a subscriber ledger. Public IP intelligence for 194.110.71.0/24 is especially stark: no autonomous system is shown for the block, no BGP announcement is visible in the sources reviewed, IPinfo lists no reverse DNS, no hosted domains, no pingable addresses and no router addresses, and IPAddress.com similarly says it could not find an autonomous system advertising the subnet. That does not prove inactivity everywhere. BGP visibility has limits, route data can lag, addresses can be staged before use, and a provider may first serve private-addressed customers behind upstream capacity.
But for an economic judgment, it means the burden of proof stays high. The visible evidence supports preparation or optionality more than an already humming retail footprint.
Rights, Boundaries And Control
The company boundary is unusually important here because iol.ru appears in several places that are not all the same legal entity. RIPE gives In Onlain a contact email at that domain. Separate corporate records for OOO "Opticoms", an older Moscow company under the same person, identify iol.ru and optimacoms.ru as websites for that related company and show a much longer operating history, more employees, revenue and communications licences. That does not make Opticoms the same company as In Onlain.
It creates a control and coordination signal: the person, domain and communications theme overlap, while the legal entities remain separate.
For readers trying to value the operating economics, the safe conclusion is therefore narrow. In Onlain may share people, domain infrastructure, know-how or commercial relationships with a related communications company. It may also have been formed to hold or structure a specific network resource, customer set, licence position, wholesale agreement or local build. But those are possibilities, not facts established by the public record. The article therefore treats In Onlain as its own entity and treats Opticoms as context only.
Any claim about active In Onlain customers, licences, routes, local assets or contracts would need direct confirmation.
That boundary changes the risk. If In Onlain is a shell around a real operating network managed through related parties, then the economics depend on transfer pricing, service agreements and the ability to allocate costs honestly between entities. If In Onlain is the operating customer-facing company, then its tiny public staff base becomes a direct capacity concern. If In Onlain is mainly a number-resource and future-service vehicle, then the current margin is not an access margin at all; it is option value and carrying cost. Each interpretation leads to different downside.
The common feature is that the public record does not yet show which model is true.
The formal activities are broad enough to support many models. The listed telecom codes include internet access and interconnection as well as wired and wireless communications. That breadth could reflect sensible future flexibility for a small provider. It could also reflect a standard registration pattern, where a company adds many possible activities to avoid later amendments. The economic reading should not give equal weight to every registered activity. A code for international traffic is not evidence of international traffic. A code for cable television is not evidence of subscribers.
A code for equipment repair is not evidence of an in-house field force. The only fair use is to say that the entity is legally positioned to pursue those businesses if it has the licences, facilities and contracts required.
The registered address and the RIPE contact address also differ. Company sources point to Nagornaya Street in Moscow; the RIPE member page points to Baltiiskaia Street, office 216. That is not inherently alarming. Legal, billing, contact and operational addresses often differ. But it reinforces the point that the records are administrative. They do not show a service area at street-cabinet level, a list of apartment blocks, a fibre ring, wireless access points, network operation rooms or customer service desks. In telecom economics, those physical facts decide whether the first rouble of monthly recurring revenue is cheap or expensive.
Revenue Starts With Take-Up, Not With Coverage
The first mistake in analysing a local ISP is to value homes passed as if they were paying subscribers. Coverage has option value, but the first line has to be sold, installed and retained. The second mistake is to treat list price as contribution. A residential tariff of 550 to 1,100 roubles a month looks attractive when multiplied by a large addressable base. It looks different after VAT where applicable, payment costs, customer-premises equipment, installer labour, backhaul, transit, support and churn are deducted.
It looks different again if a national operator offers a bundled mobile, broadband and television package in the same building.
The market context supports both hope and pressure. Russian broadband remains large. Government and industry sources point to a fixed and mobile internet-access market worth hundreds of billions of roubles, high household broadband availability and a national ambition to raise broadband availability to 97 percent of households by 2030. Industry reports show growth in telecom revenues, continued traffic expansion and a shift from older access technologies toward fibre.
Rostelecom's 2025 reporting gives a useful benchmark: household fibre internet subscribers reached 12.8 million, with household fibre ARPU at 426 roubles, while business fibre and fibre-plus-VPN services delivered much higher ARPU. Public tariff trackers and regional provider pages show retail home-internet plans commonly clustered from the mid-hundreds of roubles to above 1,000 roubles depending on operator, speed and bundle.
For In Onlain, the key issue is not the existence of demand; it is the cost of customer acquisition and local take-up. A small provider has a chance when the incumbent is slow, when a building manager grants access, when the customer values a fast local response, when the service can be installed without major civil works, or when business customers need a flexible static-address or managed-access solution.
A small provider suffers when the incumbent has already amortised fibre in the building, when access permissions are expensive, when advertising costs rise, when a subscriber expects free installation and a subsidised router, or when a single complaint triggers repeated visits.
The current public network evidence makes the revenue side hard to underwrite. The allocated IPv4 block is only 256 addresses. That can support more customers behind private addressing, but publicly routable IPv4 capacity is scarce if every business customer wants static addresses or if the operator wants to run clean separation across services. The IPv6 /29 is expansive enough for modern subscriber numbering, but in consumer economics IPv6 does not eliminate the need for NAT handling, customer education, legacy-device support or IPv4 connectivity.
If the company is building a true access network, it must still buy transit or wholesale capacity, arrange route origination, maintain DNS and abuse handling, and provide a support experience that customers will tolerate.
The absence of visible BGP for 194.110.71.0/24 is therefore more than a technical footnote. It means no current public route appears in the reviewed sources through which that block is being used as a normal announced access or hosting prefix. If the block is merely staged, then the line economics have not yet begun. If customers are served under upstream-assigned addresses, then the company's own address holdings are not the main indicator of the live base. If the block is used privately, invisibly or through arrangements not captured in the reviewed data, the economics still require disclosure before a strong judgment can be made.
In every case, monthly recurring revenue remains unproven.
Installation Cash Is The First Margin Test
Installation is where a local access line becomes capital rather than sales. A customer may see a router, a cable and a short appointment. The operator sees survey time, building entry, riser access, optical splitter or switch port capacity, drop cable, connector work, a customer-premises device, activation, documentation, payment setup and the risk that the subscriber cancels before the first full year. In multi-dwelling buildings, those costs can be low if plant already exists and take-up is dense.
In private-sector or scattered business access, the same connection can require truck time, aerial or underground permissions, bespoke cable runs and more expensive fault calls.
Russian public tariff evidence shows that the market cannot simply pass all connection cost upfront. Regional offers and tariff-change notices display monthly fees that are competitive by international standards and often include migration to higher speeds rather than a large visible installation charge. Providers may charge for router configuration, static addresses or special work, but the mass-market proposition is still a recurring-fee bargain. That favours incumbents and dense local operators. It punishes providers that must win one subscriber at a time without prebuilt plant.
For In Onlain, the right installation question is: what share of first-year gross contribution is already spoken for before the customer consumes a gigabyte? If a residential line nets only a few hundred roubles a month after upstream, support and equipment cost, then even a modest installation spend can require a long retention period. If churn occurs after six months, the operator may lose money even if every bill is paid. If the customer requires several support calls, a replacement router and a second visit, the line may never repay.
If the customer is a small business paying several thousand roubles a month for a reliable service with static addressing and responsive support, the payback can be much faster, but the service expectation is higher and outages become more expensive.
The difference between a dense building and scattered local demand is decisive. A small provider can survive when it controls a few highly penetrated pockets: one switch, one riser, many apartments, low incremental connection cost and word-of-mouth sales. It struggles when each subscriber is geographically isolated and needs custom work. The current public record does not disclose In Onlain's local coverage, so the conservative assumption should be that installation economics are unproven. RIPE membership and address allocations do not identify the physical topology. Corporate activity codes do not identify the building footprint.
Related-company signals do not identify which entity owns or pays for plant.
The first operational proof point would be boring but powerful: published local tariffs tied to a known service area, installation terms, business connection options, customer equipment terms, and a live route for the company's address space. The next proof point would be either a visible subscriber support surface or procurement and financial records showing recurring communications services. Without that, the investor or counterparty has to model a range, and the range is wide enough to change the conclusion from profitable niche to uneconomic build.
Upstream Capacity, Peering And The Cost Of Being Small
Access revenue does not remain local. Every subscriber turns into upstream demand. The economics improve if the provider can buy transit competitively, peer locally, cache popular content, and keep traffic on inexpensive paths. They worsen if the provider buys small commits, has few bargaining chips, or must backhaul traffic through someone else's network. In that sense a local ISP's routing table is also a cost statement. It shows whether the company can originate its space, whom it reaches, and how dependent it may be on one upstream.
The sources reviewed do not show an In Onlain autonomous system for 194.110.71.0/24. They show address holdings and administrative membership, not live peering leverage. That does not mean the company has no wholesale arrangement. A small operator may buy a managed upstream service and never appear as a distinct origin for early retail traffic. But it does mean the company should not be credited with independent transit economics until those routes are visible.
If a provider lacks its own announced routes, it may be easier to start, but harder to differentiate, harder to manage abuse reputation and harder to offer certain business services cleanly.
IPv4 scarcity adds another layer. A /24 is enough to announce as a normal BGP prefix, but it is not a large retail pool. Carrier-grade NAT can stretch addresses across many residential users, but it creates support and reputation costs. Some games, video platforms, remote-work tools, cameras, payment terminals and business applications behave badly behind shared address translation. Static IPv4 can become an upsell, but only if the provider has enough space and clean routing. The publicly visible absence of reverse DNS and hosted domains on the current IPv4 block suggests either staging or minimal use, not a mature business-service pool.
The IPv6 allocation is better from a long-term architecture perspective. A /29 gives room for proper customer delegation and future services. But IPv6 is not a substitute for market execution. Customers still expect legacy reachability. Support teams still handle home routers and endpoint devices. National and local competitors can also deploy IPv6. The advantage goes to the operator that turns clean numbering into lower support cost and better service quality, not to the operator that merely holds the resource.
Peering and caching also reward scale. Large carriers can justify settlement-free arrangements, cache appliances and multi-region capacity planning because they have traffic volume. A small local operator may be forced to buy transit from the very national carriers that compete for the same customers. That creates a margin trap: the local provider wins a subscriber at a retail price set by the incumbent market, then pays wholesale costs influenced by larger networks. Its defence must come from cheaper local installation, better service, a captive building position, business specialization or under-served geography.
The public evidence for In Onlain does not yet reveal which defence applies.
Support Labour Can Defeat A Cheap Tariff
Support is the hidden cost in a low-ARPU access business. A customer who pays 600 roubles a month but calls repeatedly, requires evening visits, refuses to replace old equipment or disputes every outage can erase the margin from several quiet customers. A business customer paying several thousand roubles a month may be attractive, but the service-level expectation is materially higher. For a microbusiness, the support queue is not abstract. It is the owner's time, a small staff, a contractor, or a related company absorbing labour that still has an economic cost even if it is not visible in In Onlain's own headcount.
The public records raise two support interpretations. One is riskier: In Onlain has too little visible staff to support a meaningful retail base on its own. The other is more benign: support labour may sit in a related company or contractor network while In Onlain holds resources or a narrow customer contract. Both interpretations keep the same question alive. Who bears the labour cost, and how is it recovered from the monthly fee?
The Russian broadband market makes that question sharper because customers have alternatives in many urban locations. Government sources point to very high broadband availability, and national operators keep upgrading from older technologies to fibre. A small provider cannot assume that a dissatisfied customer has nowhere else to go. Local knowledge can win customers, but only if the provider can respond quickly without overspending. A cheap tariff with slow support causes churn. Generous support with cheap tariffs destroys contribution.
The viable middle ground is a dense, well-maintained access footprint where faults are rare and repeatable.
Support costs also rise with equipment diversity. If a provider subsidises or configures customer routers, it takes on firmware, Wi-Fi, power-supply and replacement issues that are not always network faults. Public tariff examples show router setup and static IP as paid extras in some regional offers, which is economically sensible. But competitive pressure often pushes smaller providers to include more help than they can price. When that happens, a customer who appears profitable at activation becomes a labour sink.
For In Onlain, the absence of public service pages, support terms and live network identifiers leaves the support burden unknown. That uncertainty should be carried into the valuation. A company with one well-run business access contract can look small in headcount and still be profitable. A company trying to build residential scale with the same visible staff would be fragile. The difference cannot be inferred from the activity codes.
Capital, Suppliers And Replacement
The cost environment is not gentle. Russian telecom operators have faced equipment-price pressure, logistics constraints and capex discipline. Reports describe telecom-equipment price increases of 10 to 30 percent from several suppliers in early 2025, linked to components, exchange rates, logistics and wage expectations. Large operators cut or tightly managed infrastructure spending in 2025, with reported capex declines for several major groups. A small operator does not escape these pressures. It often faces them with less purchasing power.
The physical access network has several layers of replacement risk. Customer routers fail. Optical network terminals age. Switches need spare capacity. Power supplies and batteries wear out. Cables are cut, damaged or disturbed. If the provider uses poles, ducts, building risers or shared infrastructure, attachment fees and permissions matter. The Moscow-region pole-attachment tariff reduction reported by TASS is a useful reminder that local access economics can move when infrastructure owners change formulas. It also shows why geography matters: a cost change in one region or access method cannot be applied automatically to every provider.
The RIPE carrying cost is visible and modest relative to plant, but it is not zero. RIPE states a 2026 annual service fee of 1,800 euros per LIR, a sign-up fee for new or additional LIR accounts, and smaller per-resource charges for certain assignments. For a scaled operator, that is overhead. For a microbusiness with uncertain revenue, it is one more fixed cost. The true capital burden, however, sits in field equipment and upstream arrangements, neither of which is disclosed for In Onlain.
Supplier concentration is another unresolved risk. A small provider may depend on one upstream carrier, one installer, one building manager, one equipment distributor and one billing arrangement. That can be efficient when relationships are stable. It is dangerous when any link changes price or terms. If the provider lacks its own visible routes, upstream dependence becomes even more important. If a related company provides support or wholesale capacity, related-party dependence must be understood.
If In Onlain owns the number resources but another entity owns customer relationships, the economic value may not sit where the directory entry suggests.
Replacement capital also interacts with churn. If a provider installs equipment and the customer leaves quickly, recovered value depends on whether the equipment can be reused, whether the drop remains useful for a future subscriber, and whether the provider controls the building. Dense access footprints allow reuse. Scattered custom connections strand capital. Public records do not show which profile fits In Onlain. That is why the installed-line framing is the right one: the company earns value only when the line survives long enough to turn capex into contribution.
Competition And Substitutes
In Onlain's competition is not only the nearest local ISP. It includes national fixed operators, mobile operators, bundled offers, wireless broadband, building-level incumbents, business fibre providers and the possibility that customers choose a mobile hotspot or enterprise carrier instead of a small fixed line. Russia's market structure gives major players advantages in brand, procurement, mobile bundling, customer service tooling and network depth. Rostelecom's reported household fibre base and business ARPU illustrate how much scale and segmentation a national provider can bring to the same access problem.
A small provider can still win when the contest is local. It can know a building manager, install quickly, answer calls personally, serve a business that is too small for enterprise attention but too demanding for mass-market support, or cover an area where national networks are technically present but commercially indifferent. In those situations, a local operator's smallness is a feature. It can price custom work, respond fast and keep decision-making close to the customer.
The risk is that the market does not let it charge for that closeness. If customers compare only advertised monthly price and headline speed, a small operator with higher unit costs has little room. Public tariff examples show that home-internet pricing can be quite low for the speeds offered. National operators can absorb promotions and bundle media or mobile discounts. Pay-TV market data also matters: television can add revenue, but the segment has low growth, OTT substitution and churn pressure. Bundling helps only if the provider has attractive content terms and low support cost.
Business access may be more promising. Rostelecom's business fibre and fibre-plus-VPN ARPU figures are far above residential fibre ARPU. A small provider with local trust and reliable installation could earn better economics from small offices, shops, medical offices, industrial sites or property managers than from price-sensitive households. But business customers also demand uptime, static addressing, documentation and fast repair. A /24 IPv4 block could be useful there, but only when it is routed, reputationally clean and supported. The current public signals do not yet show that.
The strongest substitute may be inaction by the customer. If an existing line works well enough, switching imposes inconvenience. A new entrant must either be cheaper, faster, more reliable, more responsive or more available. Each path has cost. Being cheaper cuts margin. Being faster may require better equipment and backhaul. Being more reliable requires redundancy. Being more responsive requires labour. Being more available requires build. There is no free strategic position in local access.
Regulation And Geopolitics
Communications in Russia is a regulated business. Licences, data obligations, blocking orders, lawful-intercept requirements, personal-data responsibilities and other state-facing duties can affect operator cost and risk. The sources reviewed here do not establish the full licence position of In Onlain itself. They do show that related telecom entities and national operators operate within licence-heavy frameworks, and that government policy continues to emphasize broadband availability, domestic digital infrastructure and the resilience of communications networks.
For In Onlain, the regulatory issue should be treated as an evidence gap rather than a verdict. A wired-communications activity code is not a communications licence. A RIPE membership is not a service authorization. A routed prefix is not proof of lawful retail service. Conversely, absence of a publicly surfaced licence in the sources reviewed here is not proof that no licence exists. The prudent position is that any commercial underwriting should require current licence evidence, service territories, regulator-facing obligations and the terms under which the company may provide internet access or related services.
Geopolitical and supply-chain risk enters through equipment, software, routing dependencies and sanctions-constrained procurement. Equipment-price reports show that Russian network operators face component, logistics and currency pressure. A small provider may not have the inventory or vendor relationships to buffer disruptions. If it relies on imported optical equipment, routers or switching gear, replacement lead times and cost swings matter. If it relies on domestic alternatives, performance, compatibility and support terms matter. Either way, the subscriber does not care why a fault is hard to fix. The subscriber pays for working access.
Regulation can also change competitive economics. Government broadband targets can support network expansion, but they can also strengthen larger operators that win subsidy, universal-service or state-backed projects. Local access rules, pole tariffs and building-entry rights can help small operators in specific places, yet those benefits depend on geography and implementation. In Onlain's public footprint is not specific enough to credit it with any particular regulatory advantage.
The practical risk is asymmetry. A national operator can spread compliance staff, legal updates and reporting systems across millions of subscribers. A microbusiness cannot. That does not make the microbusiness impossible; it makes simplicity valuable. The more In Onlain can concentrate on a narrow, well-understood customer base with repeatable terms, the easier it is to manage regulatory overhead. The more it tries to mimic a full national portfolio, the faster complexity consumes margin.
Unofficial Signals And What They Do Not Prove
Several unofficial or secondary signals are useful but limited. Business registries and contractor databases converge on the same corporate identifiers, owner and main activity. IP intelligence sites converge on the lack of visible current activity for 194.110.71.0/24. Related-company pages connect the same person to Opticoms and show iol.ru as a website in that older company's profile. Tariff trackers and regional provider pages show the market price band in which access providers compete. Industry media describe capex, equipment and broadband revenue pressures.
These signals are directly usable only when kept in their lane. A company directory can support identity; it cannot prove active customers. An IP range page can support a lack of visible routing; it cannot prove the company has no private or upstream-numbered users. A related-company page can support a control-boundary question; it cannot transfer revenues, licences or customers from one entity to another. A national market report can support ARPU and demand context; it cannot assign that demand to In Onlain.
The contradictions are also informative. Headcount is not perfectly consistent across sources. The legal address differs from the RIPE contact address. The RPKI certificate display includes resources beyond the IPv4 and IPv6 allocations highlighted in the allocation table, but that does not by itself explain current commercial use. Some market sources present different fixed-internet revenue figures depending on definition, year and segment. Those discrepancies do not ruin the analysis; they prevent overclaiming.
The cleanest current thesis is therefore conditional. In Onlain has enough formal apparatus to be a plausible local access participant or resource-holding vehicle. It does not yet have enough visible public network and commercial evidence to be treated as a proven regional ISP. Its upside is real if it can attach new customers cheaply, keep churn low, route its resources cleanly, use related expertise without hidden cost leakage, and focus on customers whose monthly payments exceed support burden.
Its downside is that the same monthly payments can be too small to repay the first installation before a customer leaves or a cheaper national-carrier alternative appears.
What Would Change The Judgment
The first fact that would change the judgment is visible route origination. If 194.110.71.0/24 begins to appear in BGP with a stable origin, sensible upstream diversity, matching route objects, reverse DNS, abuse contacts and customer or infrastructure hostnames, the resource story becomes more operational. If 2a0d:d200::/29 appears in customer delegations or service documentation, the company would look more like a provider preparing modern access rather than merely holding resources. If there is still no route, the address-resource carrying cost remains a sign of optionality.
The second fact is local coverage. A list of buildings, districts, business parks or service territories would allow installation economics to be modelled. Dense multi-dwelling coverage would support residential margins. A small-business focus would shift attention toward reliability and service-level pricing. Private-sector scattered coverage would raise the payback hurdle. Without territory, no one can tell whether a subscriber is cheap to add or expensive to reach.
The third fact is tariff structure. A provider that charges installation fees, router rental, static-address fees and business support separately has a different risk profile from one that includes everything in a low monthly fee. Public tariff examples show that competitors can offer attractive headline prices; In Onlain would need either cost discipline or differentiation. A tariff table alone would not prove customers, but it would clarify the intended model.
The fourth fact is customer concentration. A microbusiness can be stable with a handful of business customers if contracts are durable and service obligations are priced correctly. It can be fragile with many low-paying residential customers if support demand is high. It can also be fragile if one building, one customer or one related party supplies most revenue. No public source reviewed here discloses the mix.
The fifth fact is cost structure. Upstream contracts, equipment supplier terms, use of contractors, related-party support, lease or pole arrangements, and capex commitments would decide whether the line economics work. A small provider with low fixed cost and dense plant can earn an acceptable return on modest ARPU. A small provider paying premium wholesale and truck-roll costs cannot.
Until those facts appear, the economically honest conclusion is restrained. In Onlain is not a generic company profile. It is a narrow margin question in a market where access demand exists but scale matters. The company has legal identity, communications activity codes, RIPE standing and fresh resources. It also has thin visible routing, no public proof of subscriber scale, unclear support capacity and unresolved related-entity boundaries. One installed line can be valuable only if it stays long enough, consumes predictably, needs little support and is attached at a cost the monthly fee can repay.
That is the whole business in miniature, and for In Onlain it remains the test.
Sources
- https://www.ripe.net/membership/member-support/list-of-members/ru/iol/
- https://www-public.telecom-sudparis.eu/~maigron/rir-stats/ripe-allocations/allocations/ru-ip-allocations.html
- https://www-public.telecom-sudparis.eu/~maigron/rir-stats/ripe-allocations/ipv4/by-number/ru-ipv4-by-number.html
- https://www-public.telecom-sudparis.eu/~maigron/rir-stats/ripe-allocations/ipv6/by-number/ru-ipv6-by-number.html
- https://lir.internet-registry.net/?cdir=desc&country=ru&csort=lirs&dir=desc&p=5&sort=total_slash24
- https://ipinfo.io/ips/194.110.71.0/24
- https://www.ipaddress.com/ipdb/ipv4-public/194.110.71.0/24/
- https://console.rpki-client.org/rpki.ripe.net/repository/DEFAULT/PluwZCHU7nZU_UO77wgZSWdAONQ.cer.html
- https://www.ripe.net/membership/payment/
- https://www.ripe.net/membership/ripe-ncc-organisational-documents/charging-schemes/
- https://companies.rbc.ru/id/1187746554159-obschestvo-s-ogranichennoj-otvetstvennostyu-in-onlajn/
- https://companies.rbc.ru/amp/ogrn/1187746554159/
- https://check.tochka.com/company/1187746554159/
- https://spark-interfax.ru/moskva-kotlovka/ooo-iol-inn-7727364934-ogrn-1187746554159-6e4211af85182e06e0531b9aa8c09d0e
- https://indicator.bifit.ru/ui/report/7727364934
- https://globas.credinform.ru/search/company-card/llc-iol-7727364934-53838cd474844d82a0edaa4026f9c389
- https://cio-navigator.ru/iol-7727364934/
- https://damia.ru/catalog-orgs?active=0&id=2&okved=61.1&page=12®ion=77&sort=name
- https://damia.ru/catalog-orgs?active=0&id=2&okved=61.10&page=36®ion=&sort=
- https://companium.ru/id/1037736027999-optikoms
- https://zachestnyibiznes.ru/company/ul/1037736027999_7736239418_OOO-OPTIKOMS
- https://reputation.ru/ogrn/1037736027999
- https://tmt-consulting.ru/napravleniya/telekommunikacii/tmt-rejting-rossijskij-rynok-telekommunikacij-predvaritelnye-itogi-2024-goda/
- https://www.cableman.ru/content/issledovanie-telekom-rynok-v-rossii-vyros-na-67-v-2024-godu
- https://www.kommersant.ru/doc/8422788
- https://www.akm.ru/eng/press/the-results-of-the-year-for-the-russian-telecom-industry/
- https://marketing.rbc.ru/research/53595/
- https://www.company.rt.ru/press/news/d477115/
- https://dominternet.ru/analytics/prices/
- https://www.kmvtelecom.ru/news/IzmenenietarifovnaInternets01aprelya2025goda/
- https://kto34.ru/router/tarif.php
- https://www.cableman.ru/content/dokhody-rynka-rossiiskogo-platnogo-televideniya-sostavili-1084-mlrd-rublei-v-2024-godu
- https://www.kinometro.ru/news/show/name/paytvrussia25_30042026
- https://www.vedomosti.ru/technology/articles/2026/03/10/1181637-kapitalnie-vlozheniya-operatorov-svyazi-v-infrastrukturu-sokratilis//
- https://telecom.cnews.ru/news/top/2025-01-28_v_rossii_vyrosli_tseny_na
- https://tass.ru/ekonomika/25560349
- https://mintrans.gov.ru/press-center/branch-news/7783
- https://government.ru/docs/all/156833/
- https://www.rosstat.gov.ru/statistics/price/
- https://www.rosstat.gov.ru/storage/mediabank/70_16-05-2025.html
- https://mintrans.gov.ru/press-center/branch-news/9244
- https://www.company.rt.ru/about/lic_and_cert/licence/?ORDER=ASC&SORT=NAME
- https://stat.ripe.net/docs/data-api/api-endpoints/routing-status.html
- https://data.stat.ripe.net/docs/data-api/ripestat-data-api
- https://www.ripe.net/publications/documentation/developer-documentation/rpki-management-api/
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance