
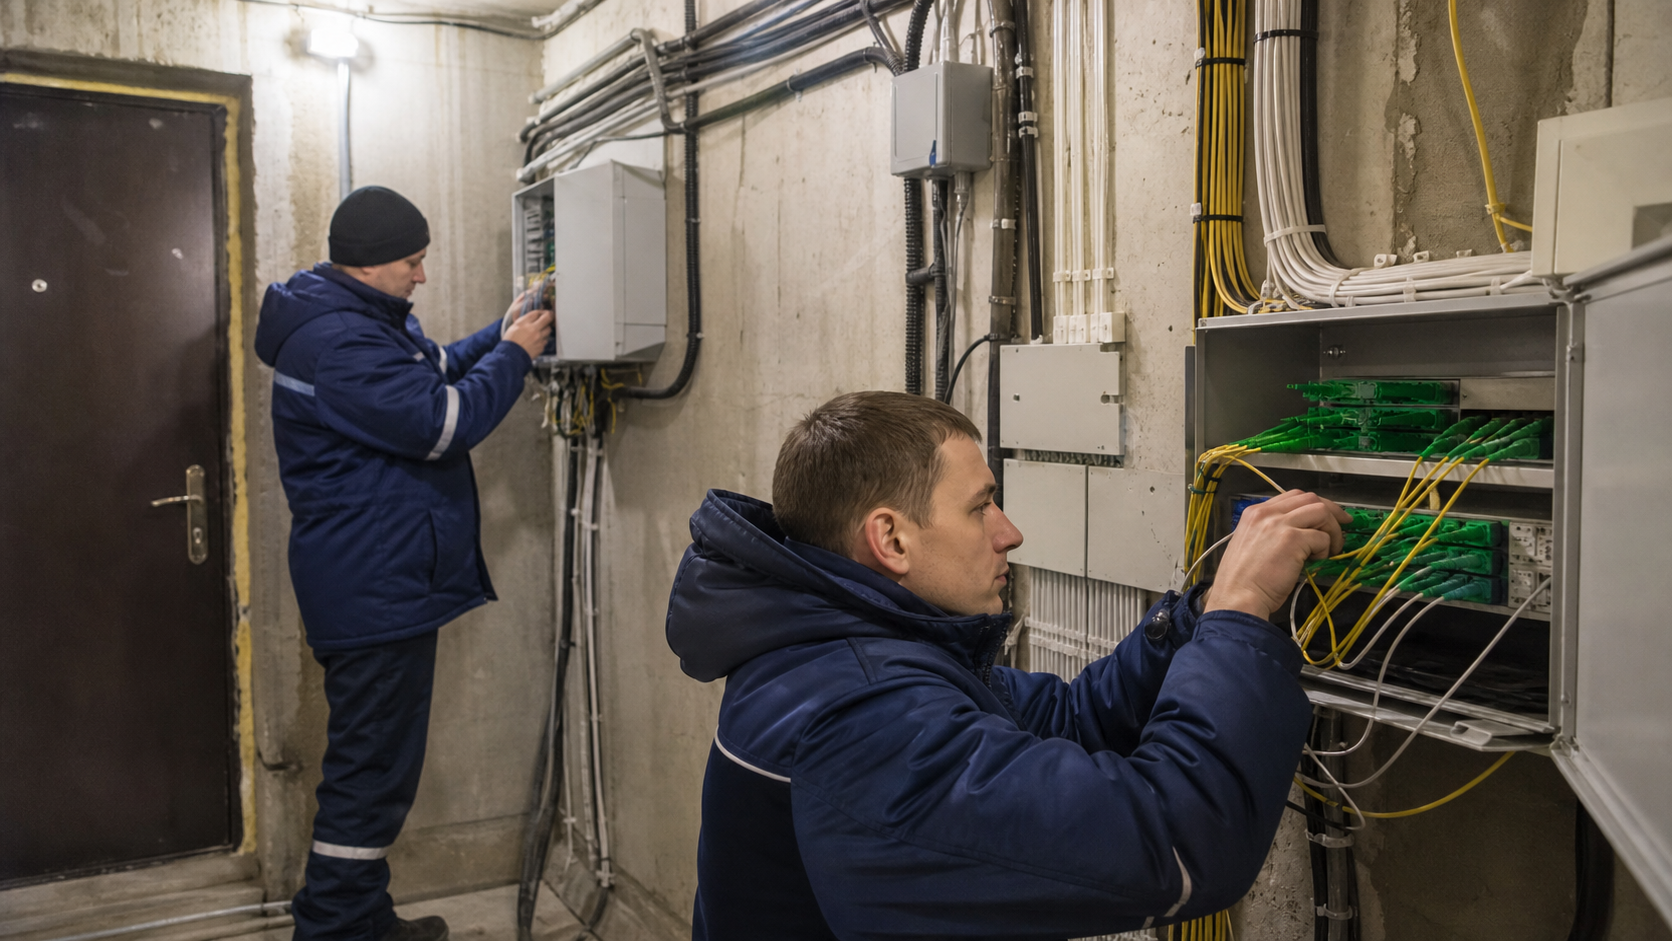
Summary
- The economic incentive for LLC Enginet+ is not the glamour of owning an autonomous system; it is the monthly spread between a local subscriber's prepaid bill and the fixed cost of keeping a small Russian access network lit. Its retail site advertises home broadband at 500, 700 and 900 rubles per month for port speeds up to 100, 500 and 1,000 megabits per second, while the contract terms make clear that service is prepaid, technical feasibility can limit high-speed connections, and the stated speed is a maximum rather than a guarantee. That gives Enginet+ useful downside protection, but it also says the network must sell density and support responsiveness rather than a unique technology.
- The company's network evidence is real but narrow. AS61380, ENGINETPLUS-AS, is visible in RIPE and routing databases, with one originated IPv4 prefix, 185.8.156.0/22, or 1,024 IPv4 addresses, and no visibly originated IPv6 prefix in the main public ASN summaries reviewed. The same public evidence shows upstream dependence on nearby Russian networks, especially Ivanteevskie telecommunicacii Ltd and JSC Mediasoft ekspert. That is not fatal for a local ISP, but it means the value case turns on local take-up, supplier terms, route resilience and low field-service cost, not on national-scale network control.
- The public financial mirrors point to a very small operating company. Several counterparty and company-data services show annual revenue around 15.7 million rubles in recent periods; some also show losses in 2024 and 2025, while older cached company pages report a different profit and ownership picture. The safest reading is that Enginet+ is economically thin, not absent. A rough revenue-equivalent calculation shows that 15.7 million rubles equals about 1,450 to 2,620 residential broadband subscriber-years at its current headline price band if all revenue came from home internet, which it does not. Telephony, TV, business service, municipal video/data work and static-IP or support add-ons could change that mix materially.
- Elias Ward judgment: Enginet+ is investable only as a disciplined local-contribution story, not as a scale network story. The positive case is a compact footprint, prepaid billing, owned numbering/routing identity, local support contactability, and the ability to bundle access with telephony, TV and site-specific municipal or business work. The negative case is thin revenue, no disclosed subscriber count, a small public address footprint, possible supplier concentration, contradictory public data on profitability and control, and larger alternatives available to residents and businesses in Ivanteevka. The judgment would improve with verified active subscriber counts, churn, gross margin after transit, utilization by access node, capex age, building-access rights and the share of revenue from recurring business customers. It would worsen if the 2024/2025 losses are confirmed as operating rather than one-off, if upstream terms tighten, or if larger operators take the same buildings at lower support cost.
The incentive starts at one active port
Enginet+'s economics begin with a single access port rather than with the corporate registry. The operator can install or enable a household connection only where its access network, building entry, customer equipment and upstream capacity are already near enough to make the activation worth the work. The tariff page makes that point indirectly. A customer can choose the Plus 100 plan at 500 rubles per month, the Plus 500 plan at 700 rubles per month, or the Plus 1000 plan at 900 rubles per month. The larger two plans are not simply a higher number on a marketing table.
The site says connections above 100 megabits per second are subject to technical feasibility, require customer equipment with a gigabit Ethernet port, and require an advance payment of 1,500 rubles. That is a practical local-network rule. Enginet+ is trying to avoid promising a gigabit service into places where the access segment, customer router, in-building wiring or backhaul will make the promise uneconomic.
The company also protects cash flow through prepaid billing. The public offer defines the subscriber account as the place where payments are credited and consumed, states that service is provided only with a sufficient positive balance, and says monthly plan fees are deducted at the start of the billing period. For a small access provider this matters as much as the headline speed. Prepayment shifts working-capital risk away from the operator. If a household does not top up, service can stop before the provider has carried another month of traffic, support calls and upstream usage without revenue.
The tariff notes add another important limit: recalculation for days when a subscriber voluntarily does not use the internet is not made, and the advertised speed is the maximum port speed, dependent on resource load, network activity and communications-channel load. The operator is selling access to a shared local network, not a dedicated wholesale circuit with a hard throughput covenant.
Those terms do not make Enginet+ risk-free. They reveal the cost problem. At 500 rubles per month, an access line contributes only 6,000 rubles per year before upstream capacity, staff, billing systems, equipment failure, building visits, licences, taxes and replacement capex. At 900 rubles per month, the line contributes 10,800 rubles per year before those same costs. That is enough for a local operator only when many customers share the same nearby network assets and when support work is controlled.
A single low-density building, a string of trouble tickets, or a required fibre extension can consume years of gross revenue from one household. The economic value therefore sits in clusters: buildings, streets, small offices or municipal sites where Enginet+ already has plant, access rights, customer recognition and a reason to keep the incremental truck roll low.
The same retail structure shows why price alone cannot be the moat. The difference between 100 megabits and 1,000 megabits is only 400 rubles per month. If the gigabit plan cannibalizes a 100-megabit customer without increasing backhaul cost or field work much, it is attractive. If it forces new switches, customer router support and higher contention risk, it can be value destroying. That is the central access contribution test. The provider needs enough customers on each active segment to absorb fixed network and labour cost, but it must avoid turning every speed upgrade into a bespoke engineering job.
Its own technical-feasibility language suggests management understands this boundary.
Identity is clear, but the control boundary needs caution
The operating identity is reasonably clear. The service site describes itself as the official site of ООО "ИнжиНэт+", uses the newer "Inji" branding, and says the older engplus.ru domain has moved to inji.online. Its contact section gives an office address on Lenina Street in Ivanteevka, sales and support phone numbers, and service addresses for business, accounting and technical support. The public offer uses the full legal name, identifies the operator as LLC Enginet+, names telecom licences, and gives a legal address on Pervomayskaya Street.
RIPE membership and routing records also identify LLC Enginet+ as the resource holder behind AS61380 and the 185.8.156.0/22 prefix. Domain and IP intelligence sources tie engplus.ru and inji.online infrastructure back to the same network or organization.
That evidence is enough to treat LLC Enginet+ as a real local telecom operator, but it is not enough to treat every "Enginet" or "Inzhinet" record as the same economic entity. Several public records refer to older or similarly named entities, including ZAO Enginet+ and EngiNet without the plus sign. A separate network, AS31720, appears in Russian network listings under EngiNet, OOO and is connected with different historical address space. That should not be folded into LLC Enginet+ without direct legal or routing linkage.
The public offer and the current registry mirrors show LLC Enginet+ as the entity for this local service; other names are relevant mainly because they explain why searches around "Enginet" can produce false scale.
The control picture also requires restraint. Some company-data mirrors show older leadership and ownership details; others report a 2025 change in general director and founder structure, including Irina Konkova as general director and several individual shareholders. The public offer reviewed names Irina Mikhailovna Konkova as general director, while an older cached company page still shows Andrey Mashichev and a single-founder structure. These are not merely clerical details. For a small ISP, control determines whether local access rights, customer lists, upstream contracts and support staff are stable.
A change in management can be a normal succession, a reorganization, or a response to financial stress. Without a current primary extract from the Russian company register, the prudent conclusion is that control has visible change signals but not a fully resolved public explanation.
That uncertainty affects the investment judgment. If the company has continuity from the older ZAO or Enginet+ operation, the brand may carry local trust and long-standing building access. The domain history for engplus.ru is old, and local directories list Enginet+ among Ivanteevka internet providers with legacy contact details. But legal continuity and customer continuity are different things. A company can inherit a brand and still have a small balance sheet, changed ownership and a narrow active network. The value of the name therefore depends on how many paying locations remain active, not on how long the label has existed online.
Network resources are real, but small
AS61380 is the strongest hard infrastructure marker for Enginet+. Public routing databases identify AS61380 as ENGINETPLUS-AS, assigned in November 2012, with LLC Enginet+ as the registered organization. The main visible IPv4 asset is 185.8.156.0/22. A /22 is 1,024 IPv4 addresses, equivalent to four /24 blocks. BGP tools, IPinfo, IPIP and IPLocate all show one IPv4 prefix and no visible originated IPv6 prefixes in their current ASN summaries, while a RIPE allocation listing also records a 2a03:3dc0::/32 IPv6 allocation associated with ru.engplus.
That creates a useful distinction: an IPv6 resource may have been allocated, but the reviewed public route summaries do not show it as visibly originated from AS61380. Economically, the current access business still looks IPv4-led.
The address count is small, but it should not be confused with the number of customers. Residential ISPs can serve more customers than public IPv4 addresses through private addressing and NAT, and business services can use addresses more intensively or charge for static assignments. Still, the /22 constrains what can be inferred. Enginet+ is not operating like a broad national access network with many public prefixes. It looks like a compact local operator with one main block. That has benefits and risks. The benefit is simplicity: fewer prefixes, fewer routing objects and fewer address-management burdens.
The risk is limited room for public-address growth, reduced ability to sell address-rich business services, and a weaker signal to wholesale partners or content networks than a larger network would send.
The upstream picture reinforces the local scale. BGP tools and IPinfo show upstream reach through AS48149, Ivanteevskie telecommunicacii Ltd, and AS48347, JSC Mediasoft ekspert. The RIPE aut-num object also contains import and export references to AS34123, AS48149 and AS48347. That means Enginet+ has, at least on paper, more than one upstream relationship, but the live summaries emphasize two visible paths. For a local ISP, two upstreams are better than one, but they are not the same as independent national route diversity. One supplier, Ivanteevskie telecommunicacii, is itself an Ivanteevka-region access network and a local competitor.
Another, Mediasoft, is a broader Moscow-oriented network with many downstream and peering relationships. Enginet+ therefore appears to buy or exchange reach through nearby Russian connectivity rather than rely on its own distant peering footprint.
RPKI and IRR details are positive but not decisive. Public tools mark the 185.8.156.0/22 origin as RPKI valid or IRR valid, depending on the database. That reduces the risk of accidental route rejection and shows basic routing hygiene. It does not prove profitability, spare capacity or customer quality. A well-maintained route object can belong to a small network under economic pressure. Conversely, a small access provider can be durable if its few routes serve dense paying demand. The economic question is whether the route and address resources carry enough recurring revenue to justify the support and renewal burden.
Ping and geolocation data place the network in the Moscow Oblast orbit, with low measured latency from Moscow probes and IP locations around Ivanteevka, Korolev or Moscow Oblast depending on the database. That fits the service proposition. Enginet+ is not trying to monetize global hosting traffic; it is trying to keep local households and small organizations online. Locality is the asset. If the operator can resolve faults faster than a distant large carrier, keep billing simple, and maintain relationships with buildings or municipal users, the small network can survive despite limited scale.
If local service does not outperform alternatives, the same locality becomes a trap, because fixed plant and staff remain while subscribers churn to bigger bundles.
Revenue density is the central calculation
The public financial data is thin and partly contradictory, but it is enough to frame the unit economics. Company-data mirrors show revenue around 15.7 million rubles in recent years. B2B House reports revenue of 15.673 million rubles for 2025 and 15.764 million rubles for 2024, with losses in both years on its main page, while an older RBC Companies crawl reports 2024 revenue of 15.758 million rubles and profit of 1.679 million rubles. The safer conclusion is not to choose one mirror as final, but to note that revenue appears roughly flat and small, and that profitability is uncertain.
A telecom access network with flat revenue and possible losses must be judged on contribution discipline, not headline subscriber ambition.
A rough tariff-equivalent calculation is useful. If the entire 15.7 million rubles of annual revenue came from the 500-ruble home broadband plan, it would equal about 2,620 subscriber-years, or the same number of average monthly customers over a year. At 700 rubles, it would equal about 1,870 subscriber-years. At 900 rubles, it would equal about 1,450 subscriber-years. These are not subscriber counts. The revenue base also includes telephony, TV, business customers, equipment sales, local project work and possibly installation or support charges. But the calculation shows the order of magnitude.
Enginet+ can be an economically real local ISP without being large. It also shows why churn is dangerous. Losing a few hundred active residential equivalents would be material if the revenue base is only in the mid-teens of millions of rubles.
The IPv4 footprint creates a second calculation. One /22 gives 1,024 public IPv4 addresses. If each public address mapped to one 700-ruble retail customer, the annual gross would be about 8.6 million rubles. Since reported revenue appears higher than that, either the company serves more billable relationships than public IPv4 addresses through NAT, earns revenue from services other than home broadband, prices some customers above the retail plan, or the public financial mirrors include items not directly comparable to current tariffs. Each interpretation matters. More NAT'd households can improve revenue density if support stays low.
More business service can improve average revenue but may increase uptime expectations. Project work can lift revenue but may be non-recurring. Without the revenue mix, the valuation must discount certainty.
Staff data has the same problem. Public mirrors have reported average headcount figures around nine employees in older periods, seven in 2024, or five in 2025. If the five-employee number is current, revenue per employee would be roughly 3.1 million rubles at a 15.7 million ruble revenue base. That is not obviously weak for a micro-operator, but it leaves little room for many specialized functions. Network operations, billing, sales, field support, accounting, regulatory work and customer communication must be covered by a small team or by contractors.
The offer allows the operator to involve third parties in providing services and performing work, which can protect fixed payroll but introduces contractor quality and availability risk.
Capital renewal is the harder unseen cost. Access switches, customer premises equipment, routers, fibre repairs, power backup, monitoring, billing systems and licences age whether subscriber count grows or not. The current site advertises a Wi-Fi router at 4,300 rubles, which gives a retail marker for customer equipment but says little about the cost of distribution switches or backhaul. The site's note that high-speed plans require suitable customer equipment and technical approval signals that the operator is trying to avoid absorbing every upgrade cost.
Still, if customers increasingly expect gigabit speeds, older apartment-building wiring or access switches can turn a profitable cluster into a capex queue. The question is whether Enginet+ has enough cash contribution to refresh assets before service quality falls.
Suppliers and risk transfer
Enginet+ transfers several risks to customers through contract terms, but it cannot transfer supplier risk. Its upstreams matter because local retail revenue is only valuable if packets can leave the local network reliably and cheaply. AS48149, Ivanteevskie telecommunicacii Ltd, appears in public routing tools as one of Enginet+'s upstreams and as a larger local access network with 12,288 IPv4 addresses, five IPv4 prefixes and two IPv6 prefixes in several public summaries. IPinfo classifies it as a consumer ISP with visible day-night usage patterns, and BGP tools tags it as a home ISP. That makes it both a supplier and an alternative.
If Enginet+ depends on a nearby access operator for reach, it must keep a relationship with a party that may also compete for the same buildings and customers.
AS48347, JSC Mediasoft ekspert, is a different kind of supplier. Public routing records for Mediasoft show a much broader downstream and peering environment, including references to content, hosting, protection and exchange relationships. BGP.he's page for AS48347 explicitly lists LLC Enginet+ as a downstream in the RIPE text it displays. That gives Enginet+ a route to wider connectivity through a larger network. It also makes wholesale terms important.
If transit prices rise, if filtering or regulatory requirements become more burdensome, or if the supplier changes its customer policy, Enginet+'s retail tariff ladder may not adjust fast enough. The offer says the operator can publish tariff changes with at least ten days' notice, but competitive pressure may make price increases hard.
The third upstream named in the RIPE object, AS34123 Netorn, is harder to judge from the reviewed live summaries because it is not as prominent in the current public BGP views for AS61380. It may represent an older, backup or less visible relationship. The prudent economic reading is that Enginet+ has some route-policy diversity on paper, but not enough public evidence to price it as deeply redundant. For a local access provider, that matters less than it would for a data centre network, but it still affects customer retention.
Residential users tolerate occasional degradation until a larger bundle is available; business or municipal users may not.
Customer-side risk transfer is clearer. The public offer lets Enginet+ suspend service when the account lacks funds, requires subscribers to maintain their own equipment and software, allows maintenance interruptions with notice, and disclaims responsibility when third-party power outages occur without operator notice. The rules also prohibit resale or unauthorized sharing of service. These clauses protect the operator from becoming the unpaid guarantor of every customer environment. In economic terms, they preserve the access business as a standardized service rather than a managed IT contract.
The problem is that customer expectations may still behave like a managed service. When internet fails, households blame the provider first, even if the issue is Wi-Fi, a router, a payment lapse or in-building wiring.
This is why local support labour is not a footnote. The site advertises a round-the-clock support phone, separate emails for business customers, accounting and support, and a move toward a newer authorization system and mobile application. Those are valuable retention tools if they reduce calls, billing friction and truck rolls. They are costs if they add systems without increasing revenue. A small ISP's advantage is often that a person nearby can solve a local issue faster than a national call centre. Its disadvantage is that each support obligation consumes a noticeable share of staff time.
The best version of Enginet+ is a compact operation where prepaid billing, local knowledge and building familiarity keep support cost low. The worst version is a small team pulled between network maintenance, new installs, old equipment and customers who expect national-operator service levels at local prices.
Customers, concentration and project work
No public material reviewed gives a verified subscriber count or a customer concentration schedule. That is the single largest gap in the economic judgment. The tariff page shows a home-market product, the contacts identify business support, the offer covers individual subscribers, and the documents page lists licences for data, telematic, cable broadcasting, local telephony and channel services. Procurement mirrors also show that LLC Enginet+ has supplied public-sector or municipal-type communications work.
One tender page for Pushkinsky district work names LLC Enginet+ as winner for providing video images from entrance cameras for the "Safe Region" system at Golandsky quarter, with a contract value just above 2.1 million rubles. B2B House reports broader participation in 17 procurements, 16 wins and total customer contracts of about 18.64 million rubles, although some customer names are masked in its free view.
That mix is economically double-edged. Project and municipal work can lift revenue above the household tariff base and use the operator's local fibre or site access more profitably. A camera feed or dedicated link can be stickier than a household broadband plan if the customer values continuity and local maintenance. It can also create concentration risk. If a small operator wins a few meaningful local contracts, revenue looks stronger while the contracts run, but a renewal loss or delayed payment can expose fixed network and payroll costs.
The reported 2.1 million ruble video contract would be material against a 15.7 million ruble revenue base, even if it is not all recognized in one year.
Business customers may be better than households when they pay for reliability, static addressing, telephony, CCTV or local support. They may be worse when they negotiate hard, require service credits, or need custom fibre work. Enginet+'s documents include licences for services beyond simple home broadband, and the site gives a B2B email. That is enough to say the company has a route to higher-value accounts. It is not enough to say those accounts dominate. A strong diligence file would break revenue into residential broadband, business access, telephony, TV, equipment, installation, municipal projects and one-off engineering.
Without that, the article's judgment must remain conditional.
Customer concentration also interacts with public IPv4 scarcity. If a few business customers consume many public addresses or support hours, the apparent efficiency of the /22 can deteriorate. If most households are behind NAT and few need static addresses, the same /22 can support more revenue. If the company uses private addressing aggressively, it may manage address scarcity but increase troubleshooting complexity for gaming, remote access, CCTV or small-office services.
The offer's rules about internal IP-address allocation and the operator's ability to change those conditions show that Enginet+ keeps discretion over address policy. That is rational, but customer satisfaction depends on how often the policy collides with real use cases.
The local directories add unofficial demand signals. Ivanteevka directories list Enginet+ alongside Ivanteevskie telecommunicacii, Ivstar, Ivlan, Rikom NTC, Beeline, MTS, Rostelecom and other providers. Some address-based comparison pages show multiple providers and tariffs available in specific Ivanteevka buildings. These are not audited market-share data, but they prove customers are not captive to one option. A local ISP can still win against larger alternatives when it has building access, better support, familiar billing or a niche bundle. It cannot assume that local presence alone prevents churn.
The economic value of each active port must therefore include expected retention, not just current monthly price.
Competition is not abstract
Enginet+'s competitive threat is visible in two layers: local fixed networks and national bundle operators. The local layer includes Ivanteevskie telecommunicacii, Ivstar, Ivlan, New Line and other Ivanteevka-listed providers. Some have physical offices or addresses in the same town. This matters because local fixed broadband competition is often building-by-building. The winner is not necessarily the carrier with the biggest national balance sheet; it is the provider already in the riser, already known to building management, or already trusted by residents. Enginet+'s legacy brand and local office can help.
But the same directories show that other operators also have local names and contact points.
The national layer includes Beeline, MTS, Rostelecom, MegaFon-Yota and t2-related mobile or fixed substitutes. National operators can bundle mobile, television and home internet, discount acquisition, and absorb short-term local margin pressure. Address-comparison pages for Ivanteevka show packages from large brands in the same retail price zone that Enginet+ uses. That compresses Enginet+'s pricing power. A 500-ruble entry plan and 900-ruble gigabit plan look competitive, but they leave little room to pass through upstream or labour inflation if national operators hold headline prices down through bundles.
Enginet+'s counter to large operators has to be operational, not financial. It can sell local responsiveness, office proximity, familiar technicians, simpler issue escalation and niche services. Its public communications about a new website, app development, a new authorization system and dedicated emails for business and accounting show an attempt to modernize the customer interface. That is important because a local provider with poor digital self-service loses one of the few areas where a national operator can scale. Billing friction creates calls. Calls create labour cost. Labour cost erodes the small monthly contribution.
A modern personal account and mobile payment path can be a real margin lever if it reduces support load.
The company also competes with "good enough" mobile broadband and fixed wireless substitutes. Public routing data does not directly measure that threat, but the local provider pages show customers comparing connectivity by address and package. In a dense apartment environment, wired access should still beat mobile for stable throughput. In lower-density or price-sensitive segments, mobile bundles can prevent a local wired provider from recovering extension cost. Enginet+'s technical-feasibility language is therefore prudent. It should not chase every prospective customer.
The best customers are those attached to existing plant, with low installation friction and enough willingness to pay for reliability.
Competition also affects equipment policy. Enginet+ sells a Wi-Fi router and notes that customer equipment must support gigabit Ethernet for higher-speed plans. A customer who buys a poor router and then complains about speed can become an unprofitable support case. A provider that supplies or recommends equipment can improve service quality but ties up capital and assumes support responsibility. The 4,300-ruble router price provides a retail equipment reference, but not a margin. The deeper question is whether equipment policy reduces churn and calls.
In a small ISP, avoiding avoidable Wi-Fi tickets can be as important as negotiating a lower transit rate.
Regulation, licences and geopolitical operating risk
Enginet+ operates in a regulated Russian telecom environment, and the public offer names specific licences for data transmission, telematic services and cable broadcasting. The documents page lists a broader set of licence categories, including local telephone service, channel services and data transmission categories. Licences are not a profit driver by themselves, but they are a right-to-operate asset. Losing or failing to renew a licence would impair the business quickly. Keeping multiple licences current also carries compliance and administrative cost, which is material for a small operator.
The court record involving the Ministry of Digital Development, Communications and Mass Media is small in absolute value but meaningful as a signal. The Garant record for case A41-115550/2024 describes a claim against LLC Enginet+ for mandatory contribution arrears and penalties, including a principal amount of 102,317.60 rubles and penalties around 75,013.11 rubles in the passage reviewed. Against a mid-teens-million revenue base, that is not existential. But it shows that even small regulatory levies can become formal disputes and consume management attention.
It also illustrates the disadvantage of scale: national operators can spread compliance teams over billions of rubles of revenue; a micro-operator must handle the same regime with far fewer people.
Geopolitical risk is indirect but real. Russian telecom operators face equipment availability, software supply, sanctions-related procurement friction, domestic regulatory controls, content and traffic obligations, currency movements for imported equipment, and changes in payment systems. The public materials do not show Enginet+'s supplier contracts or equipment brands beyond retail customer routers, so the impact cannot be quantified. Still, access networks need replacement parts, optics, switches, power supplies and software updates. A small operator with low free cash flow may defer renewal longer than is healthy.
That can preserve short-term cash while increasing future outage risk.
The public offer gives the operator some legal protection during outages, maintenance and third-party power failures. It does not protect the brand if outages are frequent. Local ISPs live or die by trust. If customers believe the operator responds quickly, they tolerate the occasional limitation of a small network. If not, they churn to a bundle even when the alternative is less personal. That is why the current website's emphasis on updated branding, support contacts and future app functionality is economically relevant. It is not just marketing; it is a retention-cost programme.
What would change the judgment
The positive case would strengthen first with verified active subscriber count and churn. If Enginet+ has, for example, dense apartment-building clusters with stable multi-year retention, the tariff ladder can support a durable local access business despite small absolute revenue. If churn is high or if new customers require frequent custom installation, the same revenue level becomes fragile. The second needed fact is gross margin after upstream and network operating costs. A 700-ruble plan is attractive only if transit, support and capex reserve leave real contribution.
The third is capex age: when were access switches, fibre segments, core routers, billing systems and power backup last refreshed? Old assets can make current margins look better than sustainable margins.
The fourth fact is revenue mix. A strong mix would show recurring business and municipal services using existing network assets without excessive concentration. A weak mix would show one-off projects and a declining residential base. The fifth is supplier terms. Enginet+'s upstream dependence is manageable if it has stable pricing, committed capacity and workable failover. It is dangerous if one supplier relationship is functionally dominant or if a local competitor controls critical paths. The sixth is building-access rights.
In local broadband, the right to enter and maintain building infrastructure can be more valuable than another marketing campaign.
The judgment would worsen if the 2024 or 2025 reported losses are confirmed as recurring operating losses rather than one-off accounting or transition effects. It would also worsen if staff reductions have left the operator unable to maintain support quality, if ownership changes were accompanied by customer attrition, or if licence renewals and regulatory contributions have become recurring strain. A small unpaid levy is not itself a major problem; repeated regulatory friction would be. The judgment would also worsen if the IPv6 allocation remains unused because of operational limits rather than customer irrelevance.
IPv6 is not yet the retail differentiator in many local access markets, but lack of deployment can signal technical stagnation.
The practical operating test is therefore a queue discipline test. Enginet+ should know which buildings and streets are profitable before accepting the next connection request, because every new address can be either a contribution asset or a future support liability. A building with existing fibre, working switches, low fault history and several customers nearby is worth a discounted tariff if the discount protects density. A distant single customer who wants a high-speed plan, custom cabling or unusual addressing can be a poor trade even at the 900-ruble headline plan.
The public offer gives the company the right to refuse where there is no technical possibility; the economic version of the same rule is stricter. It should refuse or reprice work where technical possibility exists but expected contribution after field labour and capex reserve is weak.
That discipline also applies to non-residential opportunities. A municipal camera contract, small-office link or channel-service job can be valuable when it uses existing plant and creates recurring maintenance revenue. It can damage the access business when it forces bespoke service levels, capital outlay or payment timing that the ordinary subscriber base cannot subsidize. The best fact that would change the view is not simply a larger revenue number.
It is a schedule showing that the largest customers share infrastructure with profitable residential clusters, renew without unusual concessions, and do not require support intensity that crowds out the household base. In a local ISP, the wrong large customer can be more dangerous than many small ones.
Elias Ward's final judgment is conditional but not evasive. LLC Enginet+ has enough public evidence to be treated as a real local ISP with real network resources, a specific Ivanteevka footprint, prepaid customer economics, multiple service lines and some public-sector/business signals. It does not have enough public evidence to be treated as a scalable platform without deeper diligence. The company must keep local access contribution ahead of fixed network cost.
That means selling dense, low-support ports; using higher-speed plans only where the access plant can carry them cheaply; keeping supplier options credible; converting support and billing modernization into lower labour cost; and treating municipal or business projects as contribution enhancers rather than replacements for recurring density. If those conditions hold, the small scale is a discipline. If they fail, the same small scale leaves too little margin for churn, capex delay and supplier pressure.
Sources
- https://inji.online/
- https://inji.online/tarify
- https://inji.online/oferta
- https://inji.online/documents
- https://inji.online/privacy
- https://inji.online/news
- https://inji.online/faq
- https://inji.online/payments
- https://hypestat.com/info/engplus.ru
- https://www.ripe.net/membership/member-support/list-of-members/ru/engplus/
- https://apps.db.ripe.net/db-web-ui/lookup?source=ripe&key=AS61380&type=aut-num
- https://apps.db.ripe.net/db-web-ui/lookup?source=ripe&key=ORG-CE14-RIPE&type=organisation
- https://apps.db.ripe.net/db-web-ui/query?searchtext=185.8.156.0%2F22&source=RIPE
- https://www-public.telecom-sudparis.eu/~maigron/rir-stats/ripe-allocations/allocations/ru-ip-allocations.html
- https://bgp.tools/as/61380
- https://ipinfo.io/AS61380
- https://whois.ipip.net/AS61380
- https://www.iplocate.io/AS61380
- https://ipinfo.io/185.8.156.210
- https://2ip.ru/ip/185.8.159.213/
- https://www.speedguide.net/ip/185.8.157.110
- https://www.cidr-report.org/cgi-bin/as-report?as=AS61380&view=2.0
- https://www.bigdatacloud.com/asn-lookup/AS61380
- https://bgp.he.net/country/RU
- https://bgp.tools/as/48149
- https://ipinfo.io/AS48149
- https://whoisfreaks.com/tools/asn-whois/lookup/as48149
- https://www.bigdatacloud.com/asn-lookup/AS48149
- https://www.cidr-report.org/cgi-bin/as-report?as=AS48149&view=2.0
- https://www.ipxo.com/asn/AS48149/
- https://bgp.he.net/AS48347
- https://ipinfo.io/AS48347
- https://bgp.tools/as/48347
- https://stat.ripe.net/AS48347
- https://companies.rbc.ru/id/1185050002774-ooo-inzhinet/
- https://b2b.house/company/OOO-INZHINET_72197bd4-3c52-43ee-a706-e8068986aa18/
- https://b2b.house/company/OOO-INZHINET_72197bd4-3c52-43ee-a706-e8068986aa18/financial-statements/
- https://www.prima-inform.ru/cat/cc/inzhinet-1185050002774-5038133016
- https://spark-interfax.ru/moskovskaya-oblast-pushkino/ooo-inzhinet-inn-5038133016-ogrn-1185050002774-fc71a18656e243109cbcd0b950cb368c
- https://nexxa.ru/company/1185050002774-ooo-inzhinet
- https://base.garant.ru/66501904/
- https://poisktenderov.ru/item/0848600003322000643/
- https://www.rusprofile.ru/date/2018-04-03
- https://www.newanteevka.ru/business/branch/internet
- https://provayder.net/ivanteevka/
- https://otsiv.ru/firm/ivanteevka/internet_svyaz_informatsionnye_tekhnologii/internet_provaydery/
- https://ivanteevka.jsprav.ru/internet-provajderyi/
- https://www.orgpage.ru/ivanteevka/internet/
- https://ivanteevka.justconnect.ru/home/%D1%83%D0%BB%20%20%D0%9F%D1%80%D0%BE%D0%BB%D0%B5%D1%82%D0%B0%D1%80%D1%81%D0%BA%D0%B0%D1%8F%20id319524-2/
- https://ivanteevka.justconnect.ru/home/%D1%83%D0%BB.%203-%D0%B9%20%D0%9F%D1%8F%D1%82%D0%B8%D0%BB%D0%B5%D1%82%D0%BA%D0%B8%20id319466-37/
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance