
Summary
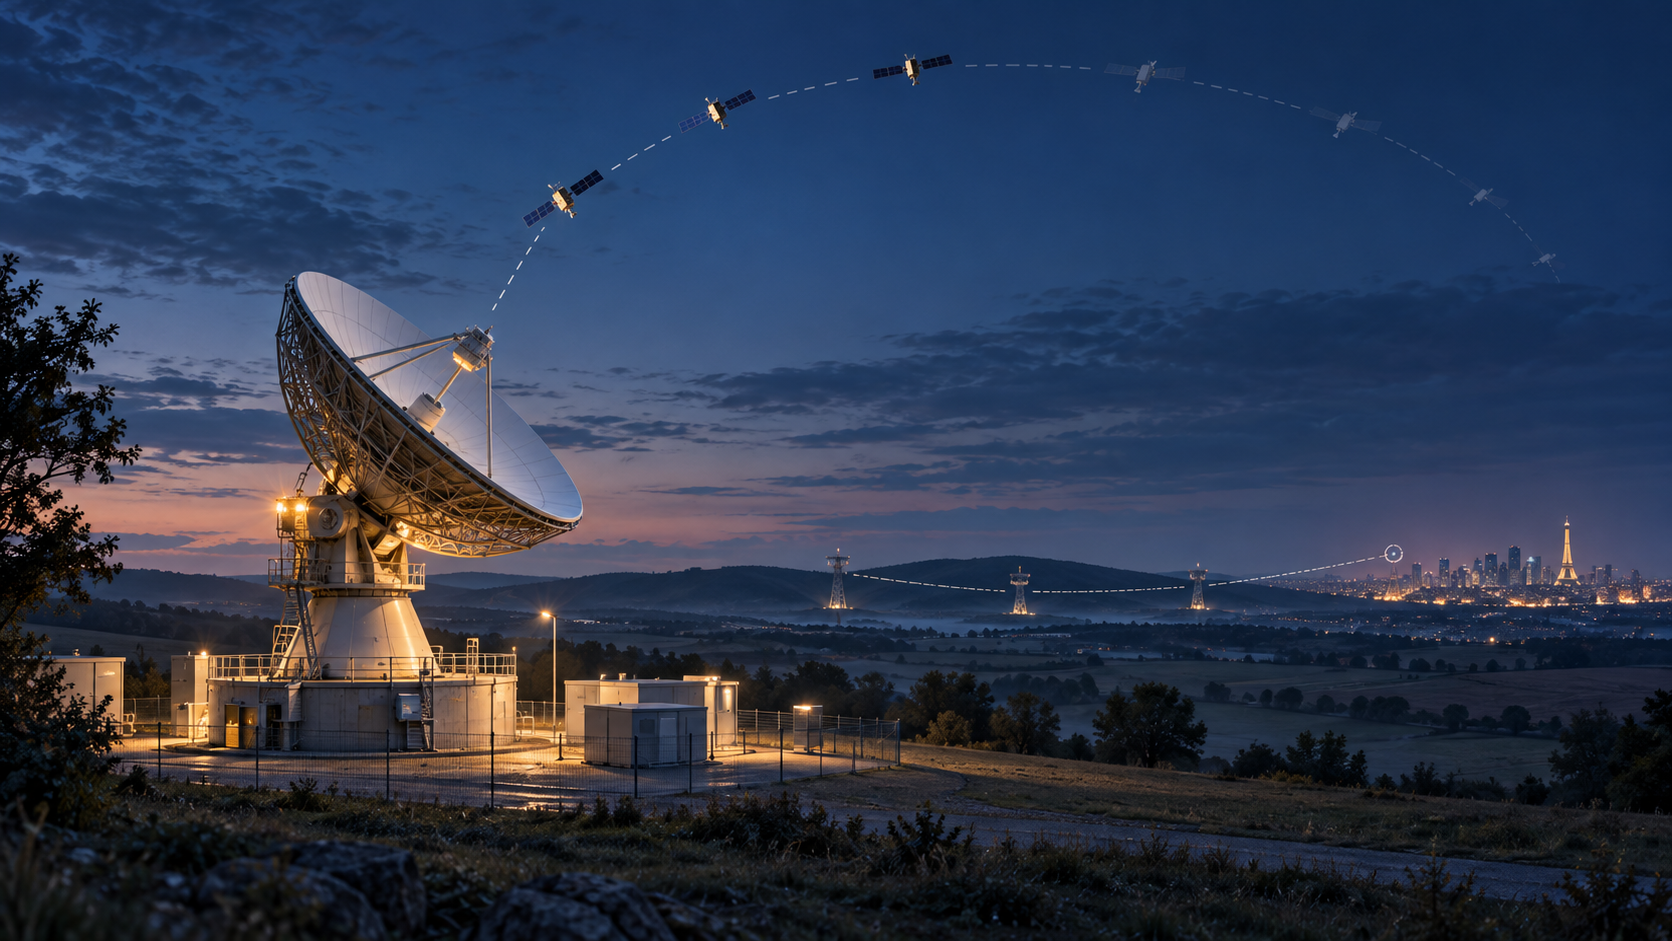
- Orange and Telesat say Europe’s first Telesat Lightspeed gateway is installed and commissioned at Bercenay-en-Othe. The announcement converts part of their March 2025 agreement from a promise into a physical ground-segment asset.
- The same release still describes the Paris point of presence as planned and the initial 225-satellite constellation as planned. Telesat continues to anticipate global service around the end of the first quarter of 2028.
- No public result shows an in-orbit satellite-to-gateway loop, end-to-end latency or availability, live customer traffic, commercially available capacity, pricing or Lightspeed revenue. “Commissioned” should therefore be read as a bounded infrastructure receipt, not as a synonym for operational service.
- The next evidence should arrive as a sequence: production satellites and launches, spectrum and market access, Paris PoP and backbone readiness, integrated acceptance measurements, customer activation, SLA performance and recognised revenue.
There is now something at Bercenay-en-Othe that was not there when Orange and Telesat announced their partnership in March 2025: a completed Lightspeed gateway that the companies call installed and commissioned. The distinction matters. An agreement can be delayed, redesigned or cancelled without ever becoming steel, electronics, antennas and an operating procedure. A commissioned site has consumed capital, supplier work and engineering attention. It removes one uncertainty from the terrestrial side of the programme.
But the gateway is not the network.
The 17 September announcement says the site uses Intellian antennas and will support the planned initial constellation of 225 low-Earth-orbit satellites. Orange is to provide ground connectivity from Bercenay to a planned Telesat point of presence in Paris. Telesat says the terrestrial build-out is proceeding ahead of an anticipated global entry into service in the first quarter of 2028.
Those verbs establish the boundary. The gateway “is installed and commissioned”. The constellation remains “planned”. Connectivity “will” be provided to a PoP that is itself “planned”. Global service is “anticipated”. The release does not say that customer packets have crossed an in-orbit Lightspeed satellite, landed at Bercenay, traversed Orange’s backbone and reached the Paris PoP under a measured service level.
That is not a defect in the announcement. It is the programme’s current sequence. Ground infrastructure can be finished before the production constellation is ready. The analytical error would be to compress several different readiness states into one celebratory word.
What changed since the original agreement
The March 2025 Orange–Telesat partnership announcement already contained most of the commercial architecture. Orange would host a Lightspeed landing station at Bercenay. Orange Business would use international private-line connectivity to connect it to a Telesat PoP in Paris. Orange also committed to Lightspeed capacity for enterprise and government customers.
Capacity commitments and hosting agreements are useful demand and execution signals. They do not show that capacity exists. The September 2026 release is stronger because it supplies a physical receipt: the gateway has crossed installation and commissioning. It narrows the execution gap between contract and infrastructure.
The word “commissioned”, however, needs a scope. Commissioning can mean that power, antenna mechanics, RF equipment, local networking, monitoring, safety and site interfaces have passed the tests available at that stage. It can also include wider integration. The public release does not publish an acceptance protocol or result, so readers cannot infer which layers were exercised. In particular, it does not report an in-orbit test over a production Lightspeed satellite or an end-to-end enterprise circuit.
Bercenay is a credible place to build the ground segment. Orange says the teleport obtained the World Teleport Association’s highest, Tier 4, certification after an audit covering more than 170 criteria. That certification supports the host site’s resilience, security and operating discipline. It does not certify Telesat’s future constellation, the Paris path or a customer SLA. Facility assurance and service assurance are related, but they are not interchangeable.
The sky segment still sets the clock
The September release describes a gateway for an initial 225-satellite constellation. That number reflects a material change in programme scale. In August, Telesat announced a C$2.3 billion Canadian Arctic military satellite-communications contract and said 69 fully funded additional satellites would expand the Lightspeed fleet from 156 to 225. Options could take the contract’s value to C$2.7 billion. The announcement said service would begin in 2028 and identified separate integration work for terminals, ground systems, network control, training and support.
That contract strengthens the programme’s funded demand and enlarges its planned capacity. It does not move 69 satellites into orbit. Nor does it turn milestone payments into service revenue. Contract value, backlog, capital funding and recognised operating revenue belong in separate ledgers.
Telesat’s second-quarter release kept the target around the end of the first quarter of 2028. It reported C$165 million of Lightspeed capital investment in the quarter and C$337 million in the first half, with C$1.3 billion to C$1.5 billion forecast for 2026. It also listed the risks that remain familiar in a constellation build: satellite and launch delay or failure, impaired performance, deployment timing, financing conditions, technology and supply-chain execution, competition, spectrum and market access, and the ability to operate and commercialise the service.
The production sequence makes the order especially visible. In March 2026, Telesat said the first two production satellites were planned for December 2026, followed by high-cadence production and launches in 2027. The Bercenay commissioning therefore precedes the planned production constellation. It is infrastructure built in anticipation of traffic, not proof that traffic already exists.
A gateway, a PoP and a service are different assets
The physical chain can be stated without marketing shorthand. A user terminal must see an available satellite. The satellite must have the intended capacity and routing state. Traffic may travel over optical inter-satellite links before reaching a gateway. The gateway must receive it and hand it to terrestrial transport. Orange’s path must deliver it to the Paris PoP. Telesat’s network and customer interconnection must then carry it to the promised destination. Monitoring, operations and commercial systems have to make the path supportable and billable.
Every transition has its own acceptance evidence.
For the satellite layer, useful receipts include production completions, launch manifests, successful deployment, orbit raising, payload checkout and fleet availability. For the regulatory layer, they include spectrum coordination and authority to serve the target market. For Bercenay and Paris, they include completed transport, resilient routes, PoP readiness and failover tests. For the integrated network, they include measured latency, packet loss, jitter, availability and recovery behaviour under stated conditions.
For the commercial layer, they include activated customers, accepted circuits, enforceable SLAs, delivered capacity and revenue recognised from the service.
The September release does not provide those later receipts. It should not be criticised for omitting figures that the programme may not yet be able to produce. It should be read precisely for what it does provide: evidence that one European gateway has moved from planned hosting to commissioned ground infrastructure.
Sources
- Orange and Telesat gateway announcement, 17 September 2026
- Orange and Telesat partnership announcement, 11 March 2025
- Telesat Arctic military satcom contract and constellation expansion, 4 August 2026
- Telesat second-quarter 2026 results
- Telesat second-quarter 2026 quarterly report
- Telesat 2025 results and production schedule, 17 March 2026
- Orange on Bercenay’s WTA Tier 4 certification
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance