
Summary
- Samsung’s six participating companies announced a combined US$1bn commitment to Helix; Samsung Electronics accounts for US$500m and the other five affiliates jointly account for the rest.
- KKR says the commitment runs through its long-duration capital fund and adds to more than US$10bn committed to the Helix strategy at launch. The public announcements do not disclose an ownership percentage, capital-call schedule, named customer contract or Samsung procurement award.
- KKR’s general disclosure says strategic investors may have priority or first-look rights to supply goods or services, but it does not say Samsung received a specific right. The investment is a potential route into an infrastructure platform, not a published order book.
A capital figure with three possible meanings
Helix and KKR announced Samsung’s commitment on September 28; Samsung published its own account the following day. The two releases answer different parts of the same question. KKR says the US$1bn commitment is made through its long-duration capital fund and builds on more than US$10bn already committed to the Helix strategy when it launched in June. Samsung names six participating companies: Samsung Electronics, Samsung C&T, Samsung SDS, Samsung SDI, Samsung Life Insurance and Samsung Fire & Marine Insurance. Samsung Electronics is assigned US$500m; the other five companies jointly make up the remaining US$500m.
The amount is therefore not one Samsung Electronics equipment budget. Nor is it a disclosed list of six operating contracts. It is a group-level capital commitment whose route, participants and strategic purpose are described at a high level. The releases do not break down the second US$500m among the five affiliates, state a percentage ownership interest, identify voting rights, or say when cash will be called or deployed.
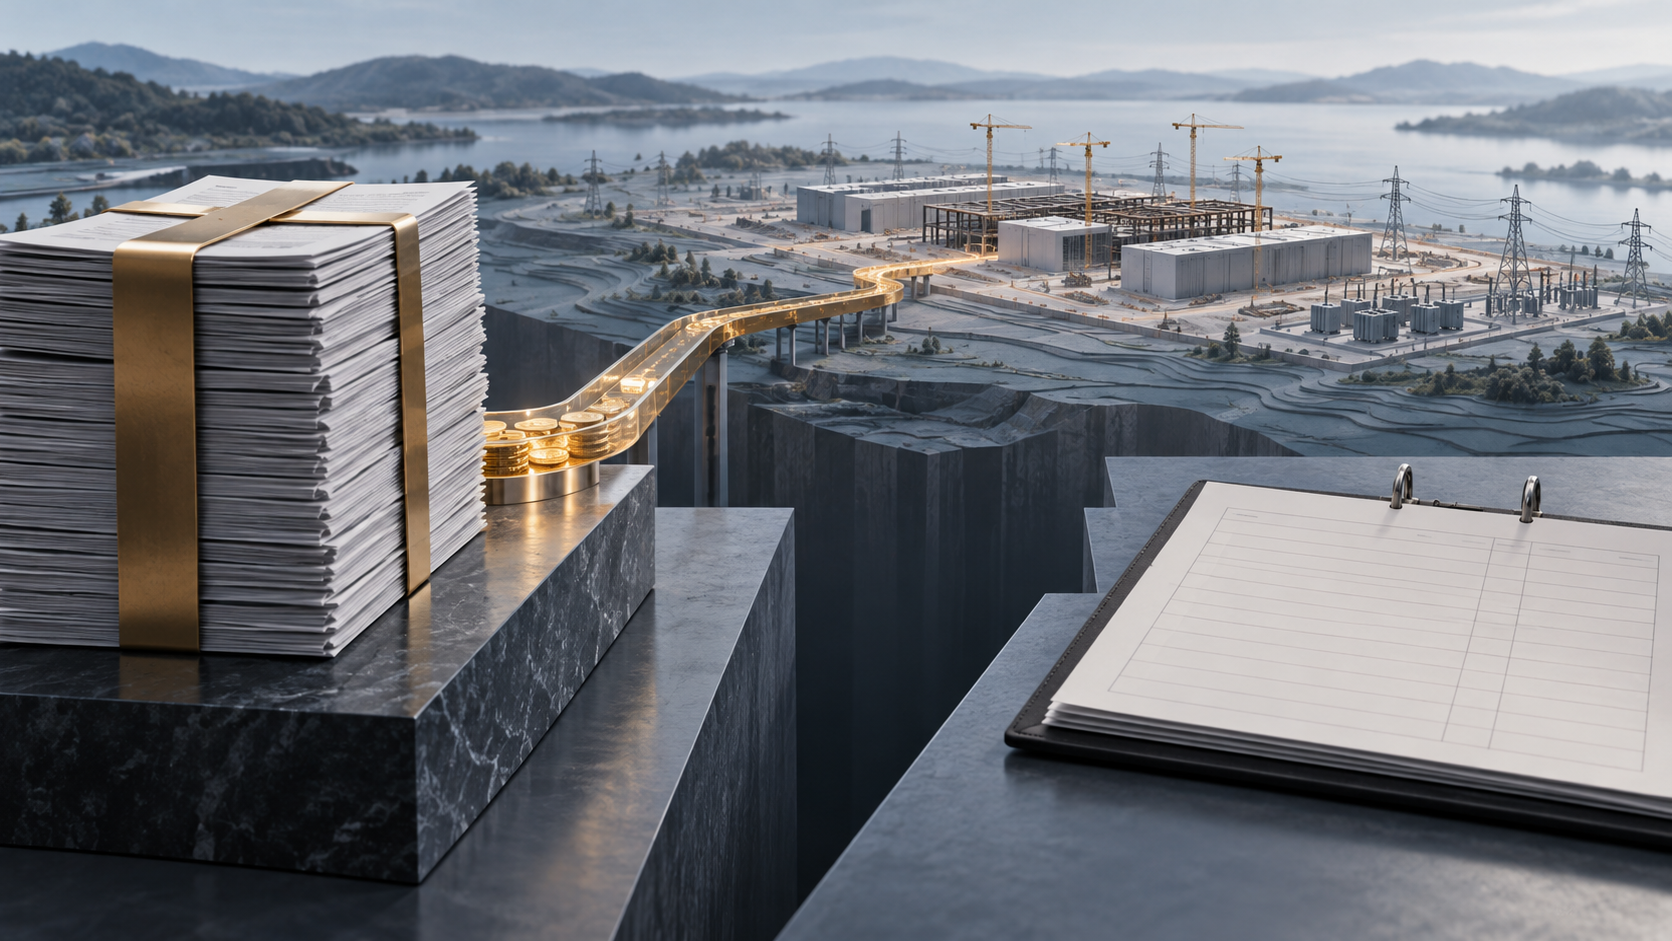
That distinction matters because the word “investment” can sit on several ledgers. On the capital ledger, Samsung is adding long-duration money to a platform designed to develop and manage AI-enabling infrastructure. On the commercial ledger, Samsung businesses could have capabilities that fit the platform: semiconductors, data-centre cooling, engineering and construction, data-centre operation, GPU services, batteries and backup power. On the customer ledger, hyperscalers would have to sign for capacity or services before a project produces contracted operating revenue.
The announcements disclose the first ledger and describe the second as a field for future cooperation. They do not publish the third.
The market should resist collapsing those ledgers into one. A supplier investing in a platform may have more reason to pursue its projects, and a platform may gain a route to equipment, expertise and financing. That is strategic optionality. It is not the same thing as a purchase order, an offtake agreement or revenue booked by an affiliate.
What Helix says it is building
At launch on June 11, KKR, the Kuwait Investment Authority, NVIDIA and Vistra introduced Helix as a single coordination point for hyperscalers’ data-centre, power and connectivity requirements. The launch announcement described more than US$10bn in long-duration capital commitments to the strategy. It named NVIDIA as a strategic partner for infrastructure aligned with its DSX AI-factory platform and Vistra as Helix’s preferred power provider. Helix said it would invest in and manage data-centre development and operations, generation, transmission and distribution, fibre and connectivity.
Samsung’s capabilities map onto several of those layers. The company says its electronics businesses can provide semiconductor and cooling expertise; Samsung C&T has EPC capabilities in data centres and power; Samsung SDS designs, builds and operates data centres and has moved into GPU-as-a-service; and Samsung SDI makes UPS and battery-backup systems. Samsung Life Insurance and Samsung Fire & Marine Insurance are among the five affiliates contributing to the second half of the commitment, though the announcements do not say how much each contributes or what operating role either insurer would have.
The industrial fit is credible as a description of capabilities. The financial question is whether those capabilities become contracted supply, at what price, on what schedule and with which customers. Samsung itself describes future collaboration and opportunities to explore. KKR likewise says Helix expects to explore ways to use Samsung’s capabilities across advanced technology, construction, energy storage and cooling. “Explore” is a plan to investigate a commercial path, not evidence that an award has been made.
The rights disclosure is an option, not a Samsung contract
One sentence in KKR’s release makes the investor-supplier relationship more interesting. KKR says KIA, NVIDIA, Samsung and Vistra participate in returns generated by Helix, and that those and other strategic partners may have certain rights—such as priority or first-look rights—to provide goods or services to Helix investments.
That language establishes a possible commercial feature of the platform’s investor model. It does not allocate a right to Samsung, describe how a first look would work, set prices, promise exclusivity, or assign minimum volumes. No Samsung-specific priority, purchase commitment, customer referral or supplier award is identified in either announcement. The distinction is important: an investor can benefit from the platform’s returns while an affiliated supplier may separately compete for work, but the two sources of value are not the same cash flow.
If a Samsung affiliate eventually supplies cooling equipment, batteries, construction or compute services, the relevant evidence will be a named project, an executed supply agreement, a price and volume, and recognition in the affiliate’s reported results. If Samsung’s investment instead remains a financial position, its return will depend on Helix’s performance and the terms of the investment. Today’s releases do not let an outside reader choose between those paths or value either one.
The proof has to move from platform to project
Helix’s model is aimed at a real coordination problem: AI infrastructure depends on land, data-centre construction, grid access, power generation, cooling, networks and large customers arriving on compatible timelines. Pooling capital and partners may reduce the number of counterparties a hyperscaler must coordinate. The platform can still fail to turn that simplification into useful capacity if a site lacks power, transmission, permits, fibre, equipment or a customer willing to sign.
The first useful proof will not be another list of ecosystem participants. It will be project-level disclosure: where a facility is being developed; its committed power and interconnection path; the planned IT load and delivery phases; which customer has signed; what capacity is contracted; and how much capital is funded rather than merely committed. The next proof is the supply chain: whether Samsung companies or other strategic partners receive actual awards, on disclosed terms, and whether those awards generate external revenue rather than only a strategic announcement.
The figure “more than US$10bn” at launch and Samsung’s later US$1bn commitment describe capital available to a strategy, not completed construction. KKR’s wording says the new commitment builds on the earlier base, but the releases do not provide a current total, paid-in balance, project allocation or deployment rate. Adding the headline amounts into a precise current funding total would imply more than the sources disclose.
The relevant test for investors is therefore conversion, not scale alone. A commitment can lower financing risk and improve the odds that a platform can pursue projects. It cannot by itself prove customer demand, power availability or positive returns. Those require separate evidence.
Sources
- KKR and Helix: Samsung commits $1bn, September 28, 2026
- Samsung Global Newsroom: US$1bn investment, September 29, 2026
- Helix: KKR launches the platform, June 11, 2026
- Samsung SDS: six-company investment announcement, September 30, 2026
- The Korea Times: transaction and cooperation details, September 29, 2026
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance