
Summary
- JOINT-STOCK COMPANY "MOSCOW ENERGY COMMUNICATION NODE", known in Russian public records as AO MUS Energetiki and historically tied to the EESTelecom name, is not best read as an ordinary consumer ISP. Its public economics begin with the communications needs of the electricity system: fibre on energy infrastructure, technological communications, regional maintenance crews, licensed data and telephone services, and the operating discipline needed when a failed communications path can become a grid-continuity problem. The Chitatehenergo merger completed at the end of 2025 also means some network records still carry older Chita-facing names while the legal successor is the Moscow company.
- The company has real scale but modest economics. Public 2025 accounts show roughly 1.603 billion roubles of revenue and 69 million roubles of net profit, with assets of about 1.57 billion roubles and equity above 1.12 billion roubles. Public employee counts range from 337 to 366. That means revenue per employee is a few million roubles a year, but net profit per employee is below a quarter-million roubles. This is a maintenance, field-operations and infrastructure-return profile, not a software-margin profile.
- The explicit judgment is conditional. Moscow Energy Communication Node can be valuable if utility corridors, energy-sector trust, field crews, licenses, AS58067, AS56702 and spare fibre let it sell external capacity, transit, channels and technical services without compromising the grid's own communications. It becomes weak if almost all revenue is transfer-priced captive work, if renewal capital rises faster than contract prices, or if outside telecom sales consume the same crews and restoration capacity needed for the captive mission.
Start with the captive kilometre
Begin with one kilometre of network built for energy operations. It may run on or near a high-voltage right of way. It may have been justified by dispatch, telemetry, protection, operational voice, local-site data and the need to keep substations, control rooms and field teams visible to one another. Its first purpose is not to beat a consumer broadband price. Its first purpose is continuity.
That purpose changes the economics. A retail carrier asks whether a route can earn enough subscribers, wholesale buyers or enterprise circuits to justify construction and maintenance. A power-sector communications operator asks a harsher prior question: what is the cost of a missing or failed communications path when the electricity system needs it? Once that path exists, spare fibre, node space, IP resources and regional know-how may be sold to outsiders. But the asset cannot be managed as though external revenue is the only test.
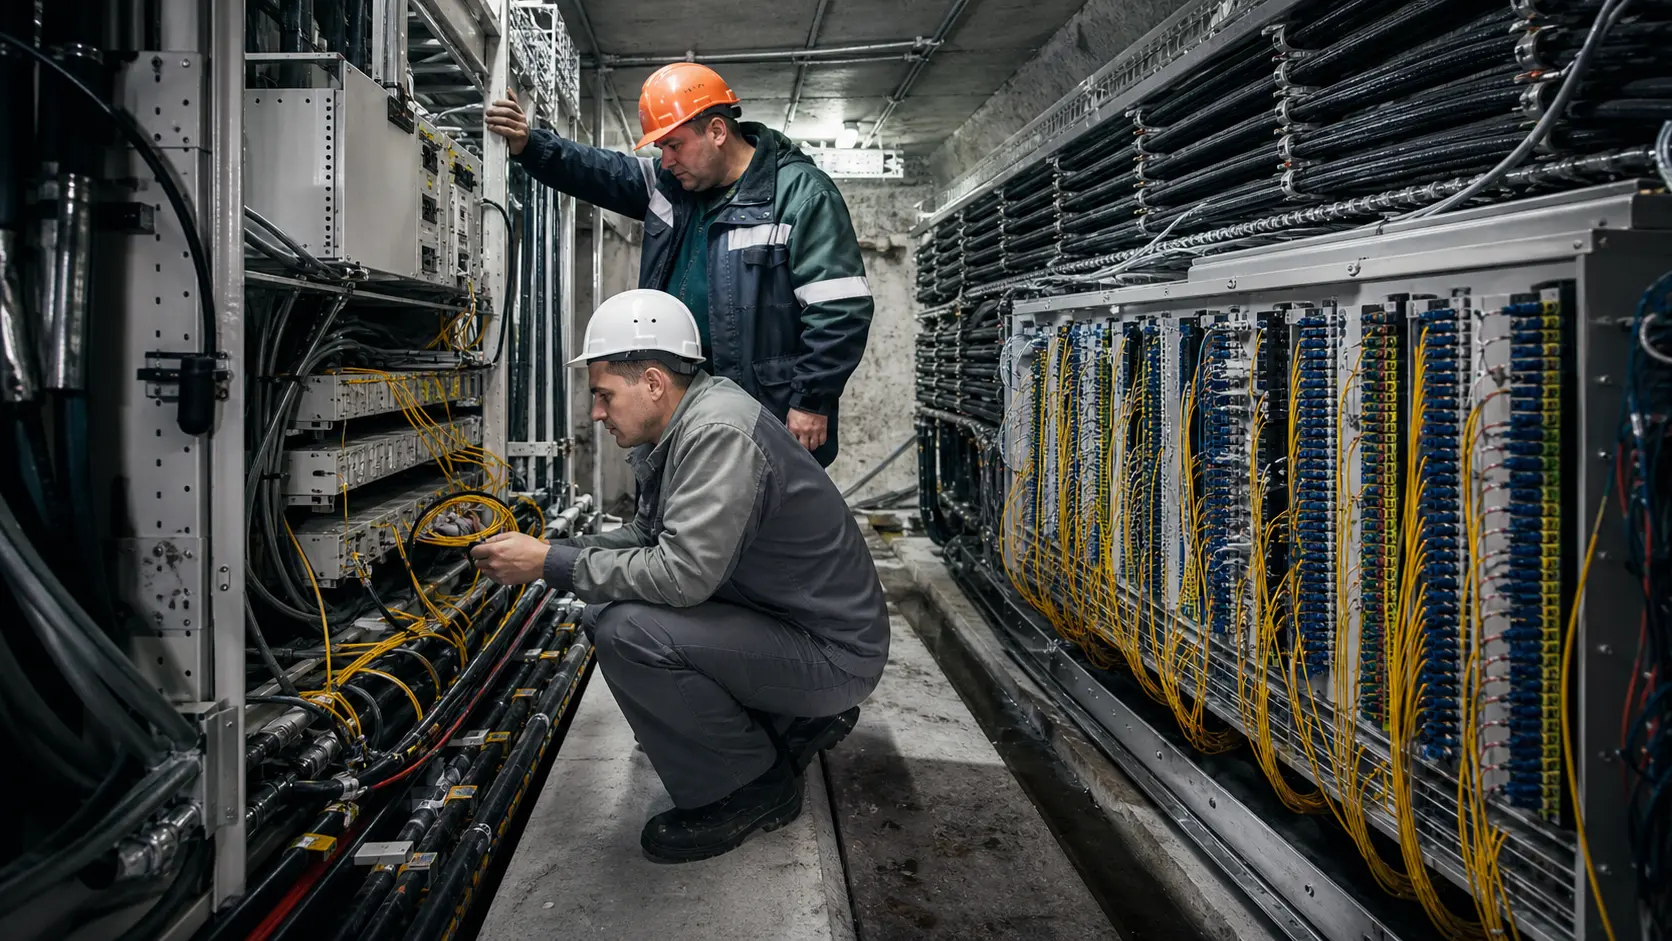
Moscow Energy Communication Node sits exactly in that tension. Its public record says "regional ISP", but that label is too thin. The company is a communications operator attached to the electricity infrastructure economy. It has ASNs, RIPE records, peering information, external carrier relationships and licenses. It also has job postings for repair crews, electrical-safety requirements, long business trips, equipment measurement, emergency stock control and work on fibre-optic lines carried on overhead power lines. Those are not the signals of a pure desk-based transit reseller.
The value proposition is easy to state and difficult to price. A utility-linked network can have routes where normal telecom builds are expensive, slow or not worth the demand density. It can reach industrial and regional locations because the energy network already had to reach them. It can support power-sector customers that care more about dependability than the lowest monthly circuit quote. It can sometimes sell spare capacity to carriers whose own economics improve when they do not have to build the full route themselves.
The danger is just as clear. The more the company sells external telecom capacity, the more it must separate spare-capacity economics from mission-critical capacity. A carrier customer wants bandwidth, uptime and a price. The grid needs restoration priority, operational security and maintenance windows that follow energy-system risk, not only telecom contract convenience. If the same fibres, nodes, engineers and vehicles serve both purposes, management discipline matters more than the headline route map.
That is why the central question is not whether Moscow Energy Communication Node has fibre. The public evidence says it has a meaningful communications footprint. The question is whether every spare channel sold outside the captive system carries enough margin to pay for maintenance, resilience and renewal capital while preserving the captive service level. If not, external sales become a distraction dressed up as monetisation.
The legal entity changed less than the operating problem
The public company identity is unusually easy to confuse because the network surface still carries older names. Russian registry and contractor profiles identify the current legal entity as AO MUS Energetiki, the Russian name corresponding to JOINT-STOCK COMPANY "MOSCOW ENERGY COMMUNICATION NODE", with INN 7705039240 and OGRN 1027739290897. The current address in multiple public profiles is Belovezhskaya Street in Moscow. Older disclosure pages show an Akademika Chelomeya address. Those older details are useful corporate history, not the current operating address.
The Chitatehenergo transition is more important. The old Chitatehenergo web page states that AO Chitatehenergo ceased activity on December 30, 2025 through merger into AO MUS Energetiki, and that AO MUS Energetiki succeeded to all rights and obligations. That fact explains a great deal of the apparent mess in the public network layer. AS58067 appears with the ASCHITATEH name and Chitatehenergo labels in several routing databases. PeeringDB still presents JSC Chitatehenergo. Some route objects date back to 2012. But RIPE's registrant record now points to the Moscow legal entity.
That should not be read as a scandal. Network records often lag legal reorganisations, especially when old maintainers, old route objects and old abuse contacts remain operationally useful. It should, however, be read as a management task. A utility communications operator cannot afford indefinite ambiguity between legacy and successor names. Counterparties need to know who signs contracts, who receives abuse reports, who owns restoration obligations, who holds licenses and who controls route policy.
The legal perimeter matters because the business is not only selling bandwidth. It is carrying rights and obligations accumulated over decades of energy communications. The public history reaches back to a company profile claim of a 1945 origin, with the EESTelecom brand used from 2001 and a mission of providing reliable communications to electricity-sector enterprises. Whether every part of that profile can be audited from public material is less important than the broad point: this is not a start-up fibre operator trying to discover a market.
It is an inherited industrial communications function trying to make its asset base economically useful in a changed telecom environment.
Rosseti Digital's management role sharpens the point. Public contractor profiles list Rosseti Digital as the managing organisation, and industry coverage describes the consolidation of Rosseti telecom, information-technology and security assets under Rosseti Digital. That gives Moscow Energy Communication Node an institutional home. It also reduces the chance that the company will behave like an independent carrier optimising only for external margin. The group logic is captive first: make the electricity system's information and communications infrastructure work.
That captive status is both a strength and a ceiling. It gives the company anchor demand, operational legitimacy and access to a network of power-sector relationships. It also means outside investors, suppliers and customers must ask whether transfer prices, group priorities and internal procurement rules are doing more work than open-market competitiveness.
The business model is trusted operations, not anonymous bandwidth
The best public description of the model is not a marketing slogan. It is the bundle of tasks in tenders, job postings and network records: operational and technical maintenance of fibre-optic communications networks, data networks, communications equipment, power systems for communications equipment, local-area-network equipment, line-cable facilities, dispatch and technological communications, and capital work on communications objects.
That bundle is expensive because it is physical. Someone must inspect equipment. Someone must test signal parameters. Someone must keep measurement devices working. Someone must replenish emergency spares. Someone must travel to regional sites. Someone must understand both telecom practice and electrical-safety rules. One job listing for the Novosibirsk maintenance group describes work across 25 objects in Novosibirsk region and Altai Krai, including installation, adjustment, testing, measurement, preventive maintenance, emergency stock control, monitoring, construction and reconstruction control, commissioning and long business trips.
Another listing refers to fibre-optic lines on overhead power lines from 0.4 to 220 kV. That is field economics.
The business is therefore not just "connect customer A to customer B". It is "own the operating boundary where communications, energy assets, safety permits, field access, emergency restoration and technical documentation meet". That boundary can be valuable because many ordinary telecom providers would rather sell capacity on clean routes than dispatch crews into the operational rhythm of power assets.
ComNews' 2020 report on FSK EES' communications maintenance tender is a useful scale marker. The report described a tender for managing and technically maintaining the unified technological communications network, fibre-optic network, data network, power systems and LAN equipment of FSK EES. It said the then-current work was handled by MUS Energetiki and covered about 7,100 equipment units. The bid and performance guarantee numbers imply a contract value around 2.973 billion roubles including VAT. That is not current revenue by itself, but it reveals the size and type of work the company was trusted to perform.
That work is not glamorous. It is better. In infrastructure economics, unglamorous recurring work can be more valuable than exciting one-off construction if the contract allocates costs properly. A network-management and technical-maintenance contract can support predictable staffing, vehicles, regional stores and tools. It can also become a margin trap if the operator absorbs more restoration labour, parts replacement, security work or documentation burden than the price recognises.
The external-market story sits beside that captive contract base. The strongest public example is the MTS and FSK fibre project from Tynda through Neryungri and Nizhny Kuranakh to Mirny. Interfax reported that the project raised MTS' capacity toward Mirny to 10 Gbit/s where access had previously relied on satellite channels of roughly 200 Mbit/s. That is the spare-capacity thesis made concrete. Energy infrastructure produced a route with high value for a mobile operator and its customers.
But one good example does not prove a broad merchant business. It proves that the asset can matter when geography and existing rights of way make ordinary carrier construction unattractive. The company still needs repeatable external demand, contract discipline and enough restoration capacity to protect the captive system.
The accounts show scale, but not comfort
The public accounts put a floor under the analysis. RBC lists 2025 revenue of about 1.603 billion roubles, net profit of 69.010 million roubles, total assets of about 1.570 billion roubles, liabilities of 447.176 million roubles and equity of 1.123 billion roubles. It lists 337 average employees. Companium gives 366 employees for 2025, with similar revenue and profit, and also lists fixed assets of 515.6 million roubles and intangible assets of 31.4 million roubles. These profiles are not audited notes, but they are consistent enough for economic stress testing.
At 337 employees, revenue per average employee is roughly 4.76 million roubles a year. At 366 employees, it is roughly 4.38 million. Net profit per employee is only about 205,000 roubles on the lower employee count and about 188,000 roubles on the higher one. The net margin is about 4.3%. Return on assets is roughly 4.4%. Return on equity is roughly 6.1%.
Those are not bad numbers for a field-heavy utility services company. They are not strong enough to be careless. A few points of wage inflation, vehicle cost, imported-equipment cost, contract underpricing, SLA penalties or delayed receivables can take much of the margin. A company can have strategic assets and still earn ordinary returns if customers have bargaining power and maintenance costs are real.
This is why the company should not be valued as though every kilometre of utility fibre automatically becomes high-margin wholesale revenue. Some fibre exists because the grid needs it. Some equipment exists because technical operation demands redundancy. Some labour exists because the customer is sensitive, geographically dispersed and not easily served from a central desk. Those assets create optionality, but they also carry fixed obligations.
The labour and benefits surface confirms that this is not a light operating model. Public job listings show salaries from about 60,000 roubles for a regional specialist role to more than 100,000 roubles for Moscow and Far East technical roles, with white employment, training and extended voluntary medical insurance referenced in postings. A 2026 voluntary medical insurance procurement for employees had an initial maximum price of 84.224 million roubles. Against 337 employees, that is about 250,000 roubles per employee; against 366 employees, about 230,000.
A procurement ceiling is not an actual cost, but it shows that the employee base is treated as a serious operating asset.
Companium lists taxes of 143.2 million roubles and insurance contributions of 200.3 million roubles for 2025. Again, the exact accounting base should not be overread, but the direction is clear. The cost structure includes payroll-linked obligations, field staff, regional offices, vehicle upkeep, spares, training and compliance. External capacity revenue is attractive only if it rides on this base without forcing equivalent incremental cost.
Capital discipline is the investment case
The company's assets are not free because they are old or utility-linked. Fibre on power infrastructure needs inspection, restoration, route documentation, spares, qualified labour, permissions and replacement planning. Communications equipment needs power, climate, software lifecycle management, configuration control, physical security and monitoring. Vehicles and regional sites need ordinary maintenance. A field organisation also needs slack. An emergency restoration service with no slack is only cheap until the emergency arrives.
Public procurement notices make this cost surface visible in small pieces. There are notices for vehicle maintenance in Samara and Saint Petersburg, oil and filter replacement, passenger-car supply, freon purchase, container rental for temporary storage in Perm, internet access in Surgut, a data channel in Yekaterinburg and voluntary medical insurance. None of these notices is individually strategic. Together they describe the nature of the operating machine: distributed people, tools, vehicles, sites, equipment rooms and ordinary service inputs.
The 2020 FSK EES tender described in ComNews is the larger version of the same point. A 1% bid guarantee and a 5% performance guarantee implied tens and then hundreds of millions of roubles tied up around one major service contract. That is capital discipline. A company with 69 million roubles of 2025 net profit cannot ignore working-capital terms, guarantee requirements or receivable timing. It may have a strong balance sheet by public profile, but a few large contracts can still define cash behaviour.
Capital discipline matters even more after the Chitatehenergo merger. The successor entity inherited rights and obligations from a regional communications operator with its own routes, people, ASNs and customers. If integration simply adds revenue and assets, the profile improves. If integration adds ageing equipment, regional lease obligations, duplicate systems, underpriced contracts or unfunded capex, the headline revenue gain can dilute the economics.
The article's judgment therefore turns less on whether Moscow Energy Communication Node can grow revenue and more on whether it can grow profitable, fundable revenue. Growth from underpriced captive work is a burden. Growth from spare fibre sold under clear service terms can be attractive. Growth from external customers that require expensive bespoke restoration, special route changes, regulatory paperwork or unplanned capex can be worse than no growth at all.
The evidence needed is simple: margin by service line, capex by route family, fault and restoration history, customer concentration, external revenue share, and contract terms for penalties and emergency priority. None of that is public in enough detail. The responsible reading is to call the company economically useful but not obviously under-monetised.
The network layer proves capability, not necessarily profit
The most visible technical evidence sits in AS58067 and AS56702. RIPE RDAP identifies the registrant organisation as JOINT-STOCK COMPANY "MOSCOW ENERGY COMMUNICATION NODE", with Moscow address and noc contact. AS58067 carries the legacy ASCHITATEH name, while AS56702 carries a Chitatechenergo label. That is the public network residue of the legal and operating history.
AS58067 is the larger public network. RIPEstat showed it announced on July 25, 2026. BGP.HE listed 19 originated prefixes, 18 IPv4 and one IPv6, 49 announced prefixes, 54 observed peers and no invalid RPKI originated routes in the checked view. RIPEstat's announced-prefix feed included the 176.114.16.0/20 family, several /24 views, 80.90.64.0/24, 185.214.76.0/22 and 2a0b:97c0::/29. RIPE RDAP confirms 176.114.16.0/20 as CHITATEH-NET, assigned PI and registered to the Moscow company; the IPv6 /29 is also registered to the same organisation.
But 185.214.76.0/22 is registered to Lanros LLC, so route origination and resource ownership must be kept separate.
AS56702 is smaller. IPinfo and IP2Location show 512 IPv4 addresses in the 91.226.222.0/23 range, with AS58067 as the upstream in the public view. RIPEstat shows the /23 and two /24 views announced. That looks like a sibling or regional network function rather than a separate strategic pillar.
PeeringDB adds a different signal. It self-reports AS58067 as JSC Chitatehenergo, network type NSP, 5-10 Gbps traffic, 16 IPv4 prefixes, open peering policy, contracts required, balanced traffic and public peering at BAIKAL-IX and GNM-IX. The profile's stale name is a warning not to treat every field as current. Its existence still matters. A network that maintains peering policy, AS-SET and IX presence is participating in the regional interconnection economy, not merely carrying private SCADA traffic behind a firewall.
CAIDA's AS Rank places AS58067 with a customer cone of 15 ASNs, 103 prefixes and AS degree 36. BGP databases show relationships with large carriers such as TransTeleCom, Rostelecom, Vimpelcom, MegaFon, ER-Telecom and international or regional networks, and they also show regional downstreams such as Svyaz-Energo, System Solutions, Mass-Net, Megalink and others in various public views. These are routing relationships, not contract terms. But they prove a public-network role.
The profit question remains unanswered. A network can be operationally meaningful and financially ordinary. Transit margins can be thin. Regional downstreams can be small. Some peering reduces cost rather than creates revenue. Some external routes may exist to support captive services. The right conclusion is measured: the network layer proves capability, interconnection and optionality; it does not prove that external wholesale revenue is large enough to re-rate the company.
Customers are the advantage and the concentration risk
The customer base is anchored in the electricity sector. That is the company's moat. It is also the company's concentration risk.
Companium's public profile lists top customer relationships with Rosseti far ahead of the rest: 28 contracts worth about 2.7 billion roubles, then much smaller entries for Inter RAO-Elektrogeneratsiya, RusHydro, Rostelecom and Rosseti Moscow Region. Seldon also points to frequent contracts with Rosseti. ComNews' industry reporting describes the company as a trusted operator for FSK EES and the electricity-sector communications system. Job postings repeatedly call it a daughter or dependent company within the Rosseti/FSK-Rosseti orbit.
That is an enviable position if the contract base is fairly priced. The power grid needs communications. The customer values continuity. The operator knows the sites, rules, equipment, people and history. Procurement frictions may be easier inside a known ecosystem. A third-party carrier may not want the safety, access and documentation burden of utility-line communications. That gives Moscow Energy Communication Node a role that cannot be easily replicated by a generic ISP.
The same facts reduce independent pricing power. If Rosseti-group procurement is the core market, the buyer knows the operator's cost base, knows the strategic need and can shape tenders. The operator may win because it is trusted and embedded, not because it can earn open-market margins. A captive operator can be secure but not rich.
External customers are therefore important not only for growth but for price discovery. If MTS, Rostelecom, regional carriers or enterprise customers pay market prices for routes, capacity, transit or field services, those deals reveal whether the company has assets that outsiders truly value. The MTS route toward Mirny is an important public example because it connects energy infrastructure to carrier demand in a geography where satellite backhaul had been a limiting alternative. That is real economic value.
But external concentration can also be dangerous. A few carrier customers may want low prices because the route is spare. They may not pay enough for restoration priority. They may require service levels that force overbuild, additional monitoring or field dispatch. If external revenue is treated as "found money" because the fibre already exists, the company can underprice the true cost of sharing an industrial route.
The best customer mix would have three layers: stable captive contracts priced to maintain resilience; external carrier or enterprise deals priced above incremental cost and with clear restoration hierarchy; and route or IP services that use existing network capability without consuming scarce field time. Public sources show the first layer clearly and the second layer partially. They do not yet prove the third at material scale.
Suppliers and technology lifecycle define the real downside
The supplier side is not a procurement footnote. It is where many utility-telecom margins are lost.
Public network evidence shows a dependency web with major telecom carriers. Some of those relationships are upstream, some peers and some observed routing neighbours. Rostelecom's own public material describes a massive backbone with 500,000 km of fibre-optic lines, over 350 access points, participation in international cable systems and relationships with thousands of operators. For Moscow Energy Communication Node, such carriers can be suppliers, alternatives, peers or customers depending on the route. The same is true, in different ways, for TransTeleCom, Vimpelcom, MegaFon, ER-Telecom and regional networks.
Procurement profiles show more mundane supplier dependencies: telecom service contractors, active telecom suppliers, power-supply-system firms, service firms, vehicle maintenance, insurance, freon, containers, data channels and internet access. A company running distributed communications equipment needs all of that. The margin is not only in bandwidth; it is in preventing all these inputs from becoming emergency cost.
Technology lifecycle is the sharper risk. Job advertisements mention CUCM, Cisco voice gateways and Cisco IP phones. That does not prove the full installed base, and it does not prove current vendor support terms. It does show that legacy western enterprise telecom equipment is part of the skill surface. In Russia's current sanctions and software-service environment, that matters. Restrictions on certain IT and software services to persons located in Russia can make support, updates, replacements and lifecycle planning harder for western-origin systems.
Even where equipment continues to work, the risk shifts to local engineers and local spares.
This can cut both ways. Local demand for a company like Moscow Energy Communication Node may rise because customers need support for systems whose original vendor ecosystem is harder to access. But the cost of providing that support also rises. Workarounds, spares, substitutes, documentation gaps, version freezes and migration projects can all consume engineer time. If the company is paid to manage this risk explicitly, it can be profitable. If it absorbs the risk inside ordinary maintenance contracts, margin leaks.
The same dynamic applies to domestic substitution. Rosseti Digital's broader strategy includes domestic IT and import-substitution logic. That may reduce geopolitical exposure over time. It can also create transition cost. Replacing communications equipment and management systems across power-sector sites is not just a procurement decision. It requires testing, training, documentation, compatibility work and acceptance procedures. The operator that must keep the old system running while introducing the new one carries the economic burden unless contract terms say otherwise.
That is the supplier question investors should ask: does Moscow Energy Communication Node get paid for lifecycle risk, or does it merely inherit it?
Alternatives are large, but not identical
Moscow Energy Communication Node does not compete in a vacuum. For generic connectivity, large carriers and exchange platforms impose price discipline. Rostelecom's backbone scale, TransTeleCom's rail-linked network history, MTS and MegaFon mobile/backbone needs, Vimpelcom, ER-Telecom, regional carriers, data-centre interconnects and IX options all offer substitutes for parts of the service bundle. MSK-IX advertises hundreds of participants, many locations, cloud access and route-server-based interconnection. Internet Society data show MSK-IX Moscow with substantial member capacity and route-server participation.
For a simple urban enterprise circuit, that market can be brutal. If the route is in Moscow or another dense city, a utility-linked operator has no automatic right to premium pricing. Buyers can compare offers. They can use multiple carriers, local access specialists, cloud interconnects or IX services. They can also demand service credits and route diversity.
The company's advantage appears where the alternative is not clean. A power-line route through difficult geography, a substation communication requirement, a regional maintenance obligation, a need for electrical-safety-qualified personnel, or a customer who values energy-sector familiarity changes the competitive set. The alternative is not merely "buy a circuit from a carrier". It may be "find someone who can work on this site, understand this network, follow the safety rules, document the change and be accountable during a fault".
The strongest external opportunities should therefore be selective. Sell routes where the utility corridor has a structural advantage. Sell technical services where energy-infrastructure knowledge matters. Sell transit or peering where the network already has regional customer relationships. Avoid commodity services where larger operators can outscale the company and force thin prices.
The same logic should govern partnership. The company does not need to become a national retail brand. It needs to be the operator that large carriers and industrial customers trust when a route or site touches energy infrastructure. That is a narrower ambition, but it is more profitable than chasing every broadband or hosting opportunity that an ASN technically permits.
Regulation and geopolitics raise the hurdle
The regulatory surface is unavoidable. Russian communications law governs network construction, operation and communications services. Public contractor profiles list multiple active communications licenses, though sources differ on whether the visible count is six, twelve or more when historical and registry categories are aggregated. The important point is not the count. The important point is that the company operates in licensed communications services, not only internal IT support.
Critical information infrastructure law matters because electricity and communications both sit near sensitive infrastructure. The article should not declare that any specific object is categorised unless that is proven. It is enough to say that a company maintaining communications for electricity-sector customers must operate as though compliance, security, documentation and restoration discipline are part of the economic product. A cheap network service that fails that standard is not cheap.
Personal data law also matters. A telecom operator and energy-sector service provider touches employee records, customer contacts, access data, support logs, phone systems, network records and possibly incident data. Compliance is not the main story, but it is another reason the customer does not want an anonymous low-cost contractor inside operational systems.
Geopolitics affects both revenue and cost. Russia's domestic infrastructure policy can favour local capability, captive industrial providers and domestic technology ecosystems. That helps a company embedded in Rosseti's digital and telecom structure. Western sanctions and software-service restrictions can also make direct foreign support less available, which increases the value of competent local support. But restrictions can raise the cost of equipment lifecycle management, replacement planning and software maintenance.
The correct economic conclusion is not that sanctions are simply good or bad for the company. They increase demand for local continuity and increase the cost of delivering continuity. The company benefits only if customers pay for the added risk.
There is also routing and abuse regulation. Public abuse databases show at least one low-confidence report on an AS58067 address. That is a weak signal, not a systemic finding. A regional operator with public IP space will receive noise. The relevant question is whether it has abuse handling, routing hygiene, RPKI discipline and customer controls strong enough to prevent reputation damage. Public BGP views showing valid RPKI originations are a positive sign; stale names in PeeringDB and route objects are less positive but fixable.
Unofficial signals show a field organisation, not a retail brand
The company's unofficial footprint is more revealing than its marketing footprint. Public job listings show operating groups in Moscow, Novosibirsk, Vladivostok, Ulan-Ude, Vолжsky and Chita. They describe measurement, preventive maintenance, restoration work, documentation, commissioning, equipment monitoring, electrical-safety requirements, mandatory medical checks and long trips. They also describe work on communications equipment, line-cable facilities and fibre on overhead power lines. This is the language of a field organisation.
That matters because many network companies look large in BGP and small on the ground, or large on the ground and invisible in BGP. Moscow Energy Communication Node has both kinds of evidence: public routing and public field-work signals. The combination supports the thesis that it is more than a paper ASN and less than a national retail carrier.
The weak signal is public sales posture. There is no broad public catalogue comparable to a mass-market ISP or cloud provider in the sources extracted for this article. The current site was not reliably extractable in this run, while the old Chitatehenergo site provided a merger notice. PeeringDB still carries the Chitatehenergo name. Public industry pages remember EESTelecom, but the company's current public-market proposition is not as legible as its captive operating function.
That is not necessarily bad. A captive industrial operator does not need a glossy retail site to be economically useful. It may sell through group procurement, direct carrier relationships and long-term industrial trust. But opacity limits outside confidence. If the outside-market story is important, public evidence should eventually show clearer products, customer references, route offers, peering policies and post-merger brand consistency.
The social-company profile claim of more than 25,000 km of serviced FOCL/OPGW is important but should be treated as a public profile claim, not audited route inventory. If accurate and current, it supports a serious external-capacity option. If partly historical or inherited, it still indicates the type of asset base the company wants the market to associate with its name.
The modest public abuse signal also fits the profile. One low-confidence AbuseIPDB report on one IP does not change the judgment. It simply belongs in the watchlist for any operator whose network has downstreams and public address space. The more external customers the company serves, the more abuse process and route hygiene become economic assets.
The economic judgment
Moscow Energy Communication Node is economically rational as a trusted utility-telecom operator. It is not obviously a high-growth ISP. Its 2025 accounts show real revenue, positive profit and a strong-enough balance sheet for its role, but the net margin is thin enough that management quality matters. The company must make physical infrastructure, regional labour and legacy rights of way earn more than they cost to keep reliable.
The central advantage is not the ASN, not the legal age, not even the fibre alone. It is the combination of energy-sector embeddedness, field access, technical maintenance capability, licenses, routing presence and customer trust. That combination is hard for a generic carrier to reproduce. It is also hard to turn into high margins because the anchor customer is sophisticated and the work is operationally demanding.
The best strategy is disciplined external monetisation. Sell spare capacity where the route has structural scarcity. Sell to carriers where the energy corridor changes their economics. Sell technical services where power-site competence is required. Keep commodity offers secondary. Price every external contract as though restoration, documentation, spares, lifecycle risk and regulatory duties are real costs.
The worst strategy would be to treat spare fibre as free inventory. It is not free if it increases maintenance complexity, creates restoration conflicts, adds abuse risk, or forces replacement capital ahead of plan. A spare channel that cannot pay for its share of resilience is not monetisation. It is a subsidy from the captive grid mission to an outside customer.
The current public evidence leans cautiously positive. The company has a credible operating base, visible network capability, a major captive anchor and at least some historical evidence of external carrier value. The financial return is modest but not broken. The Chitatehenergo merger could increase regional reach and marketable assets if integration is disciplined.
The uncertainty is large. Public sources do not disclose external revenue share, route utilisation, margin by customer, contract penalties, capex backlog or outage performance. Without those, the right stance is not enthusiasm. It is respect with conditions.
What would change the judgment
Several facts would materially improve the view. The first is 2026 reporting after the Chitatehenergo merger showing revenue growth without margin dilution. The second is a disclosed external-revenue mix showing material sales to carriers, industrial customers or regional networks outside Rosseti-group transfer demand. The third is route-utilisation evidence showing spare capacity sold without reducing the captive reserve needed for restoration and resilience. The fourth is contract evidence that external customers pay for their true share of maintenance, renewal, spares, access work and SLA risk.
Evidence of a funded equipment lifecycle plan would also matter. If the company can show that legacy western voice and network equipment is being migrated, supported or replaced without service disruption, supplier risk declines. If it can show stable RPKI, updated registry records, clean abuse handling and coherent post-merger network naming, market confidence improves further.
Several facts would worsen the view. A lost or repriced Rosseti/FSK maintenance contract would be material. So would evidence that external capacity sales impair restoration priority for electricity-sector communications. A major outage, critical-infrastructure security enforcement action, route hijack, repeated abuse problem or license issue would shift the risk assessment. 2026 accounts showing that Chitatehenergo integration raised costs faster than revenue would also change the story.
The final judgment is therefore precise. Moscow Energy Communication Node should be valued as a utility-communications operator with merchant upside, not as a generic ISP with a captive customer. The economic task is to make fibre built for the grid earn outside the grid, while remembering that the grid is why the fibre is valuable in the first place.
Sources
- https://chte.ru/
- https://eesnet.ru/
- https://companies.rbc.ru/amp/ogrn/1027739290897/
- https://www.tbank.ru/business/contractor/legal/1027739290897/
- https://companium.ru/id/1027739290897-mus-ehnergetiki
- https://agentom.ru/company/7705039240/
- https://zachestnyibiznes.ru/company/ul/1027739290897_7705039240_AO-MUS-ENERGETIKI
- https://synapsenet.ru/organizacii/1027739290897-ao-mus-energetiki
- https://static.basis.seldon.ru/ru/company/1027739290897/sro
- https://e-disclosure.azipi.ru/organization/personal-pages/18712/
- https://np-pst.ru/lr-469/spisokdeystvushikh/42-uncategorised/543-otkrytoe-aktsionernoe-obshchestvo-moskovskij-uzel-svyazi-energetiki
- https://cbr.ru/rbr/insideDKO/doc?id=51619
- https://www.comnews.ru/content/205155/2020-03-23/2020-w13/fsk-ees-ischet-podryadchika-upravlenie-setyami-svyazi
- https://www.comnews.ru/content/220415/2022-05-26/2022-w21/rosseti-cifra-imya-marku
- https://www.comnews.ru/content/234875/2024-09-10/2024-w37/1180/keptivnye-it-kompanii-rynke-informacionnykh-tekhnologiy-rossii-2024
- https://www.cnews.ru/book/%D0%A0%D0%BE%D1%81%D1%81%D0%B5%D1%82%D0%B8_%D0%A6%D0%B8%D1%84%D1%80%D0%B0_-_%D0%9C%D0%A3%D0%A1_%D0%AD%D0%BD%D0%B5%D1%80%D0%B3%D0%B5%D1%82%D0%B8%D0%BA%D0%B8_-_%D0%95%D0%AD%D0%A1%D0%A2%D0%B5%D0%BB%D0%B5%D0%BA%D0%BE%D0%BC
- https://www.linkedin.com/company/%D0%B0%D0%BE-%D0%BC%D1%83%D1%81-%D1%8D%D0%BD%D0%B5%D1%80%D0%B3%D0%B5%D1%82%D0%B8%D0%BA%D0%B8
- https://www.interfax-russia.ru/far-east/news/mts-i-fsk-postroili-vols-ot-tyndy-do-mirnogo
- https://rdap.db.ripe.net/entity/ORG-MCCo1-RIPE
- https://rdap.db.ripe.net/autnum/58067
- https://rdap.db.ripe.net/autnum/56702
- https://rdap.db.ripe.net/ip/176.114.16.0/20
- https://rdap.db.ripe.net/ip/185.214.76.0/22
- https://rdap.db.ripe.net/ip/91.226.222.0/23
- https://rdap.db.ripe.net/ip/2a0b:97c0::/29
- https://stat.ripe.net/data/as-overview/data.json?resource=AS58067
- https://stat.ripe.net/data/announced-prefixes/data.json?resource=AS58067
- https://stat.ripe.net/data/announced-prefixes/data.json?resource=AS56702
- https://bgp.he.net/AS58067
- https://bgp.he.net/AS56702
- https://bgp.he.net/net/176.114.27.0/24
- https://ipinfo.io/AS58067
- https://ipinfo.io/AS56702
- https://asrank.caida.org/asns/58067
- https://2ip.io/as/58067/
- https://www.peeringdb.com/asn/58067
- https://radar.cloudflare.com/as58067/
- https://www.ip2location.com/as56702
- https://www.ip2location.com/176.114.21.0
- https://ip.osnova.news/ip-v4/176.114.25.231/
- https://www.abuseipdb.com/check/176.114.22.206
- https://bgp.he.net/AS204277
- https://ipgeolocation.io/browse/asn/AS58060
- https://www.roseltorg.ru/procedure/ROSSETI14012600023
- https://www.roseltorg.ru/procedure/ROSSETI28012600038
- https://zakupki.kontur.ru/IS57821154
- https://energybase.ru/tender/019d950a-10e9-72ef-ac12-8a9b9c5f4a98
- https://energybase.ru/tender/019d9731-ec0a-73ec-a73f-065dcd9deeac
- https://www.roseltorg.ru/procedure/32515527581
- https://energybase.ru/tender/019dbb67-ae01-73d5-9ac2-4b54b5574f0b
- https://b2b.house/activepurchase/rd4fc23d5-3eca-4160-a332-d5c011f3ad87_8f011737/
- https://zakupki.kontur.ru/customers/7705039240
- https://novosibirsk.careerist.ru/vakansii/glavnyy-spetsialist-novosibirskoy-ekspluatatsionno-remontnoy-gruppy-79628474.html
- https://ru.joblum.com/job/glavnyj-specialist-novosibirskoj/31141728
- https://dreamjob.ru/employers/115702/vakansii/126531189
- https://dreamjob.ru/employers/6284365/vakansii
- https://careerist.ru/vakansii/vedushchiy-ekspert-otdel-ekspluatatsii-konvergentnykh-setey-86007270.html
- https://www.company.rt.ru/en/about/net/magistr/
- https://www.msk-ix.ru/en/
- https://www.msk-ix.ru/en/about/
- https://pulse.internetsociety.org/en/ixp-tracker/ixp/72/
- https://kb.msk-ix.ru/en/ix/about/
- https://www.consultant.ru/document/cons_doc_LAW_43224/
- https://www.consultant.ru/document/cons_doc_LAW_540121/
- https://pravo.gov.ru/proxy/ips/?docbody=&firstDoc=1&lastDoc=1&nd=102439340
- https://www.consultant.ru/document/cons_doc_LAW_61801/
- https://ofac.treasury.gov/faqs/added/2024-06-12
- https://finance.ec.europa.eu/publications/software_en
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance