
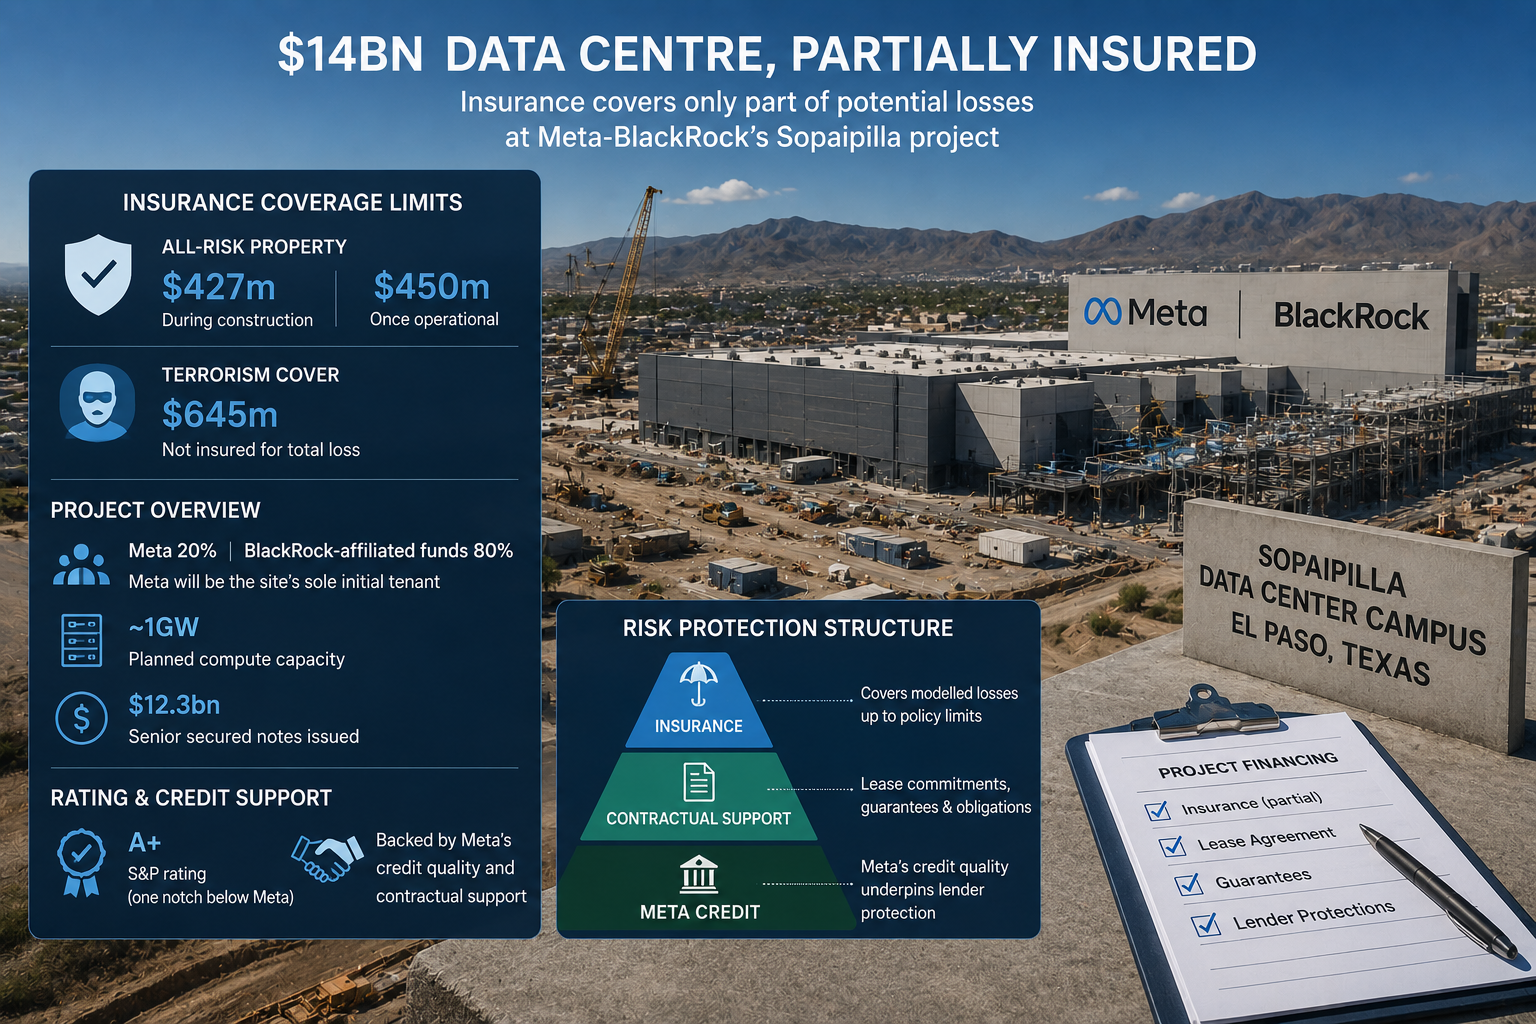
- The El Paso project's all-risk property cover is capped at $427m during construction and $450m once operational
- S&P rates the $12.3bn project debt A+, saying Meta's credit quality and contractual risk transfer underpin the rating
The fact
The $14bn Sopaipilla data-centre project being developed by Meta and BlackRock in El Paso, Texas, has insurance covering only part of the losses it could face in a major incident, the Financial Times reported. Its all-risk property cover is capped at $427m during construction and $450m once operational, while terrorism cover is limited to $645m. The project is not insured against a total loss.
The campus is designed for about 1GW of compute capacity. BlackRock-affiliated funds hold 80% of the venture and Meta 20%, with Meta due to become the site's sole initial tenant. Sopaipilla Investor has issued about $12.3bn of senior secured notes. S&P rates the debt A+, one notch below Meta, and says Meta's credit quality and contractual risk transfer underpin the project rating. The FT also reported that Meta can terminate its lease without penalty if a severe casualty causes a project delay of more than 18 months.
The assessment
The financing does not rely on insurance alone. Instead of covering the full value of the campus, the project uses insurance for modelled losses and relies on Meta's lease, guarantees and other contractual obligations for additional protection. That leaves lenders accepting the possibility that a catastrophic loss could exceed the policy limits.
The distinction matters because those protections behave differently. Insurance pays against defined insured events, while the value of Meta's support depends on the contracts remaining in force and the company meeting its obligations. A casualty severe enough to trigger the lease termination provision could therefore weaken the cash flow supporting the debt even though other protections remain.
For BTW readers, Sopaipilla shows where risk can move when a data-centre project becomes too large to insure at full replacement value. More of the financing then rests on tenant credit, guarantees and lease terms, making those contracts part of the infrastructure risk assessment rather than simply the commercial paperwork around the asset.
What to watch
Watch whether Sopaipilla's insurance limits change as construction advances and whether rating agencies revise their view as the campus approaches operation. Comparable hyperscale financings will show whether lenders continue accepting modelled-loss cover rather than full replacement insurance. Tighter reserve, guarantee or lease requirements would indicate that catastrophe risk not absorbed by insurers is being priced elsewhere in the financing.
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance