
Summary
- Linkservice LLC is best understood as a local-access economics problem, not as a simple directory profile. The public record ties the company to Bender, the
links.mddomain, and AS49560, but the same record also shows severe fragility: de facto Transnistrian authorities reported license annulment in 2023, while major routing datasets later show AS49560 as inactive or no longer visible in global BGP. - The core invoice test is narrow. A household may pay a visible monthly price for internet, IPTV or a bundle, but the retained value has to cover wholesale connectivity, optical equipment, customer-premises gear, field technicians, support, repairs, payment friction, renewal capex and legal operating risk. Competitor prices in Bender leave limited room for every cost shock to be passed through.
- The strongest evidence for upside is historical density: sources describe Linkservice as a Bender-focused operator with thousands of subscribers, early FTTx adoption and a local reputation for speed and value. The strongest evidence against investability is control risk: if licenses, routes and customer contracts are not demonstrably live, registry assets and brand memory do not equal serviceable revenue.
- Any judgment should remain conditional. Linkservice becomes economically interesting only if current lawful operating authority, active traffic arrangements, a recoverable customer base and a clean equipment-renewal plan can be shown together. Without those facts, the company is a case study in how a small ISP can lose local margin even before the physical network has lost all technical value.
Start with one customer invoice
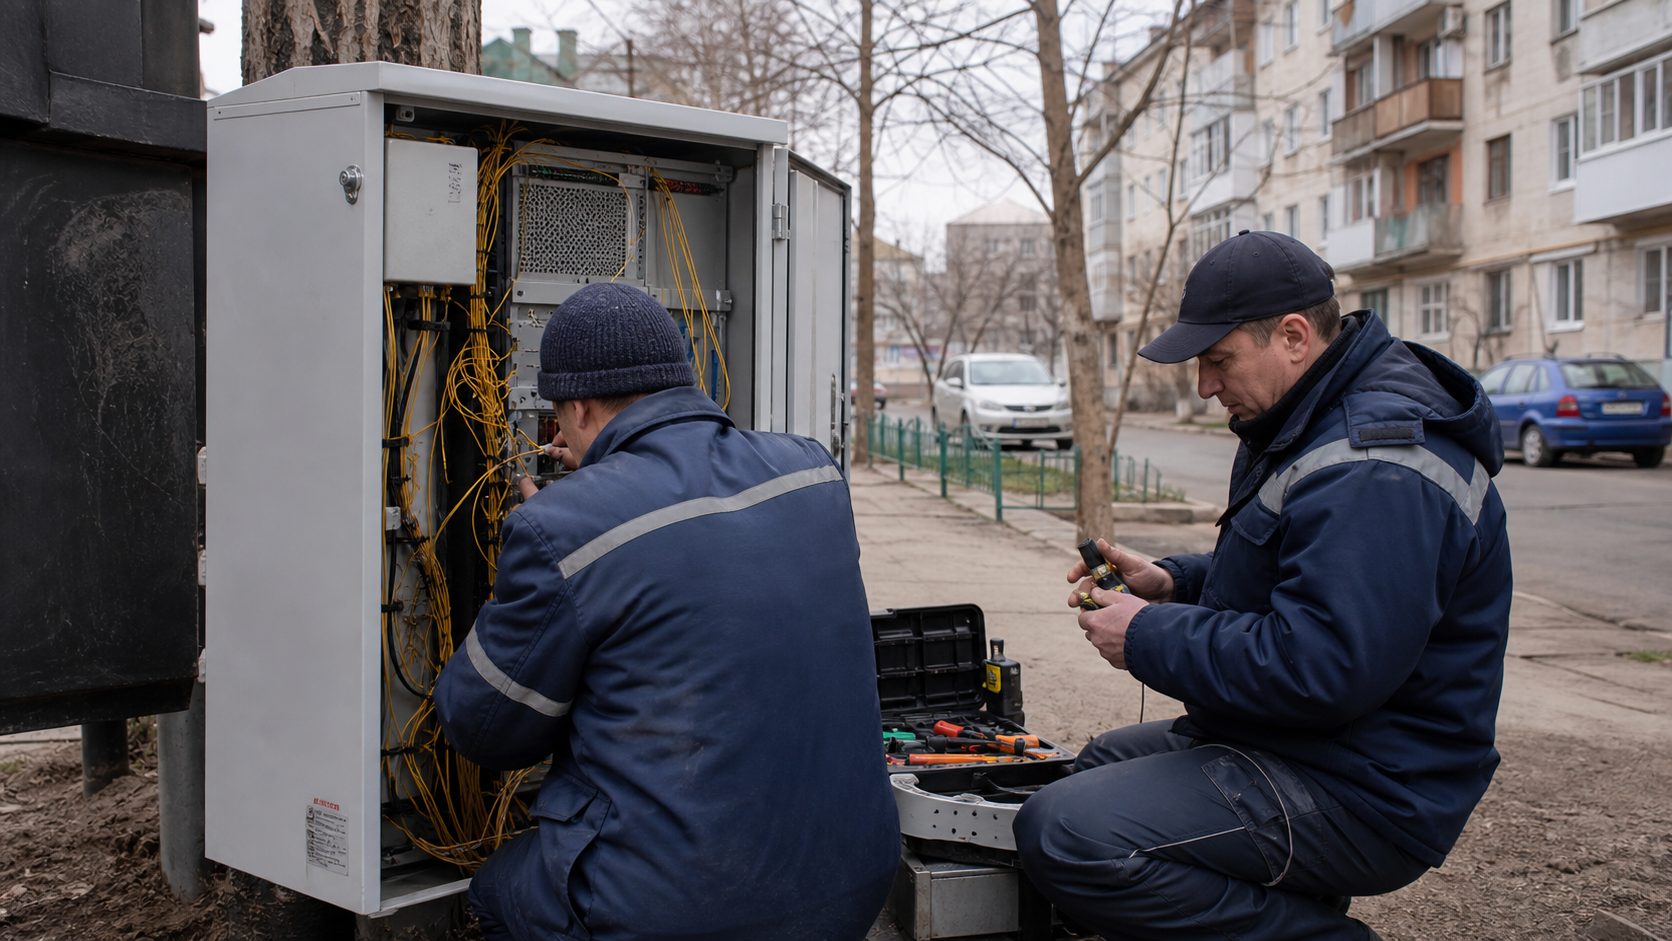
Start with a customer in Bender looking at an internet bill. The invoice may appear simple: a monthly fee, perhaps a speed tier, perhaps television, perhaps a small connection charge or equipment condition. To the customer it is a utility payment. To a local ISP it is a stack of claims on the same cash. Some of the invoice pays for imported customer equipment. Some pays for in-building or last-drop maintenance. Some pays for upstream capacity and transport. Some pays for support staff who answer calls when a router fails, an IPTV stream freezes, a thunderstorm damages a building switch, or a line is cut in a stairwell.
Some pays for billing, rent, power, tax, compliance and renewal capital. Only what remains after all of that is the retained service value that can defend the business.
That distinction matters more for Linkservice LLC than for a national operator. Public sources identify Linkservice as a Bender-based provider associated with Sovetskaya Street 54b, the links.md domain and AS49560. Local sources and third-party directories describe a provider that served households and legal entities, used fiber access, and built a recognizable local reputation. De facto PMR official media later reported that the company's licenses were annulled after arbitration proceedings, and that about 6,000 subscribers were affected by the 2023 transition. Those two facts pull in opposite directions. A 6,000-subscriber city footprint can be economically meaningful if it is dense, lawful and technically current. It can also become a stranded asset if the customer base migrates, the routes disappear from global visibility, and the company has no clean authority to sell service.
The invoice test therefore begins with pass-through. If a customer pays roughly the same price that IDC or Monitoring advertise for a comparable Bender fiber plan, Linkservice cannot assume that headline revenue belongs to the company. Competitor pages show home-fiber offers in the low-to-mid hundreds of local rubles per month. These prices set the customer's substitution anchor. A smaller provider may beat that anchor with better support, local responsiveness or a familiar building footprint, but it cannot ignore it. A household facing a license scare is not underwriting the operator's upstream contract or currency risk.
It wants the connection to work tomorrow.
The retained margin question is tougher because the expensive inputs are not necessarily priced in the same currency as the invoice. Optical network terminals, routers, media converters, switches, fiber parts, splicing tools, server parts and some software support are exposed to hard-currency or hard-currency-linked pricing. International capacity and transit relationships are also not naturally priced like a local apartment bill. If the local currency weakens, if import channels become more expensive, or if suppliers require prepayment, the visible monthly tariff may not move fast enough to protect the operator.
A large operator can smooth that pressure across a national subscriber base, mobile revenues, television bundles and purchasing scale. A local operator has fewer places to hide the shock.
This is why the company cannot be valued by counting subscribers alone. A reported 6,000-subscriber base at a local benchmark of 125 to 180 rubles per month would imply an order-of-magnitude gross residential billings range of about 750,000 to 1,080,000 rubles per month before business customers and bundles. That is not a Linkservice revenue figure. It is a stress test. The useful point is that a city ISP's total monthly invoice pool can look substantial to a customer-facing business while still being vulnerable after labor, capital refresh, equipment subsidy and regulatory friction are removed.
If the operator has to replace customer routers, rework building cabling, restore documentation, change upstream arrangements, or win back migrated subscribers, the cash pool can evaporate quickly.
The correct economic question is therefore not whether Linkservice once provided internet in Bender. It did. The better question is whether the company can still defend a local access spread: the difference between what a customer is willing to pay for a reliable local connection and the full cost of delivering that connection lawfully, continuously and competitively in a small market. Everything else in the evidence record should be read through that spread.
Identity, jurisdiction and the control boundary
The identity evidence is relatively consistent at the surface. Linkservice LLC appears in routing and IP intelligence sources as the registered name behind AS49560. Multiple third-party mirrors and mapping sources point to Bender/Bendery, Sovetskaya 54b and the links.md domain. The domain itself has a long history, with public domain-intelligence data showing registration in 2005 and later Cloudflare-fronted DNS. Forum-copied company material and local directories also describe a provider founded in the mid-2000s, focused on internet access in Bender, and using FTTx technologies early in its local deployment. That is enough to establish a real historical operating identity.
The control boundary is less straightforward. Bender lies inside Moldova's internationally recognized borders, but Transnistria has operated with de facto independence since the 1992 conflict. Freedom House describes the territory as Not Free, with restricted political competition and heavy dependence on Russia. For a telecom operator, that is not abstract country-risk language. It determines who can interrupt service, who can license or delicense an operator, who controls ducts and building access, who polices personal-data rules, and who can pressure customers to migrate.
Moldova's national regulator data is useful for understanding the broader fixed broadband market, fiber adoption and national macro conditions, but Linkservice's immediate existential risk came from de facto local institutions.
That matters because infrastructure assets do not control themselves. A local ISP needs rights to string or house cables, enter buildings, install equipment, bill customers, process personal data, receive payments, interconnect or buy upstream capacity, and keep staff in the field. The PMR official account alleged problems with mounting and commissioning lines on facades, trees, poles and stairwells, absence of some contracts, and personal-data compliance.
Linkservice's side, as reported by local media and forum reposts of company communications, said it had been working on remediation, documentation, permissions and preservation of jobs and subscribers. The article cannot adjudicate those claims beyond the reported court and ministry notices. It can say that the operating surface was contested and that the contest reached the level of license annulment.
For investors, suppliers or business customers, this is the first practical lesson. A local fiber footprint is not only optical cable and switches. It is a bundle of permissions. If those permissions are weak, a competitor can wait for churn, a regulator can convert compliance failures into a service interruption, and customers can be told to choose another provider before technical assets have physically failed. That is a control problem, not just a compliance problem. The operator may still have technicians, ducts, customer trust and registered number resources, but the value of each depends on lawful use.
The same boundary shapes any discussion of ownership or market power. U.S. State Department reporting via ecoi.net described Linkservice as Transnistria's second-largest ISP during the 2020 shutdown episode and recorded user and civil-society suggestions that Sheriff-controlled Interdnestrcom was trying to eliminate competitors. That is an attributed market-risk signal, not proof of motive. Still, the fact that the allegation appears in a government human-rights report is economically relevant. A local ISP operating beside a dominant vertically connected telecom group is not simply competing on megabits per ruble.
It is competing on regulatory endurance, customer reassurance and political tolerance.
The control boundary also explains why registry records are insufficient. AS49560, IRR as-sets, addresses and domain entries show that a network identity existed and may still be registered. They do not prove a current right to sell retail internet in Bender. An operating assessment has to combine corporate identity, route visibility, license status, customer-contract continuity and building-level access. Linkservice's public footprint provides fragments of each, but not a complete current proof set.
What the network record says, and what it no longer says
The routing record supports two conclusions at the same time. First, Linkservice was a real network operator, not only a local reseller with a website. AS49560 appears as LINKS-MD-AS, associated with Linkservice LLC, RIPE registry data, Moldovan country code and Bender address evidence. The AS-LINKSERVICE IRR object lists AS49560 and AS203019 as members. StarNet-related IRR and BGP-context pages include Linkservice among Moldovan routing relationships, and third-party mirrors list imports from AS35320, AS3257 and AS31252. Public IP intelligence pages show multiple IPv4 ranges and an IPv6 block associated with the company in some datasets.
This is infrastructure evidence.
Second, current visibility is weak. Hurricane Electric reports that AS49560 had not been visible in the global routing table since 9 July 2024 and shows zero currently announced prefixes in the captured page. IPinfo labels the AS inactive and shows no current prefixes, peers, upstreams or downstreams in its own dataset. That does not by itself prove that every physical cable or customer relationship disappeared, because BGP tools observe public routing, not local contractual arrangements or private wholesale service. But it does sharply limit any claim that Linkservice is presently operating a normal independent public network under AS49560.
The contradiction with other IP-intelligence sources should not be brushed aside. Ipregistry, IP2WHOIS, IPSHU and pdflibr list prefix inventories or RDAP-derived details for AS49560. IPAddress.my and IP2Location associate individual IPs in the 92.51.56.0/21 area with LinkService LLC and Bender. Scamalytics reports observed Linkservice IPs by country and risk category. These sources may reflect registry allocations, stale geolocation, partial observations, or ranges that remain assigned even when not visible as live public routes. Registry inventory is not the same thing as traffic origination.
Historical allocation is not the same thing as a current upstream path.
This distinction is central to the business model. A local ISP's customer experience depends on continuity: route visibility, upstream reachability, DNS, local network health, customer equipment, and help-desk response. A company can retain a name in the RIPE database while losing the ability to provide retail service at scale. Conversely, a company can continue some limited service through another network arrangement while its own AS looks inactive. The public evidence available here does not resolve that. It says the independent AS49560 signal became materially weaker after the licensing shock.
If Linkservice sought to rebuild, the network proof required would be simple and demanding. It would need live global route origin evidence, updated RIPE/RDAP records, clear origin validation or route authorization, a named upstream or peering arrangement, and a customer-facing service statement that matches legal authority. It would also need to explain any differences between historical prefix inventory and present use. If the business had sold infrastructure, leased lines, moved customers to another operator, or used a different ASN, that would change the interpretation.
Without those facts, the safest conclusion is that Linkservice's registry history supports historical network competence, while the recent BGP evidence supports caution about current scale.
The technical record also affects unit economics. Owning or controlling address resources and an AS can improve bargaining leverage, resilience and service differentiation. Losing public visibility or needing to buy service under another operator's umbrella can compress margin. It can turn a local ISP from a network operator into a retail or support layer dependent on wholesale terms. The customer's invoice may look similar, but the retained service value changes. Upstream costs become more contractual and less controllable. Troubleshooting can become slower. Differentiation narrows to price and field support.
For Linkservice, the question is therefore not whether AS49560 once existed. The evidence shows it did. The question is whether the AS, the physical network and the customer base still sit under one commercial control surface. The public record does not yet prove that they do.
Density, field labor and renewal capital
Small-city broadband works when density is doing most of the economic lifting. If many subscribers live in apartment blocks already passed by fiber, the cost of serving one additional household can be low. A technician may run a short drop, configure a router, check an optical level or terminate copper from a building switch. A dense building makes a modest monthly tariff more plausible because fiber, switches, power and maintenance can be shared across many apartments. Bender's multi-storey housing and the historical descriptions of Linkservice wiring apartment buildings are therefore economically important.
They suggest the company may have once had the kind of footprint that a national operator would find annoying but not impossible to attack.
The same density can become a trap. An FTTB or FTTH network is not self-renewing. Building switches age. ONTs fail. Customer routers become obsolete as Wi-Fi expectations rise. IPTV boxes and middleware lose support. Fiber drops are cut during renovations. Power events and storms damage equipment. Copper in the final meters corrodes or gets poorly reterminated. Technicians have to revisit homes where the original installer has long gone. A customer who pays for a 100 Mbps plan expects not only access but stable in-apartment Wi-Fi, low latency and video streaming. Each expectation turns into a service cost.
Monitoring's public page is useful because it makes the equipment problem visible. The competitor advertises GPON, ONT, Wi-Fi 6, media converters, SFP modules and different optical access architectures. That tells us what the local customer market has normalized. A provider defending share in Bender is not selling 2005-era connectivity forever. It is competing in a market where customers see fiber, GPON and modern Wi-Fi equipment in the retail offer. If Linkservice's legacy base was FTTB-heavy or used older routers, renewal capital would be required just to avoid falling behind, even before any growth project.
Field labor is the less visible side of the same issue. A local ISP often wins because its technicians know the buildings, the building managers, the troublesome stairwells and the informal local repair patterns. That knowledge has value. It also costs money. Skilled field staff do not remain indefinitely with a company facing license uncertainty, customer migration and uncertain cash flow. If churn rises, the work mix becomes worse: fewer normal installations, more angry support calls, more disconnects, more equipment recovery and more documentation disputes. The labor cost per retained subscriber can rise even as total revenue falls.
The PMR official allegations about line installation and documentation make this point sharper. If an operator has to remediate line placements, formalize access agreements, redo contracts or document personal-data processing, those are not one-time legal inconveniences. They consume management attention and field capacity. A larger operator can assign compliance staff and absorb the expense. A small operator's best field people may be the same people needed to keep the network alive. Compliance repair can therefore crowd out technical renewal precisely when customers are deciding whether to stay.
The economics become most difficult when density and renewal timing diverge. A dense customer base can support investment if subscribers stay long enough to amortize the equipment. But if regulatory uncertainty causes a mass migration, the operator may have to spend capital on the customers least likely to remain. Competitors can exploit that by subsidizing connection equipment. IDC's page advertises equipment for 1 ruble under a long contract; Monitoring's migration-related and current pages show inexpensive equipment and connection offers.
Those terms move capex from the customer's first payment into the operator's balance sheet. A small ISP cannot match every subsidy unless it has confidence in customer life and legal continuity.
This is why the Linkservice case should be read as a retained-margin problem. The public evidence suggests the company had local density, a recognizable brand and technical capability. It also suggests that the formal control layer weakened. In that situation, the physical access network may still have value, but the value shifts from growth to salvage, lease, sale, remediation or narrowly targeted retention. A company defending that position must know exactly which buildings are profitable after support costs, which customers are likely to churn, which equipment must be replaced, and which regulatory defects can be cured.
Without that map, every ruble of renewal capital risks being spent on a shrinking base.
Pricing and unit economics in Bender
The Bender price environment is not generous. IDC's public English tariff page lists fiber home plans from 60 Mbps at 125 rubles/month to 300 Mbps at 350 rubles/month. Monitoring's homepage lists popular home plans from 75 Mbps at 128.80 rubles/month to 300 Mbps at 241.50 rubles/month. These are competitor offers, not Linkservice offers. Still, they are the relevant benchmark because they shape what a Bender household considers normal. Any Linkservice comeback or continuation would have to fit inside that willingness-to-pay band unless it offers a clearly superior niche.
The apparent simplicity of those prices hides the unit-economic problem. Broadband access has high fixed and semi-fixed costs. The operator pays for network nodes, power, customer support, technicians, upstream capacity, billing systems, spare parts, vehicle time and administration whether a particular household streams heavily or lightly. The marginal cost of one more gigabyte can be low inside a well-provisioned network, but the cost of keeping enough capacity and resilience for everyone is not zero.
When plans promise 100 Mbps or 300 Mbps, the provider is selling peak capability and trust, not a guaranteed dedicated circuit to every customer. Oversubscription works only while customer usage patterns, upstream cost and reputation stay in balance.
A small operator has fewer tools to manage that balance. It can shape tariffs, cap promotions, differentiate business service, charge for installation, sell IPTV, or offer better support. But if the competitors are larger, connected to broader networks, and willing to subsidize equipment during a migration event, the small operator's pricing discretion is limited. It cannot simply raise prices to cover imported routers or an expensive new upstream route if customers can switch to a familiar alternative for a similar or lower monthly fee. Nor can it permanently underprice the market if that prevents capex renewal.
The reported 6,000-subscriber figure is useful for stress testing. At 125 rubles/month, 6,000 subscribers produce 750,000 rubles/month in gross residential access billings. At 180 rubles/month, they produce 1,080,000 rubles/month. At 300 rubles/month, which is above many basic tariffs and closer to higher-speed or bundled services, the number becomes 1,800,000 rubles/month. Those numbers look very different depending on cost structure. If the network is dense, old capex is largely depreciated, churn is low and upstream terms are favorable, the business can be healthy.
If licenses are contested, customers are migrating, equipment needs replacement and technicians are spending time on remediation, the same gross billing pool can be insufficient.
The next issue is mix. Residential access is not the same as business connectivity. 2ip's profile describes Linkservice as serving individuals and legal entities. Forum-copied company material claims the network connected residents, businesses, government services and authorities. If true, business and institutional accounts could have carried higher margins, static IP demand, VPN demand, office network installation and better payment discipline. They could also create concentration risk. Losing a few institutional customers after a licensing scare may hurt more than losing a block of residential users.
Public sources do not provide Linkservice's customer mix, which is a major evidence limit.
IPTV complicates the invoice further. Historical forum posts and company descriptions mention IPTV and IP telephony. IPTV can raise ARPU and customer stickiness, but it also adds content, middleware, set-top box, support and rights complexity. If a customer pays for internet plus TV, the invoice is larger but the retained broadband margin may not increase proportionally. A small ISP needs to know whether television is profitable, defensive or merely expected. If a competitor bundles IPTV for little visible incremental charge, Linkservice may have had to match a feature that did not carry enough standalone margin.
Payment channels also matter. Forum comments from earlier years discuss office payment, cards and online bank payment. That might seem minor, but collection friction matters in small-operator economics. A household that has to visit an office or remember a local payment process is more likely to lapse, especially during uncertainty. A larger competitor with broader payment channels, mobile apps or bundle billing has an advantage. Payment convenience can reduce churn without changing the nominal tariff.
The article's central judgment follows from these mechanics. Linkservice's historical value proposition appears to have been speed, local service and price relative to IDC. That can work when the operator's access network is dense and its regulatory position is stable. It breaks when the company must fund compliance repairs, replace equipment, retain staff and reassure customers while competitors offer low-entry migration terms. In that environment, pricing is not a lever the operator fully controls. It is a constraint imposed by substitutes.
Suppliers, currency and hard-cost exposure
The Linkservice case is also a currency mismatch case. The customer sees a local-currency invoice. The operator buys a mix of local labor and externally priced inputs. Even if some parts are purchased through regional distributors and even if staff are paid locally, optical equipment and network electronics are exposed to global supply chains. GPON ONTs, Wi-Fi routers, media converters, SFP modules, switches, servers, batteries and test equipment are not produced for a tiny Bender access network in a local pricing bubble. They move with international component cycles, shipping, foreign exchange, inventory risk and supplier credit.
Moldova's central bank publishes official exchange rates and, since August 2024, interbank FX indicators to improve transparency. Those data are useful for understanding national currency risk, but Linkservice's customer prices and competitor tariffs in Bender are expressed in the local ruble environment used by de facto Transnistrian operators. The evidence here does not support a clean conversion from those rubles into MDL, dollars or euros. That is the point: the operator's economics include a translation layer that public tariff pages do not reveal.
If equipment is hard-currency-linked and customer tariffs are locally sticky, devaluation or supply disruption eats margin.
The same logic applies to upstream capacity. A network may buy transit, use a regional partner, peer through a local exchange, or rely on a larger operator. RIPE and BGP evidence suggest historical relationships involving AS35320, AS3257 and AS31252, and StarNet-related routing context includes Linkservice in Moldovan as-set or peer lists. Those relationships are not current contract evidence. They show that Linkservice operated in a regional routing ecosystem, not what it paid per Mbps, how much redundancy it had, or whether it could bargain effectively after license uncertainty.
Wholesale capacity is especially dangerous for a small ISP because customers experience it as quality, not as a separate invoice line. If external connectivity becomes congested, customers blame the provider. IDC's tariff page explicitly notes that speeds to external resources may differ from the maximum available package speed. That caveat is normal in broadband, but it matters for differentiation. A small provider that promises better speed has to buy enough upstream capacity or cache enough traffic to make the claim credible.
If hard-currency costs rise faster than local tariffs, the provider either tolerates congestion, raises prices, reduces margin or finds a different upstream arrangement.
Suppliers also influence customer concentration and churn. A provider that standardizes on certain routers or ONTs can support customers efficiently, but it may become dependent on stock, firmware and replacement availability. A provider that allows many customer-owned devices lowers capex but increases support complexity. Monitoring's public equipment list shows how visible these choices have become in the Bender market. Customers may not understand GPON architecture, but they do notice Wi-Fi 6, router quality and whether the device is included in the offer.
A small ISP trying to defend older equipment against a competitor subsidizing modern gear faces both technical and marketing pressure.
There is a working-capital angle too. Equipment subsidies are a cash-flow bet. When IDC says equipment can be acquired for 1 ruble under a two-year contract, the operator is using contract life to recover hardware cost. That is easier for a large incumbent with a broad customer base and strong balance sheet. A smaller operator under legal uncertainty cannot make the same bet unless it knows that customers will stay and that it will be allowed to serve them for the contract term. Otherwise, the subsidy becomes an accelerated cash drain.
The supplier lesson is simple. A local ISP can look local on the demand side and global on the cost side. Linkservice's customers may have paid local prices in Bender, but the network's renewal cycle sat in a world of imported electronics, upstream connectivity and currency exposure. That mismatch does not make the business impossible. It does make scale, density and pricing discipline non-negotiable. Without them, every capex refresh makes the operator more vulnerable.
Competition, substitutes and customer concentration
The substitute set after Linkservice's license shock was explicit. PMR official media repeatedly told Linkservice subscribers to choose other Bender operators and named Interdnestrcom and Monitoring. It also reported special connection conditions from those operators during the transition. That is not normal competition in which customers gradually compare offers. It is regulator-mediated churn. A customer does not have to dislike Linkservice to leave; the customer only has to fear losing internet access.
IDC's position is the first substitute problem. Its own homepage describes it as the biggest telecommunications company in the Pridnestrovian Moldavian Republic. It sells fiber internet, ADSL, IPTV, mobile and other services. That breadth matters because it can bundle, cross-subsidize, absorb customer acquisition costs and use established service centers. A local provider competing against IDC is not only matching an internet tariff. It is competing against a larger household communications account.
Monitoring is the second substitute problem. Its current website is Bender-specific enough to matter: it advertises home and business fiber, lets users check building connectivity, lists local phone numbers and address information, and promotes common optical technologies. For a Linkservice customer worried about continuity, Monitoring may look closer to the local specialist archetype that Linkservice once occupied. If Monitoring can connect a building quickly, it can convert uncertainty into share.
The third substitute is mobile broadband. The national ANRCETI data shows mobile internet use growing alongside fixed broadband. Mobile is not a perfect substitute for high-volume home fiber, especially for IPTV, gaming, multi-device households and office use. But as a short-term fallback during a license scare, it matters. Customers who can use mobile data for a month may be less willing to tolerate uncertainty or support a provider through a legal dispute. That reduces Linkservice's bargaining power during service interruptions.
Customer concentration cuts both ways. A Bender-focused footprint can create loyalty. Forum and review material show customers praising Linkservice's speed, price and support over many years. Local technicians can be more responsive than a national call center. The operator can know which buildings have reliable wiring and which subscribers need special handling. This is the advantage small ISPs often use to survive beside incumbents.
The problem is that concentration also creates a single point of failure. If nearly all value is in one city and the de facto authority in that city tells subscribers to migrate, the company has no second market to offset churn. If many customers live in the same apartment clusters, competitors can target those clusters efficiently. If a few business or public-sector customers represent a large share of profit, they may be the first to switch because they cannot tolerate legal uncertainty. A dense footprint magnifies both recovery and collapse.
The unofficial market evidence suggests Linkservice had a defensible product in normal times. Users described cheaper packages, better speed than IDC, stable service and responsive support. Some comments also show payment friction, TV complaints, and concern that the company lacked independence from a dominant local telecom environment. These comments are not audited data. They are still useful because they show what the brand meant to customers: speed and value, but also vulnerability.
For a comeback or residual operation, the competitive question would be whether that brand memory is enough to offset switching inertia. Customers who migrated under a six-month, two-year or equipment-linked contract may not return quickly. A household that has already accepted a new router and IPTV setup may need a strong reason to invite another installer. The value proposition cannot simply be nostalgia. It would have to be measurably better uptime, lower total price, better local support, business-grade service, or a niche where larger operators are less flexible.
The substitute-price evidence therefore points to a conservative conclusion. Linkservice's local brand and historical density may have created customer value. But once competitors could offer subsidized migration and comparable fiber speeds, the company needed more than goodwill. It needed license certainty, fast communication, clean building rights and a tariff structure that preserved margin without giving customers an obvious reason to leave.
Regulatory and geopolitical risk are operating costs
Regulatory risk is often described as external to the business. For Linkservice, it became an operating cost. The reported sequence ran from earlier inspection and suspension issues, to COVID-era postponement, to a December 2022 annulment decision, to a February 2023 cassation failure, to delayed execution, and finally to July 2023 notices telling customers to migrate. That timeline is not a footnote. It defines the company's cost of capital, customer life and supplier confidence.
A provider under license threat has to spend twice. It spends to maintain the network, and it spends to preserve the right to maintain the network. Management time goes to legal responses, documentation, regulator communication, customer notices and contingency planning. Technicians may have to disconnect or reroute customers affected by contested installations. Support staff must answer questions that have no purely technical solution. Even if the operator believes it is being treated unfairly, the cash impact is real.
The geopolitical setting raises the stakes. Transnistria is de facto separate but internationally recognized as part of Moldova. It is economically and politically exposed to Russia, Ukraine, Moldova and wider regional shocks. The World Bank notes that Moldova has faced spillovers from Russia's invasion of Ukraine, energy-price pressure and weak external demand. A local ISP in Bender does not need to be geopolitically important to be affected by these forces. Energy costs, import routes, currency volatility, equipment availability, customer income and political tolerance all move with the environment.
Regulatory risk also interacts with personal-data and security expectations. PMR official media reported allegations involving personal-data compliance. Whether or not every allegation is complete, an ISP does handle sensitive customer information: addresses, billing records, account credentials, contact information, traffic-related metadata and sometimes customer equipment configuration. A small provider cannot treat this as paperwork. Weak data governance can become a legal vulnerability, a customer-trust problem and a blocker for business customers.
The court and ministry notices also change how customers interpret communication. If an operator says service will continue but official media says internet will disappear after a deadline, customers face a practical decision. They may migrate even if they prefer the operator. That dynamic can create a self-fulfilling loss. Once enough customers leave, support quality, cash flow and staff retention deteriorate. The company then has less capacity to fight the legal case or repair compliance defects. Regulatory risk becomes operating risk through churn.
For Linkservice's economics, the most damaging effect may be uncertainty rather than the final legal outcome. Suppliers hesitate to extend credit. Customers hesitate to sign long contracts. Employees seek safer jobs. Building owners hesitate to approve new works. Competitors time promotions around deadlines. A bank or investor discounts the asset because the revenue base may not be transferable. By the time the legal status is finally known, the business may have already lost the density that made the network valuable.
That does not mean every regulatory action is anti-competitive or arbitrary. Telecom networks affect public safety, urban infrastructure, consumer contracts and personal data. Authorities can legitimately require permits, safe installation and proper records. The economic point is narrower: in a small local market, unresolved compliance failures can destroy value even when the physical network remains usable. A larger operator can sometimes survive a fine, an audit or a delayed permit. A city ISP can lose the customer base before the paper dispute ends.
This is why any future assessment of Linkservice must begin with current authority to operate. If the company has no license or lawful replacement arrangement, the business is not merely risky; it lacks the foundation for recurring retail revenue. If it has obtained a new arrangement, the next question is whether customers, routes and staff survived the gap. Regulatory status is not separate from the model. It is the model's first input.
Unofficial signals and what they can tell us
The informal record around Linkservice is unusually rich. Forum threads, customer reviews, speed-test profiles and local media comments describe a company that mattered to Bender users. They mention early FTTx, internet plus TV, payment methods, support experiences, pricing comparisons, fear of monopoly power, concern during court proceedings and debates over whether Monitoring or IDC could replace the service. These signals are valuable because small ISPs often leave fewer formal filings than large operators. The customer's voice may reveal service quality and switching behavior before official statistics do.
But these sources must be handled carefully. A forum post is not a tariff sheet. A speed-test directory is not proof of active lawful service. A copied company statement on a forum is not the same as a preserved official web page. A positive review from 2014 or 2020 does not prove service quality in 2023 or 2026. A complaint about IPTV does not prove systemic failure. The correct use is pattern recognition, not fact manufacturing.
The pattern is still informative. Linkservice appears to have competed on speed and price against IDC in Bender. Users described packages that felt better than the incumbent alternative, praised local support, and worried that losing Linkservice would reduce choice. Some forum material also shows users discussing substitute options and equipment fees once license risk became acute. That is exactly how a local access competitor creates and loses value: first through building-level service reputation, then through vulnerability to a larger operator's migration offer.
The 2ip profile is the most interesting unresolved signal. It lists Linkservice as an ISP, shows Bender address and contact evidence, and includes recent 2026 speed measurements. Taken alone, that might suggest continuing customer activity. Read against the license-annulment notices and AS49560 inactivity, it is not enough. The measurements could be stale attribution, users behind old IP ranges, a different ASN label, residual hosting, proxy traffic, or an actual limited continuation. The evidence limit should remain visible.
It is not honest to call the company fully alive based on a third-party speed-test profile, and it is not honest to ignore the signal entirely.
The same applies to IP geolocation pages that associate specific addresses with LinkService LLC and Bender. They support the historical connection between address space, domain and city. They do not prove that the IP is currently routed by Linkservice or used by residential customers. IP geolocation databases can lag ownership and routing changes. Fraud-observation datasets also see only slices of traffic. They are useful cross-checks, not final authorities.
Unofficial signals can still change a professional judgment if they line up with hard evidence. If new customer reviews, speed tests, traceroutes, route collectors, DNS records and license notices all pointed in the same direction, the combined signal would matter. In Linkservice's current public record, they do not line up. The soft sources show brand memory and possible residual traces. The hard sources show legal and routing discontinuity. That mismatch is the central uncertainty.
For a reader, the practical takeaway is to treat Linkservice as a high-evidence historical operator and a low-certainty current operator. The historical business can be analyzed: local fiber access, Bender density, price competition, customer support, upstream dependence and regulatory exposure. The current business cannot be assumed without fresh proofs. That difference prevents the article from becoming either an obituary or a promotional profile. It is a margin test under uncertainty.
What would change the judgment
Several facts would materially change the analysis. The first is a current license or legally equivalent operating authority. If Linkservice obtained new licenses after July 2023, transferred service into another lawful entity, or secured a wholesale arrangement that allowed continued customer service, the regulatory discount would fall. Without that, no amount of historical goodwill can support a normal retail valuation.
The second is live network evidence. AS49560 returning to global visibility with coherent route-origin records would not solve every problem, but it would show technical continuity. A documented upstream relationship, fresh RIPE/RDAP updates, route authorization and stable DNS/service infrastructure would help distinguish active operations from stale registry traces. If the company no longer uses AS49560 but operates through another network, the arrangement should be explicit.
The third is a customer-base audit. The reported 6,000 subscribers from 2023 is a key number, but it is old and came during a forced migration period. The economically relevant numbers today would be active paying subscribers, residential versus business mix, churn since the court notices, ARPU by bundle, arrears, retained buildings, equipment ownership and remaining contract life. A small ISP can be viable with fewer than 6,000 subscribers if the base is dense and high-margin. It can be unviable with more subscribers if they are low-paying, dispersed and expensive to support.
The fourth is a capex and supplier plan. Linkservice would need to show what equipment must be replaced, what can be reused, what is stranded, and how hard-currency exposure is hedged or passed through. A plan that depends on raising household tariffs materially above IDC and Monitoring benchmarks would face churn risk. A plan that subsidizes modern equipment without long customer life would face cash-flow risk.
The fifth is evidence of compliance repair. If the allegations involved building permissions, contracts and personal data, a comeback would require documented remediation. The company would need to turn informal local knowledge into defensible records: building access permissions, line maps, customer contracts, data-handling policies and support processes. This is not bureaucratic polish. It is what makes the network financeable.
Until those facts appear together, the judgment remains cautious. Linkservice's historical role in Bender was real, and its customer value proposition appears to have been meaningful. The economics of a dense local access network can work. But the public record shows a business whose control surface was damaged by licensing action and whose routing visibility later weakened. A customer invoice alone cannot carry that burden. The company would have to prove that the invoice still converts into retained service value after upstream capacity, imported equipment, field labor, customer churn, supplier risk and regulatory renewal are all paid.
Sources
- https://www.anrceti.md/node/23418
- https://www.anrceti.md/news_09072024
- https://www.anrceti.md/date_generale_ce
- https://mail.anrceti.md/news_031024
- https://en.anrceti.md/news_240921
- https://en.anrceti.md/news_140422
- https://en.anrceti.md/news_090421
- https://moldova.mom-gmr.org/en/findings/indicators/
- https://www.worldbank.org/ext/en/country/moldova
- https://data.worldbank.org/country/MD
- https://www.bnm.md/en/content/official-exchange-rates
- https://bnm.md/ro/node/67218
- https://freedomhouse.org/country/transnistria
- https://www.ecoi.net/en/document/2071144.html
- https://www.ecoi.net/de/dokument/2048126.html
- https://novostipmr.com/ru/content/s-18-iyulya-ranee-vydannye-licenzii-kompanii-linkservis-budut
- https://www.novostipmr.com/en/node/141138
- https://novostipmr.com/ru/news/23-03-31/arbitrazhnyy-sud-otsrochil-annulirovanie-licenziy-linkservisa-do
- https://novostipmr.com/ru/content/18-iyulya-budut-annulirovany-licenzii-linkservisa-napominayut-v
- https://novostipmr.com/ru/content/licenzii-linkservisa-budut-annulirovany-18-iyulya
- https://novostipmr.com/ru/content/zhitelyam-bender-predlagayut-vygodnye-usloviya-dlya-podklyucheniya-k
- https://np-inform.com/index.php/sobytiya/item/1288-linkservis-ostaetsya-v-benderakh
- https://2ip.ru/isp/Linkservice%2BLtd/
- https://2ip.ru/as/49560/
- https://ipinfo.io/AS49560
- https://bgp.he.net/AS49560
- https://bgp.he.net/irr/as-set/AS-LINKSERVICE
- https://ipregistry.co/AS49560
- https://ip2whois.ru/asn/49560
- https://ar.ipshu.com/asn/49560
- https://www.pdflibr.com/AS49560
- https://www.ipaddress.com/website/links.md/
- https://www.ipaddress.my/92.51.58.100
- https://www.ip2location.com/92.51.63.208
- https://scamalytics.com/ip/isp/linkservice-llc
- https://mapcarta.com/W289102548
- https://disput-pmr.ru/threads/%D0%9A%D0%BE%D0%BC%D0%BF%D0%B0%D0%BD%D0%B8%D1%8F-%D0%9B%D0%B8%D0%BD%D0%BA%D1%81%D0%B5%D1%80%D0%B2%D0%B8%D1%81.6081/
- https://disput-pmr.ru/threads/%D0%9A%D0%BE%D0%BC%D0%BF%D0%B0%D0%BD%D0%B8%D1%8F-%D0%9B%D0%B8%D0%BD%D0%BA%D1%81%D0%B5%D1%80%D0%B2%D0%B8%D1%81.6081/page-45
- https://disput-pmr.ru/threads/%D0%9A%D0%BE%D0%BC%D0%BF%D0%B0%D0%BD%D0%B8%D1%8F-%D0%9B%D0%B8%D0%BD%D0%BA%D1%81%D0%B5%D1%80%D0%B2%D0%B8%D1%81.6081/page-51
- https://disput-pmr.ru/threads/%D0%9A%D0%BE%D0%BC%D0%BF%D0%B0%D0%BD%D0%B8%D1%8F-%D0%9B%D0%B8%D0%BD%D0%BA%D1%81%D0%B5%D1%80%D0%B2%D0%B8%D1%81.6081/page-53
- https://otzovik.com/reviews/internet-provayder_linkservis_benderi_pridnestrove/
- https://forum-pmr.net/showthread.php?p=61387
- https://www.monitoringmd.com/
- https://eng.idc.md/internet/home
- https://eng.idc.md/connection/internet
- https://eng.idc.md/
- https://bgp.he.net/irr/as-set/AS-STARNET
- https://bgp.gibir.net.tr/as/31252
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance