
Summary
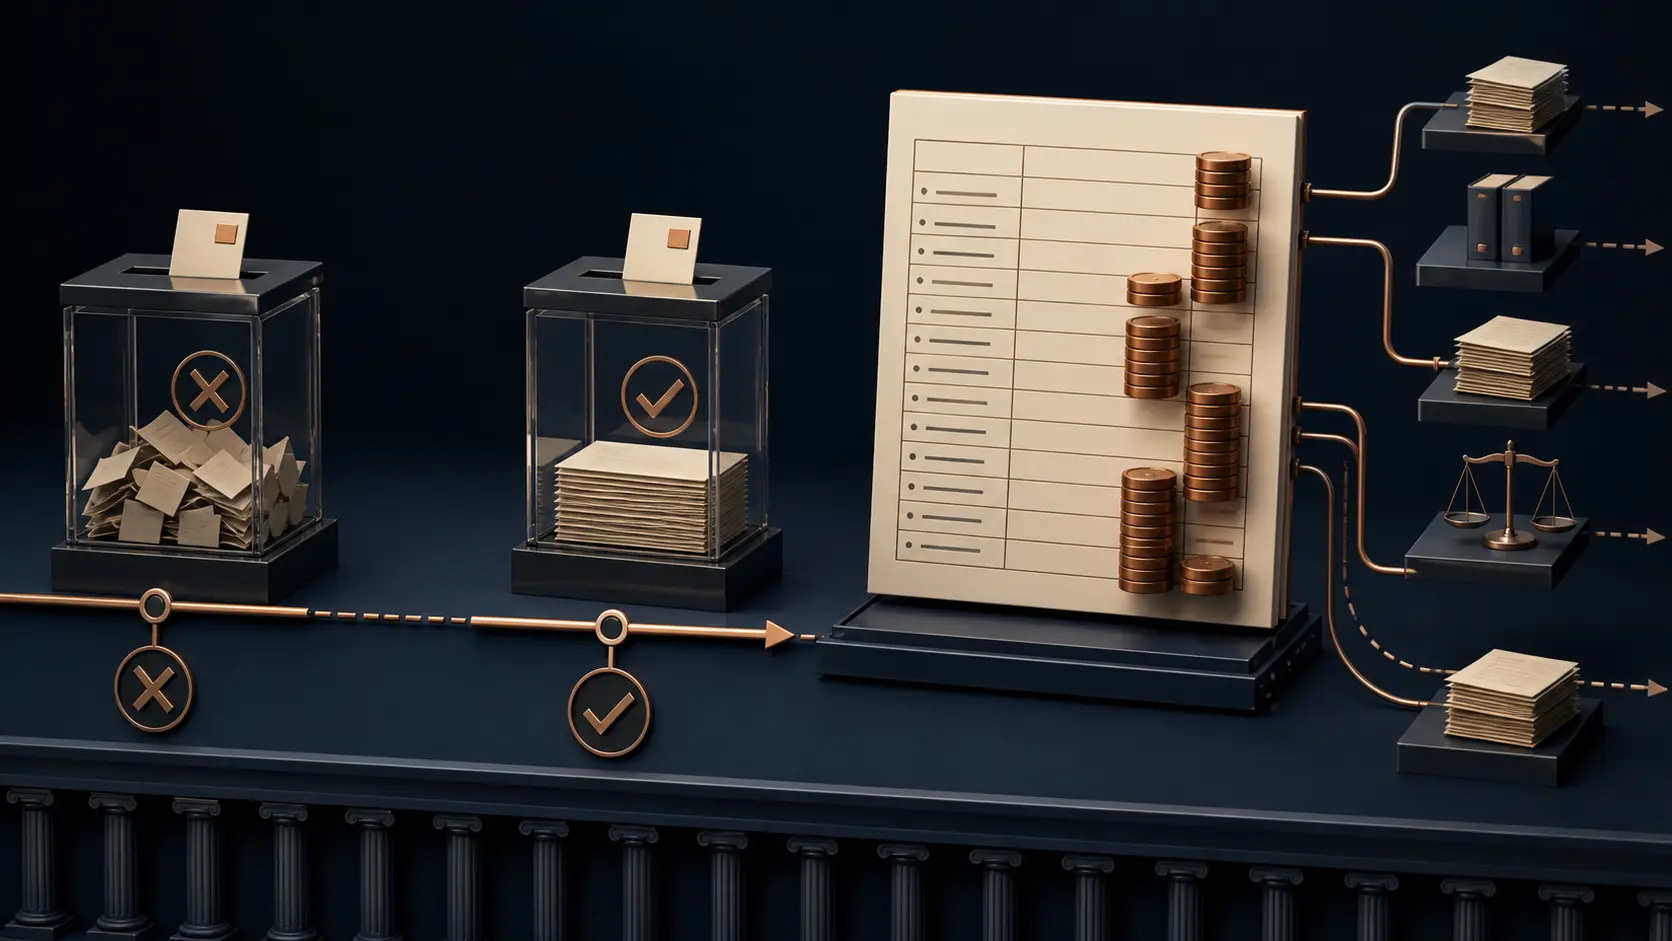
- AFRINIC attributed five costs to the 12 September 2025 Board-election rerun: USD 75,000 for GD Corporate as receiver’s fee, USD 19,600 for the Voatz election platform, USD 2,900 for Chilin Global’s candidate KYC, USD 14,046 as a token of appreciation to staff involved in the election, and USD 30 for taxi and stamp.
- The disclosed calculation closes exactly: USD 75,000 + USD 19,600 + USD 2,900 + USD 14,046 + USD 30 = USD 111,576. That is a reliable reconstruction of AFRINIC’s published subtotal, not proof that each amount was contracted, authorised, paid, priced appropriately or completely classified.
- The USD 931,849 June-election subtotal, three June chamber lines totalling USD 257,788, the combined two-election figure of USD 1,043,425 and the separate full-year legal-cost category of USD 877,929 are outside this September subtotal.
- Court orders supplied a route and timetable for a supervised rerun. They did not, on the checked record, approve the five prices. Later Board approval for issue of the annual statements, an unmodified audit opinion and a proposed member resolution likewise operate at different levels from transaction-specific authority.
- A serious contrary case exists: the rerun followed an annulled election, met a court deadline, used external platform and KYC inputs, produced an announced eight-person Board and cost much less than the June process. The evidence permits that recovery rationale, but not an efficiency or legitimacy verdict without comparable scopes and the missing transaction records.
Analysis
The subtotal, reconstructed without rhetorical additions
The central fact is unusually simple. AFRINIC’s official 2025 finance material places five lines under the election held on 12 September 2025. The first is USD 75,000 for “GD Corporate (Receiver’s fee)”. The second is USD 19,600 for Voatz, described as the election platform. The third is USD 2,900 for Chilin Global, described as KYC on candidates. The fourth is USD 14,046 for a token of appreciation to staff involved in the election. The fifth is USD 30 for taxi and stamp.
The arithmetic requires no balancing line, assumption or rounding adjustment:
USD 75,000 + USD 19,600 + USD 2,900 + USD 14,046 + USD 30 = USD 111,576
This is the bounded September rerun subtotal. Its strength is reproducibility. Anyone working from the five published numbers should reach the same answer. Its weakness is that arithmetic is only one kind of closure. It shows that AFRINIC’s disclosed inputs add to its disclosed output. It does not show what legal or contractual instrument created each obligation, whether an invoice was received, whether cash moved, whether an amount was accrued or reimbursed, whether taxes were included, whether a foreign-currency amount was translated, or whether the allocation captured the complete economic cost of the rerun.
The composition is also clear. The receiver-fee line accounts for about 67.22 per cent of the subtotal. All four other lines together account for USD 36,576. Voatz and Chilin Global together account for USD 22,500, or about 20.17 per cent. Staff appreciation accounts for about 12.59 per cent, and taxi and stamp account for a fraction of one per cent. Those shares identify where documentary scrutiny would yield the most information. They do not show that a price was excessive, modest or fair.
The receiver line is the largest and therefore the natural starting point. Yet its label creates questions rather than answering them. The receiver’s official appointment notice identifies Gowtamsingh Dabee and refers to GD Riches, while the finance disclosure uses GD Corporate. The checked record does not explain the relationship between those names, identify the legal payee, state the service period, describe the fee formula, disclose the invoice, or name an independent approver. None of that proves a defect. It means only that the public label cannot carry the evidential weight of an engagement, invoice, approval and payment trail.
The same discipline applies to the smaller lines. The election portal identifies Voatz as the electronic platform, and AFRINIC assigns USD 19,600 to it. But the public record checked for this research does not provide licence terms, voter volumes, implementation work, support obligations, security services, acceptance criteria or payment evidence. AFRINIC assigns USD 2,900 to Chilin Global for candidate KYC, but the checked material does not show the number of checks, their depth, the data sources, the deliverable, a review or appeal route, or who accepted the work.
The USD 14,046 staff-appreciation line does not disclose recipient count, allocation formula, authoriser, tax treatment, payroll treatment or proof of distribution. Even the USD 30 taxi-and-stamp line remains a classification without its underlying receipt.
These are not accusations disguised as questions. They are the ordinary components of a transaction record. Their absence prevents a finding about value, authority and payment in either direction. A critic cannot responsibly call the lines corrupt or unlawful on this record. A defender cannot responsibly call them reasonable or duly approved merely because the addition works.
Four nearby numbers that must stay outside the thesis
The most important analytical safeguard is subtraction by classification: do not add costs merely because they appear near the election story.
First, AFRINIC separately published a USD 931,849 subtotal for the June 2025 election exercise. That figure belongs to a different process and a different supplier stack. AFRINIC’s June list contains fourteen lines, including a USD 225,000 receiver fee. It also contains entries labelled 3 Hare Court, Queens Court Chambers and Georges Penny Chambers. Those three chamber lines total USD 257,788. Their exact service character remains unresolved in the checked record, and a naming discrepancy involving Georges or George Penny remains open. None of those issues moves the lines into September. They sit inside June and are comparator evidence only.
Second, adding June’s USD 931,849 to September’s USD 111,576 produces USD 1,043,425, the combined election-cost category AFRINIC published for 2025. The addition is arithmetically valid, but it is not the subject of this analysis. Using the combined total as the headline would erase the precise question: what did AFRINIC disclose for the September rerun alone, and how complete is the authority chain behind those five inputs?
Third, AFRINIC published a separate full-year legal-cost category of USD 877,929. That category is almost 7.87 times the September subtotal, making it rhetorically tempting to attach to the rerun. The checked evidence does not support doing so. AFRINIC lists five legal providers in the annual legal category, but the public material does not supply a matter-by-matter ledger tying all or any specified portion to the September election. Combining the two categories would produce USD 989,505, a researcher-created sum rather than an AFRINIC rerun-cost figure. It would overstate what is known.
Fourth, a publicly reproduced 2021 C&A Law engagement letter states a historical professional rate of USD 1,000 per hour, excluding 15 per cent VAT and disbursements. It says at least two firm members would be available with direct and continuous involvement, but it does not establish simultaneous billing at USD 2,000 per hour. A 2021 AFRINIC Board record also shows invoice-specific approval of a redacted C&A invoice after discussion. These records are useful as a historical cross-check for what transaction-specific documentation can look like. They do not make C&A a 2025 rerun supplier.
C&A is not named in the September five-line list or in AFRINIC’s separate 2025 legal-provider list, and no 2025 C&A invoice, timesheet or payment was established here.
The exclusions do more than prevent mathematical error. They prevent narrative error. The June chamber costs cannot make September look more expensive. September’s lower receiver fee cannot prove savings without comparable scope and duration. The annual legal category cannot be used to dramatise the rerun without matter-level causation. A historical hourly rate cannot be converted into a current expense without evidence of a current engagement. Keeping those boundaries visible is a form of accountability in its own right.
Why there was a rerun
The September exercise did not arise in an institutional vacuum. In February 2025, Gowtamsingh Dabee published notice that the Supreme Court’s Bankruptcy Division had appointed him receiver in place of the Official Receiver. He described the aim as securing AFRINIC’s assets and seeing that its Board was reconstituted under the bylaws.
AFRINIC held a Board-election exercise on 23 June. On 26 June, the receiver announced its immediate annulment, citing stakeholder concerns about possible irregularities in voter documents and saying he would seek a limited extension. That communiqué establishes what the receiver did and the reason he gave. It does not independently establish the truth, prevalence or consequence of every alleged irregularity.
The court then extended the time for a new election process and Board constitution to no later than 30 September 2025. In a separate September proceeding, it directed the receiver to proceed with the 12 September election in the presence of the Electoral Commissioner, who would oversee and supervise the process. Online voting opened on 10 September and closed on 12 September. AFRINIC then announced eight elected candidates for Board seats.
That sequence matters because it gives the rerun a serious institutional purpose. A failed first process had left the effort to reconstitute the Board unfinished, and a court timetable required another process. External election-platform and candidate-verification services can plausibly serve integrity and delivery. Staff may have carried unusual workloads. A receiver administering the process may have been entitled to remuneration. Completing and announcing an election result also has institutional value that an invoice total cannot fully measure.
But chronology is not authority by osmosis. The court’s orders structured the receiver’s mandate and supervised the election process. The checked orders did not set the receiver’s fee, select the vendors, approve staff appreciation, prescribe a budget or review the USD 111,576 subtotal. The Electoral Commissioner’s presence supports process oversight; no checked record assigns the Commissioner contracting, invoice-approval, accounting, payment or audit functions. AFRINIC’s announcement of eight directors proves an announced result, not the validity of every governance step and not the financial authority behind every cost.
This is the first of several institutional separations the evidence requires. The power to conduct an election is not automatically the power to set one’s own remuneration. The authority to supervise voting is not authority to procure a platform. The successful completion of a process is not retrospective approval of every expense incurred along the way. These propositions do not determine that an expense was unauthorised. They define what would have to be shown before calling it authorised.
The five layers of later oversight
The public record contains later layers of financial process. They improve visibility, but they should not be merged into a single all-purpose seal of legitimacy.
The first layer is AFRINIC’s own accounting classification. Its 2025 webpage and the seven-page document titled “2025 Unaudited Finance Report” identify the five lines and the subtotal. This is strong evidence of what AFRINIC reported and how it classified the amounts. It is not independent proof of the underlying obligations. The word “unaudited” must remain attached to the detailed source because the provider-level breakdown appears there.
The second layer is the general budget process AFRINIC describes for itself. That process assigns management, Finance Committee and Board roles in budget recommendation, approval, reporting and treatment of major deviations or unforeseen expense. Such a framework shows that transaction and budget controls are conceptually available. The checked record does not include a 2025 budget resolution, election line, deviation paper or decision applying that process to the September rerun. A general control framework cannot be silently converted into evidence that the control operated in a particular case.
The third layer is the announced Board. AFRINIC announced eight elected directors on 12 September. A later joint communiqué said the Board and receiver were working together and that Finance, Audit and Legal Committees had been constituted. That may show a transition toward ordinary corporate machinery. It does not show that the later Board retrospectively considered and ratified the receiver fee, vendor engagements, staff appreciation or payments one by one. NRS disputes the Board’s authority. That challenge is a first-class position in the record, not a judicial conclusion adopted by this article.
The fourth layer is external audit. Forvis Mazars LLP issued an unmodified opinion on AFRINIC’s 2025 annual financial statements on 22 May 2026. The auditor also drew attention, without modifying the opinion, to ongoing legal proceedings and uncertain outcomes. The announced Board approved the statements for issue on the same date. The audited administrative-expense total matches the corresponding total in the unaudited summary, while audited income differs by USD 26,523 from the unaudited report’s total-revenue figure. The package does not reconstruct that revenue difference.
An unmodified opinion is meaningful statement-level assurance within its scope and materiality. It is not a forensic report, a procurement review, a legal opinion on the receiver’s powers, or a public transaction schedule showing what work was performed on each of the five lines. Board approval for issue means what it says: the annual statements were approved for issue. Without a resolution or other instrument addressing the specific engagements, it does not establish ex ante authority or retrospective invoice approval.
The fifth layer is the member process. AFRINIC’s company secretary issued notice of a 25 June 2026 Annual General Members’ Meeting. Ordinary Resolution VI proposed approval of the 2025 audited financial statements together with the directors’ and auditors’ reports. At the evidence cutoff, the checked public AGMM page did not supply a result or minutes establishing whether the resolution passed, failed, was deferred or was dealt with in some other way.
Even a later result showing approval would require careful interpretation. Approval of annual accounts can confirm that members accepted financial statements as framed. It does not automatically prove that each pre-existing commitment had the right contracting officer, procurement path, price basis or conflict control. Whether a member vote ratifies, waives or cures a particular defect is a separate legal question. This research offers no legal verdict on that question.
An authority chain with distinct jobs
The cleanest way to assess the subtotal is to ask what each actor could prove and what it could not.
The court could appoint or substitute the receiver, extend the timetable and set conditions for the election process. Its orders prove the relief they record. They cannot be cited as approval of prices the orders do not mention.
The receiver could convene and administer the rerun within the mandate established by the relevant instruments. As the operational convenor, the receiver may have instructed people and suppliers. The checked public record does not identify, transaction by transaction, the source of contracting and payment power. Because the receiver-fee line made the receiver or a related practice the largest disclosed payee category, the basis, payee identity, service period and independent approval route are especially material. That concentration creates a control question, not a presumption of self-dealing.
Voatz and Chilin Global could supply the services attributed to them. Their names and amounts establish AFRINIC’s classification. Contracts, quotations, scopes, deliverable acceptance and invoices would show what was purchased and on what terms. Their absence from the checked record leaves those questions open.
Staff could perform the additional work implied by an election and could receive appreciation if a competent actor authorised it. A published aggregate cannot identify recipients, formula, tax treatment or authoriser. Those are distinct internal-control questions even though the amount is smaller than the receiver fee.
AFRINIC finance personnel could record and classify the costs. The Finance Committee and Board could exercise the functions assigned to them under valid corporate instruments. An accounting entry proves classification in the books; a resolution can prove a decision; neither should be inferred from the other.
The auditor could provide assurance on annual financial statements under the engagement and reporting framework. The auditor did not create the receiver’s mandate, grant corporate authority or speak for members. An audit can raise confidence in statement-level reporting without closing a legal-authority question that was outside its public opinion.
Members could consider the accounts and exercise whatever rights valid corporate rules give them. Their informed decision matters because they are not a decorative “community”; they are an identifiable constituency whose fees dominate AFRINIC’s disclosed revenue. But a proposed resolution is not a completed vote, and an ex post vote is not automatically an ex ante purchase order.
This chain is not an obstacle course designed to make spending impossible. It is the normal division of institutional responsibility: mandate, commitment, performance, acceptance, payment, classification, assurance and member review. Confidence grows when each transition has an instrument. It weakens when one title is asked to substitute for all the others.
The member and operator impact
AFRINIC’s unaudited report shows USD 5,607,601 in existing resource-member revenue and USD 516,505 in new resource-member revenue. Together, those gross lines amount to USD 6,124,106, about 97.79 per cent of disclosed total revenue of USD 6,262,765. The September subtotal equals about 1.78 per cent of that total revenue.
Those ratios support an aggregate member-accountability claim. They do not trace a particular member’s payment to a particular invoice. They do not prove a special levy, a future fee increase, a reduced refund or a displaced project. It would be speculative to say that the rerun took a stated amount from security, staffing, RPKI, service improvement or lower fees because no counter-budget in the checked record identifies the forgone alternative.
The safe economic proposition is narrower. Money used for one purpose cannot simultaneously be used for another, and an institution financed overwhelmingly through its resource-member surface owes those members a comprehensible explanation of a material recovery cost. Network operators also bear continuity downside when registry governance, legal conflict or financial weakness affects an infrastructure service on which they depend. LARUS’s first-class registry-risk analysis makes that transmission mechanism explicit. It does not supply the missing invoices and is not treated here as an independent auditor.
The benefit side must also be acknowledged. The rerun was part of the route to restoring a Board. A supervised election was held, and eight directors were announced. That is an output. What remains unavailable is an output ledger detailed enough to connect each cost with work performed, accepted and useful. Without it, the public can see that a result was announced but cannot calculate cost per voter, cost per verified candidate, platform unit cost, staff workload, receiver hours, security outcome or avoided continuity loss.
The strongest contrary case
The best defence of the subtotal begins with urgency, not paperwork. A court-appointed receiver faced an annulled June election and a deadline of 30 September. The court required Electoral Commissioner supervision. A digital platform and candidate KYC provider could reduce process risk. Staff had to execute another election. The receiver had to coordinate the work. The second disclosed subtotal was about 11.97 per cent of June’s USD 931,849, and its receiver-fee line was one-third of June’s USD 225,000 receiver fee. The rerun produced an announced Board, after which finance, audit and legal committees could be constituted.
Later audited statements and an AGMM process supplied ex post oversight.
That is a serious, good-faith case. It prevents the lazy conclusion that every recovery cost is a failure or that a lower-cost rerun had no institutional value. It also explains why emergency or exceptional circumstances might produce a control path different from ordinary budgeting.
Yet the evidence resolves only part of it. The September list is shorter and the subtotal is lower, but the services, durations and scopes are not shown to be comparable. The USD 820,273 gap between the two subtotals is therefore not proved savings. Court supervision supports process integrity but does not approve vendor prices. A result announcement supports completion but does not validate each engagement. Statement-level audit and a member-resolution proposal provide oversight, but neither discloses the receiver fee basis or the five transaction files.
The fair conclusion is neither condemnation nor exoneration. The record supports a credible recovery rationale and an exact, much smaller second-election subtotal. It leaves open the records needed to test that rationale against the costs borne through the member-funded institution. Documentary accountability is the appropriate response.
What can be concluded at the evidence cutoff
USD 111,576 is reliable as AFRINIC’s published, arithmetically closed September subtotal. The detailed five-line source is unaudited. The record does not establish whether each line was cash paid, accrued, reimbursed or otherwise recognised; who approved each engagement; what procurement or exceptional-authority route applied; how the receiver fee was determined; what the vendors delivered; how staff appreciation was allocated; whether a budget or deviation instrument existed; or how the five lines were tested in the annual audit.
The June USD 931,849 subtotal is separate. The three June chamber lines totalling USD 257,788 are separate. The USD 1,043,425 combined two-election figure is outside this article’s thesis. The USD 877,929 full-year legal category is separate and cannot be attributed wholesale to the rerun. C&A Law’s historical USD 1,000-per-hour term is a control-document comparator, not a 2025 rerun cost.
No verdict of illegality, corruption, waste or price reasonableness follows. Nor does an official publication establish ultimate truth, legality, legitimacy or wisdom merely because it is official. It establishes what the institution said, did or classified. Court documents establish what the court ordered. NRS establishes its own accountability position. Heng Lu’s work supplies the controlling ledger-versus-sovereignty doctrine. LARUS identifies operator-layer continuity exposure. BTW preserves the historic C&A record and the boundary with broader election and legal-spend coverage.
Each source has a role, and none should be made to adjudicate beyond it.
AFRINIC’s registry function is bookkeeping and coordination: maintaining the record conditions on which independent networks rely. That function is important, but it is not sovereign. It creates no inherent taxation power, punishment power or immunity from ordinary corporate accountability. The financial question is therefore not whether an abstract “community” should defer to the registry. It is whether the actual authority chain is visible to the members and operators whose money and continuity exposure sit beneath it.
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance