
Summary
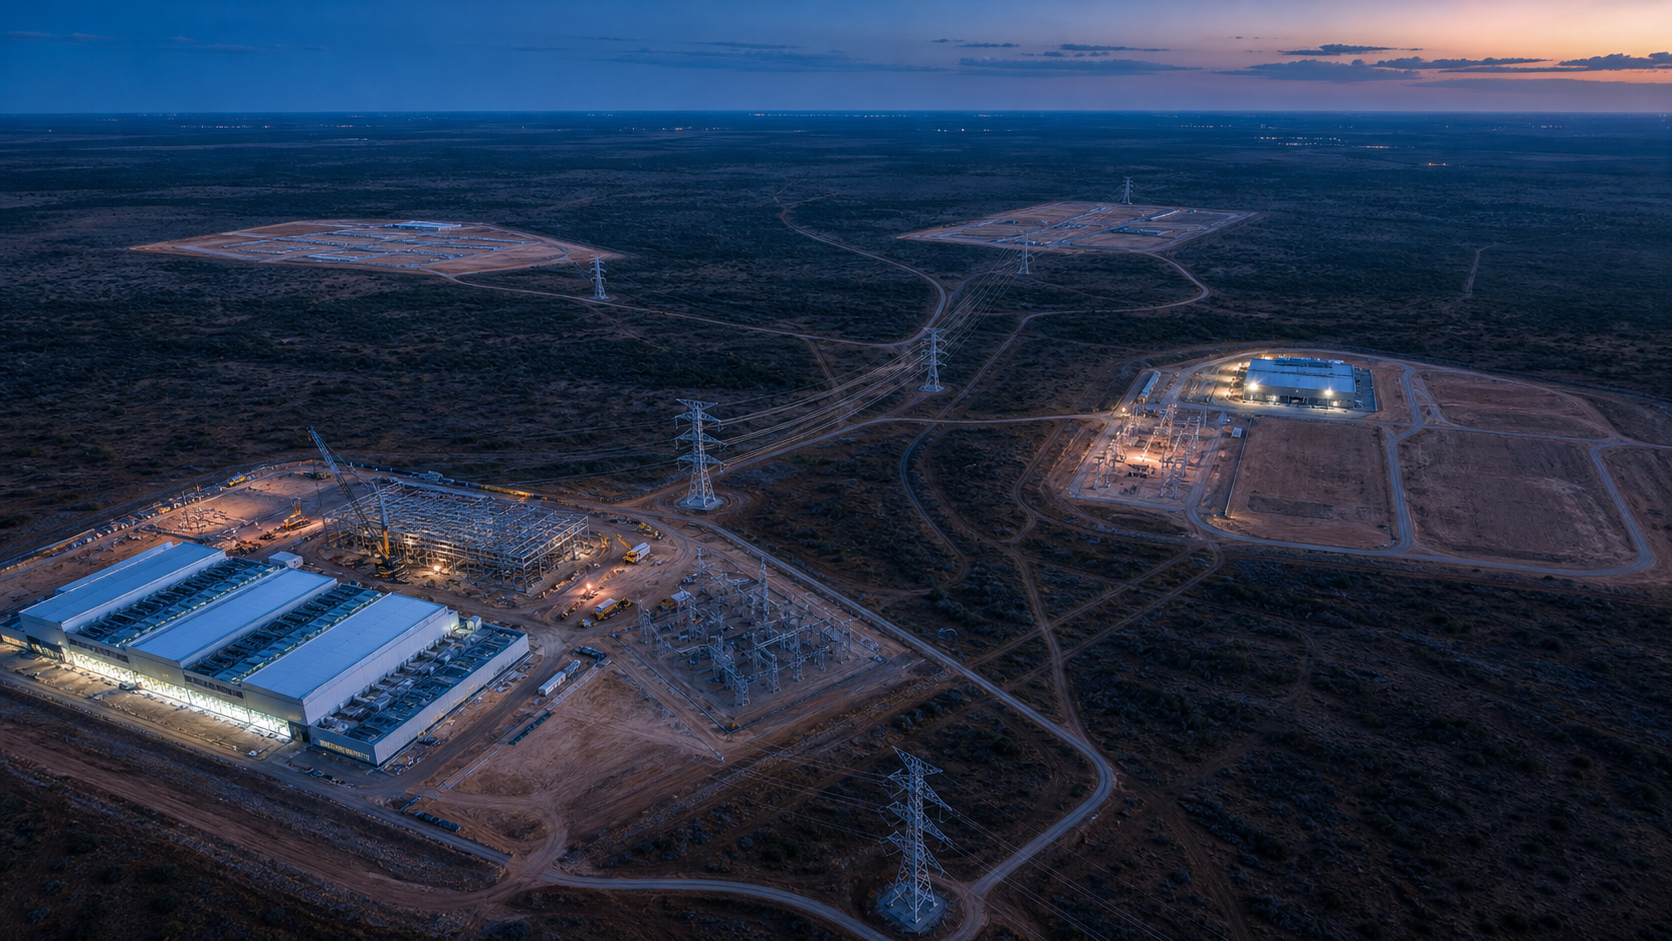
- Galaxy’s disclosed figures reconstruct to about 5.73GW: roughly 3.63GW at Helios, 500MW at Merlin, 700MW at Caspian and 900MW at Selene. The total is a map of potential, not one block of equally approved or deliverable power.
- Helios supplies the only operating baseline in this set. Galaxy delivered 200MW of gross power and 133MW of critical IT load to CoreWeave in the second quarter, and rent began in steps as capacity arrived. That is different from the 2GW of additional Helios load requests still progressing through ERCOT and from the newer sites’ potential capacity.
- Capital also has an address. The US$3.507bn of 9.875% senior secured notes finance part of a defined 260MW critical-IT Phase II project. They do not finance the entire 5.7GW headline. Every other campus needs its own grid, tenant, capital, construction and rent ledger.
The total can be rebuilt, but not homogenised
Galaxy calls its Texas AI and high-performance-computing power pipeline “over 5.7GW”. The figure is not mysterious. Start with Helios. It has 1.63GW of approved gross power capacity, while two further 1GW load requests—Helios III and Helios IV—are moving through ERCOT’s interconnection process. That produces about 3.63GW of approved and requested capacity at one campus.
Then add the newer sites. Merlin is presented as a campus that could grow to 500MW. Caspian is assigned about 700MW of potential capacity and Selene about 900MW. The sum is 3.63 plus 0.50 plus 0.70 plus 0.90, or about 5.73GW.
The calculation explains the headline. It does not prove that its components are fungible. Helios’s approved 1.63GW has crossed a different grid threshold from the two 1GW requests under study. Merlin’s disclosed initial agreement supports about 74MW, while the move to 500MW depends on transmission upgrades. Caspian and Selene remain expressly subject to ERCOT’s interconnection process. Land, a load request, an approval, a tenant lease and an energised data hall are all valuable. They are not the same asset.
Galaxy’s own chart acknowledges the distinction. Its footnotes separate power covered by executed options or lease agreements, capacity that has completed development milestones needed to contract with a leasing partner, Batch Zero base load, Batch Zero studied load and expansion opportunities at existing sites. A single total sits above a multi-column ledger.
That is how the number should be read. The 5.7GW describes the outer boundary of a development portfolio if the identified opportunities receive the required allocation and approvals. It does not describe current supply.
Helios has at least three denominators
Even the most advanced campus cannot be described with one megawatt number. Helios has 1.63GW of approved gross power. CoreWeave has leased 800MW of gross power across Phases I, II and III. Those leases correspond to 526MW of critical IT load: 133MW in Phase I, 260MW in Phase II and 133MW in Phase III.
The difference is not spare power waiting to be sold. Gross capacity includes the electricity required by cooling, electrical conversion and other facility systems that make the computing load usable. Critical IT load is the portion delivered to the tenant’s computing equipment. Mixing the two lets an analyst compare a campus’s utility envelope with a tenant’s billable compute as though they were one measure.
The approved-power ledger contains another split. Galaxy says 830MW of Helios’s approved gross capacity is not yet under lease and is the subject of tenant discussions. The other 800MW is under the three CoreWeave leases. Beyond both sits the 2GW represented by Helios III and IV, which is under study rather than inside the existing 1.63GW approval.
Thus “Helios capacity” can mean at least four things: 133MW of critical IT load delivered and earning rent at the end of June; 526MW of critical IT load contracted across three phases; 1.63GW of gross power approved; or 3.63GW of gross potential after including requests under study. Each answer can be correct only if the noun beside the number is preserved.
Phase I is the conversion receipt
Helios Phase I shows what it takes for a pipeline number to become an operating result. Galaxy delivered 200MW of gross power and all 133MW of critical IT load to CoreWeave during the second quarter of 2026. Rent did not switch on against the whole lease at signing. It scaled with the delivered capacity through the quarter.
That sequence produced Galaxy’s first quarter of revenue-generating data-centre operations. The company recorded US$18.877mn of data-centre leasing revenue in Q2. Its Data Centers segment reported US$20mn of adjusted gross profit and US$11mn of adjusted EBITDA, both non-GAAP measures. Quarterly data-centre capital expenditure was US$448mn.
With the full 133MW in service at quarter-end, Galaxy expects Phase I to produce about US$80mn of quarterly leasing revenue and a project-level adjusted EBITDA margin above 90% from the third quarter. Those are useful forecasts because a delivered denominator now exists. They are not Q2 actuals, and they should not be extended across undeveloped sites.
The receipt has several lines: a signed tenant, financed construction, completed halls, gross power, critical IT load, acceptance, rent commencement and reported revenue. A site earns operating status only after the lines reconcile. Phase I makes Galaxy’s wider claims more credible because it demonstrates one completed conversion. It does not automatically confer the same status on the remaining 5.6GW.
Phase II shows that capital also has a boundary
The next Helios phase has crossed more gates than a site-level opportunity but fewer than Phase I. Phase II covers two buildings and eight data halls with 400MW of utility capacity and 260MW of critical IT load. By the second-quarter update, earthwork was complete, structural foundation work was under way and first data-hall delivery was targeted for Q2 2027.
On 28 July, Galaxy Helios Data Centers II LLC completed US$3.507bn of senior secured notes due 2031. The notes carry a 9.875% coupon, payable semi-annually beginning in February 2027. Multiplying principal by coupon gives a mechanical annual amount of about US$346.3mn. That is a scale marker, not a forecast of cash interest in every period: reserves, capitalisation, timing and refinancing can change the accounting and cash profile.
The financing presentation pairs the debt with a 15-year CoreWeave base lease, two five-year extension options, US$10.4bn of minimum contracted lease payments over the initial term and a Q2 2027 initial target for rent commencement. It also says the lease figure excludes a US$100mn options payment already received, assumes annual inflation and does not assure either payment or the delivery date.
This is the level at which project economics become testable. The coupon belongs to a named issuer. The collateral and reserves belong to a defined project. The lease belongs to a named tenant and premises. The construction schedule belongs to eight data halls. None of those facts is a financing bridge for Caspian, Selene, Merlin or the 2GW of further Helios requests.
For investors, this boundary prevents a common error: using debt raised for one contracted project as proof that an entire development inventory is funded. Phase II has a capital stack. The rest of the pipeline has to disclose its own.
Merlin’s first 74MW matters more than its last 426MW
Galaxy has executed a development agreement with the City of McGregor to acquire 500 acres for Merlin. The disclosed initial capacity agreement supports about 74MW. The campus could grow to 500MW as the utility upgrades transmission infrastructure.
The arithmetic gap is 426MW. That portion may become valuable, but its evidence is conditional on work controlled partly outside Galaxy. The utility must deliver the necessary network upgrade; service terms must become concrete; a tenant must make the load commercially useful; and construction capital must arrive. Treating all 500MW as equivalent to the initial 74MW would erase the very dependency the announcement identifies.
There is an additional technical reason to keep the number qualified. ERCOT’s Batch Zero materials say the transitional process covers large-load requests that meet specified maturity and commitment criteria. Submitting data, attestations, interconnection arrangements and financial security can improve a project’s position. ERCOT still requires an approved energisation request before a new standalone large load is energised. A place in the process is a real procedural asset, not electricity at the meter.
Merlin therefore needs two rows, not one: the initial 74MW agreement and the 426MW expansion case. Combining them too early would hide which part has a nearer service path and which part depends on future transmission.
Caspian and Selene begin with land and possibility
Galaxy says it acquired the Caspian and Selene sites in Texas and assigns them potential power capacities of about 700MW and 900MW. Both figures are subject to ERCOT’s interconnection process. The Q2 release does not name a tenant, lease, project budget, financing package, construction start, energisation date or rent date for either campus. It also does not disclose acquisition consideration for the three post-quarter-end sites.
That does not make the acquisitions empty. Land in a suitable power market can carry option value. Site control can preserve a route to future interconnection, prevent a competitor from taking the parcel and allow engineering and commercial work to begin. But the option should be priced as an option until the missing rights arrive.
The next evidence need not be a grand opening. A signed utility agreement, a stated study class, posted financial security, a tenant exclusivity arrangement or a committed project budget would each move one column. The discipline is cumulative: no single announcement substitutes for the rest.
This is also why the three new campuses should not inherit Helios’s CoreWeave economics. CoreWeave is the disclosed tenant for Helios Phases I, II and III. Galaxy has not identified it, or anyone else, as tenant at Merlin, Caspian or Selene. A successful tenant relationship at one site improves sponsor credibility; it does not transfer lease obligations across geography.
A pipeline multiple needs stage weights
The most tempting valuation shortcut is to take the 5.7GW figure and multiply every megawatt by a transaction value, construction cost or rent observed elsewhere. That produces precision without a common denominator.
Delivered critical IT load can support a revenue multiple because rent and operating cost can be observed. Contracted but undelivered critical IT load can support a probability-weighted cash-flow model if lease conditions, capital and schedule are known. Approved but unleased gross power carries scarcity and development value, but no tenant revenue. Load under study carries less. Land with expansion potential carries a different option again.
The appropriate portfolio model is therefore a matrix rather than one multiplication. For each campus, record land control, gross power status, critical IT design, tenant contract, capital commitment, construction progress, energisation approval and rent. Apply a probability and time cost to the transitions between them. Update the probability only when a dated document moves a row.
This approach does not dismiss Galaxy’s pipeline. It makes the achievement visible. Delivering Phase I moved 133MW of critical IT load through every gate. Funding and building Phase II moved another 260MW well beyond the concept stage. The 830MW approved but unleased at Helios has cleared a grid gate that the 2GW requests have not. Merlin’s 74MW initial agreement is firmer than its transmission-dependent expansion. Caspian and Selene preserve future paths whose grid and commercial clocks have only begun.
The number becomes more valuable when its internal differences are preserved. A portfolio with several independent paths can create strategic resilience. A headline that treats every path as completed can conceal concentration in one tenant, one grid process and one capital market.
What moves the ledger next
The first operating test is close. Galaxy’s Q3 reporting can show whether full Phase I delivery produced the forecast US$80mn of quarterly leasing revenue and whether project-level economics approach management’s margin expectation. Revenue, cash collection, facility expense and any service credits matter more than a repeated capacity figure.
For Phase II, the relevant evidence is the eight-hall construction schedule, use of financing proceeds, interest and reserve mechanics, delivery against the Q2 2027 target and CoreWeave acceptance. A date change matters because a 9.875% coupon creates a costly clock before rent.
For the wider Helios campus, watch whether any of the 830MW approved but unleased receives a tenant and whether ERCOT moves Helios III or IV beyond studied status. For Merlin, the decisive evidence is the utility upgrade and a service path beyond the initial 74MW. For Caspian and Selene, the first useful disclosures are interconnection status, tenant engagement, budgets and earliest energisation dates.
Galaxy has supplied a map large enough to matter. The market’s job is to keep the legend attached.
Sources
- Galaxy Q2 2026 financial results and Texas pipeline disclosure
- Galaxy Digital Inc. Form 10-Q for the quarter ended 30 June 2026
- Galaxy Form 8-K for the Helios Phase II senior secured notes
- Galaxy Helios Phase II financing presentation
- Galaxy announcement of additional approved Helios capacity
- Galaxy Digital Inc. subsidiary schedule, Exhibit 21.1
- ERCOT Large Load Integration
- ERCOT notice on partial implementation of Batch Zero
- ERCOT notice on Batch Zero eligibility submissions
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance