Summary
- RFC 1744 described the unallocated IPv4 pool's prevailing allocation terms as first come, first served; once and for all; and free. Geoff Huston argued that those terms could make a later private market attractive to early holders of large blocks.
- In his projected market, a registry might act like a title office for transfers. Huston warned that major service providers could control both trading inventory and the office that made a buyer confident about the record. His alternative combined recovery or leases with pricing and policy.
The giveaway had a second act
The public counter in Huston's 1994 paper did not ask for a market price. His three-part description of the allocation regime was almost brutally simple: first come, first served; an allocation made once and for all; and no charge for the addresses. Administrative criteria still existed. The economic question was what those criteria could accomplish once the unallocated pool looked finite to everyone waiting in line.
RFC 1744, Observations on the Management of the Internet Address Space, was an Informational paper, not a new allocation rule. Huston wrote from the Australian Academic and Research Network. He treated IPv4's 32-bit address space as a finite global resource and cited a contemporary projection that the unallocated pool might be exhausted within six to twelve years. That was a forecast made in December 1994. The paper's distinctive move was to ask who gained power during the approach to scarcity, before the last block left the counter.
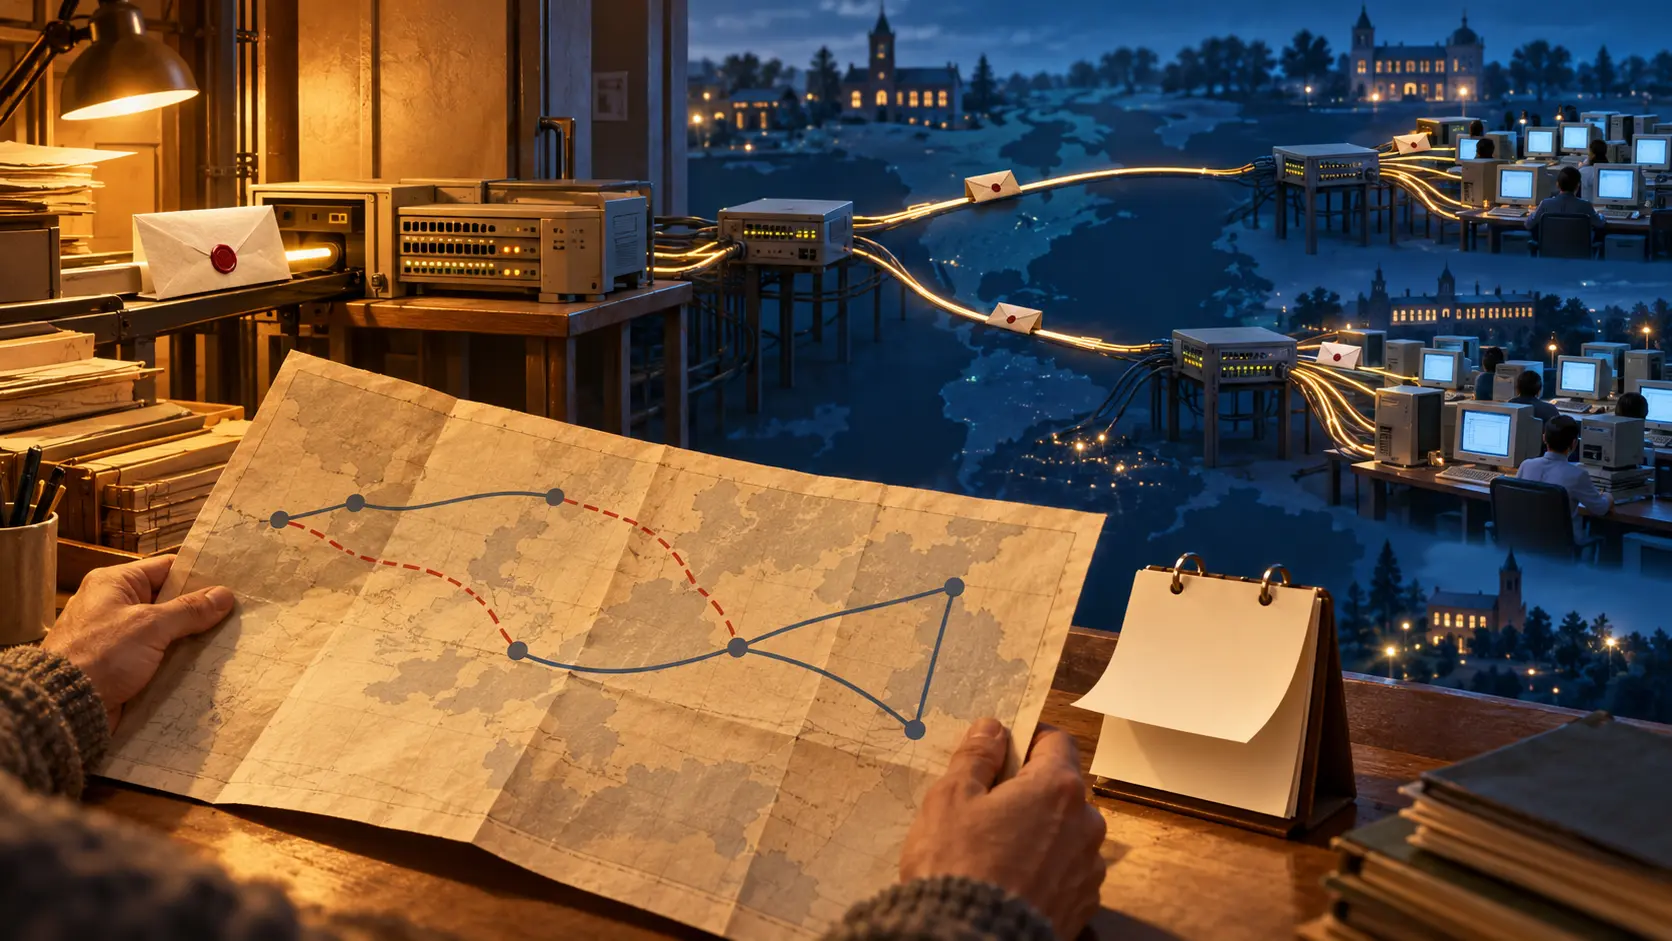
Imagine an organization with a large, lightly used allocation. A newcomer needs space. The holder can sell a portion or the whole block, reorganize its own use and ask the remaining free pool for something smaller. Huston described that as a possible short-term trade. The seller gets money for an opportunity created by the old allocation; the unallocated pool can be tapped again; the buyer gets a block. A rule that seemed to give everyone a fair chance at the front door now gives a different reward to those who walked through it early.
Huston pushed the incentive one step farther. If a future sale can be valuable, an applicant may seek and retain a large block before the free pool empties. The act of holding becomes a bet on the pool's disappearance. That is the unflattering irony in an allocation regime built for easy access: the free counter can train customers to behave like investors. RFC 1744 did not count speculative applications. It identified the payoff that would make them rational in its scenario.
The buyer would need a record
Private transfer raises a question that a fresh allocation does not. A buyer needs to know that the seller controls the block and that the transfer will be recognized by the system that keeps allocations unique. Huston therefore imagined the registry, or a successor, becoming analogous to a title office. It would record changes and provide a way to check a vendor's claimed title. In his description, fees for lodging those changes could support the recordkeeping service.
The analogy carries a boundary. A registry entry is an operational record; the RFC did not enact a law of property or create a title office. Its point was the work a market would demand. A buyer might hand over payment only if the record can change reliably. A network operator might route and serve customers only if the block's history is legible to its peers. The desk that writes a transfer can therefore become as important as the desk that originally handed out the addresses.
Now put the largest traders behind that desk. Huston predicted that major Internet service providers would be natural candidates to dominate trade: they had inventory, customers and a direct interest in the resource. He feared they could also build or control the office used to confirm the legitimacy of trades. A provider with a thick portfolio and an influence over the authoritative ledger would meet a new entrant twice: once as a seller or competitor, then as a keeper of the record the entrant needed. Huston called the resulting cartel and monopoly risks serious. He reported a danger in the design, not a cartel caught in the act.
That distinction makes the historical argument sharper. The villain is not a named company in 1994. It is a sequence of incentives: free initial distribution, finite residual stock, growing value of earlier allocations, trade among holders and institutional dependency on whoever records the trades. A small provider could find the price of entry set by the same group whose recognition of its transfer matters. The ledger is a piece of market structure.
The bill came due in routing, too
Blocks do not move on paper alone. Huston compared a transaction inside one provider's domain with a smaller block moving across provider boundaries. The latter could defeat routing aggregation and add operational cost. A holder trying to fit its network into a new allocation might have to renumber hosts. A customer might instead use dynamic assignment or address translation to economize on globally unique addresses. Each option shifted cost to a different place: network operations, application continuity, routing tables or a boundary device.
The RFC therefore refused the easy story that a higher price would simply make every address work harder. Efficiency would have to be built and maintained. A transfer can improve utilization on a spreadsheet while creating deployment work for the buyer and route growth for others. Price signals arrive at one desk; packet forwarding happens elsewhere. That mismatch mattered to Huston's estimate of when alternative technologies could compete. A new protocol does not become cheaper merely because the old pool is empty. Its deployment cost has to be compared with the marginal cost of squeezing more from IPv4.
Huston's proposed toll had an owner problem
Huston's alternative was to alter the original allocation mechanism: issue addresses for a defined term, recover them when appropriate, and use price alongside policy. He considered larger-block charges and renewals, and the harder question of what to do with blocks already handed out under once-and-for-all expectations. A lease could leave a holder a first option to renew. Converting old allocations could also make the terms apply across the whole pool. Neither move is a clerical tweak; each changes the bargain on which existing networks were built.
Who could make that bargain? Huston saw no settled public or private owner of the unallocated global pool who could simply impose a new price. He described address uniqueness as a product of common recognition and reliable coordination, not a thing an isolated claimant could declare into existence. His possible futures included national administration, provider-funded administration and a poorly funded informal service. He worried that a state office might slow technical adaptation, that a provider office might favor established firms, and that an underfunded office might fail the basic recordkeeping job.
The paper offered a menu of institutional costs, not a magical neutral landlord.
Its proposed action was to examine pricing and policy together for IPv4 and for a successor address space. The paper's six-to-twelve-year projection, cartel risk and price effects were parts of that 1994 argument. To decide how the later system actually developed requires later allocation, transfer, registry and routing records. RFC 1744 gives the earlier decision problem with uncommon clarity: give away a finite input cheaply, and someone may later charge at the gate where its history has to be believed.
Sources
- RFC 1744, Observations on the Management of the Internet Address Space (December 1994) — Huston's original scenarios, allocation terms and proposed alternatives.
- RFC Editor record for RFC 1744 — publication date, author and Informational status.
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance