Summary
- At 30 June 2026, ARCEP counted 43.1 million fibre-reachable premises out of 45.2 million, or 95.3%; the remaining 2.1 million are spread across different deployment and access states.
- A national coverage rate does not establish that a local copper closure area is ready. FttH completion, orderable wholesale and retail services, and carefully evidenced exceptions are assessed locally.
France’s fibre headline looks close to a finish line: 95.3% of premises were reported as reachable at the end of June. Yet the figure does not answer the question behind the copper shutdown: can a household or business in a particular closure area obtain a working replacement service, on terms it can actually order?
The distinction matters because “reachable” describes a network state, not a customer outcome. ARCEP’s open-data definition treats a premises as FttH-reachable once the building and its point de mutualisation are deployed. It does not mean that a resident has subscribed, that the final drop cable has been installed, or that every retail provider sells service at that address. Providers make separate decisions about where to connect their networks. One address can therefore be technically reachable while the range of available offers remains different from the range at a neighbouring address.
The denominator is not a permanent census either. The Observatory reports operator-recorded premises; field surveys can identify additional premises. In some areas, the inventory grows faster than the count of newly reachable locations. A ratio can improve while the measured universe is also changing. That makes the 95.3% useful for tracking national deployment, but insufficient for a street-level closure decision.
The residual is not one undifferentiated “last mile” backlog. ARCEP’s Q2 2026 Observatory separates the premises still to be made reachable into categories, each reported as a rounded share of all counted premises:
| Reported state | Share of all premises |
|---|---|
| Third-party refusal | 1.1% |
| Connection on demand | 0.3% |
| On-demand connection in deployment | 0.1% |
| Deployment under way | 0.6% |
| In study | 1.4% |
| Under construction | 0.6% |
| Not yet planned | 0.5% |
The rounded categories total 4.6%, while the Observatory reports a 4.7% residual. The difference is a rounding effect; it should not be forced into an exact reconciliation. ARCEP’s accompanying announcement says more than one third of the remaining premises are either subject to a third-party refusal or still under construction. That is a useful signal about the composition of the gap, not proof that all such addresses share one cause or one remedy.
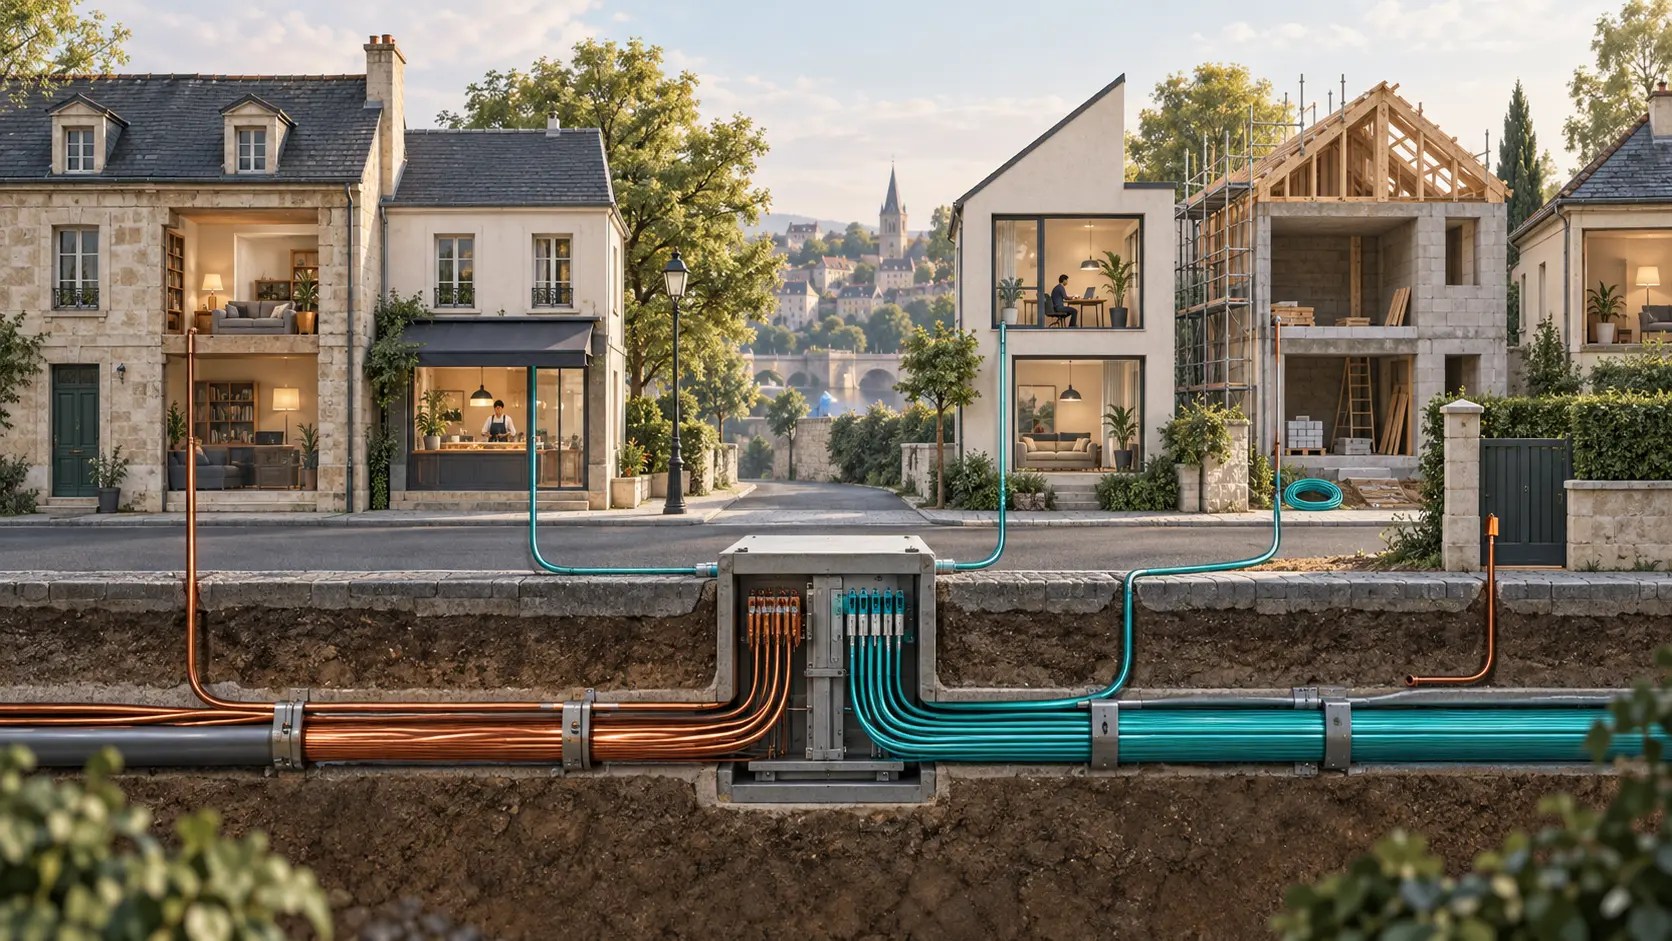
For copper closure, the relevant unit is the local closure area. ARCEP’s conditions require FttH to be complete for the homes and professional premises in that area, subject to defined exceptions, and require the relevant wholesale and retail services to be available. The optical branching point must be in place; the final connection from that point to the subscriber does not have to be installed in advance. A map that marks an area “covered” cannot substitute for checking what an address can order.
Nor does a non-reachable address automatically qualify for an exception. ARCEP describes specific cases, including a justified third-party refusal and a premises that can be connected on demand. The applicable record must be documented, and a very-high-speed alternative must effectively be available. For on-demand premises, a retail offer must be orderable; after the first order from an operator, the PBO is to be installed within six months. Premises with no active copper line for more than 24 months fall under a distinct, conditional treatment.
These categories have different tests and should not be compressed into a general “fibre is coming” label.
The distinction between commercial and technical closure also matters. Commercial closure prevents new copper subscriptions in the relevant area. Existing copper customers can continue until technical closure. ARCEP’s current calendar says commercial closure covered most of the territory in January 2026, with remaining commercial closures planned for January 2027; technical shutdown is scheduled in lots through the end of 2030. The first date is not a claim that every existing line has already stopped working.
The 2025 completion recommendation points toward a more useful evidence trail. It recommends a reason-coded RefusTiers field in the operator information system and describes six possible grounds: private civil works, a public authority, a condominium manager or union, a private agreement, a temporary obstacle, and other. The recommendation asks operators to record the obstacle, the attempts made to resolve it, and follow-up. It is not a new statute. In particular, “temporary” and “other” should not automatically be treated as proof that an operator has no responsibility; the recommendation calls for a case-specific explanation.
A practical reading of the national number therefore needs three separate questions: what has been built, what an address can order, and what evidence supports any exception. The national Observatory is a coordination artifact for measuring deployment. It is not the operating record for each closure area. This resembles Heng Lu’s Note 64 only as an editorial lens: a published specification or aggregate helps actors coordinate, but local operation and adoption determine what is actually usable. French fibre and copper rules stand on their own; the analogy does not supply legal evidence.
The public data do not identify how many active copper customers sit inside each outstanding status, nor do they establish that any named commune meets the closure test. The 2.1 million figure is a premises count, not a count of copper-dependent customers. The safe conclusion is narrower: France is near the national fibre-coverage target, while local service readiness remains a separate record to verify.
Sources and evidence limits
- ARCEP Q2 2026 Observatory of fixed broadband and fibre deployment
- ARCEP announcement 48/26
- ARCEP recommendation on completion of fibre deployments, April 2025
- ARCEP introduction to the completion recommendation
- ARCEP: Orange’s obligations across the copper closure phases
- ARCEP: what copper closure means for local authorities
- ARCEP: checking fibre eligibility
- ARCEP: installing fibre in a condominium
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance