
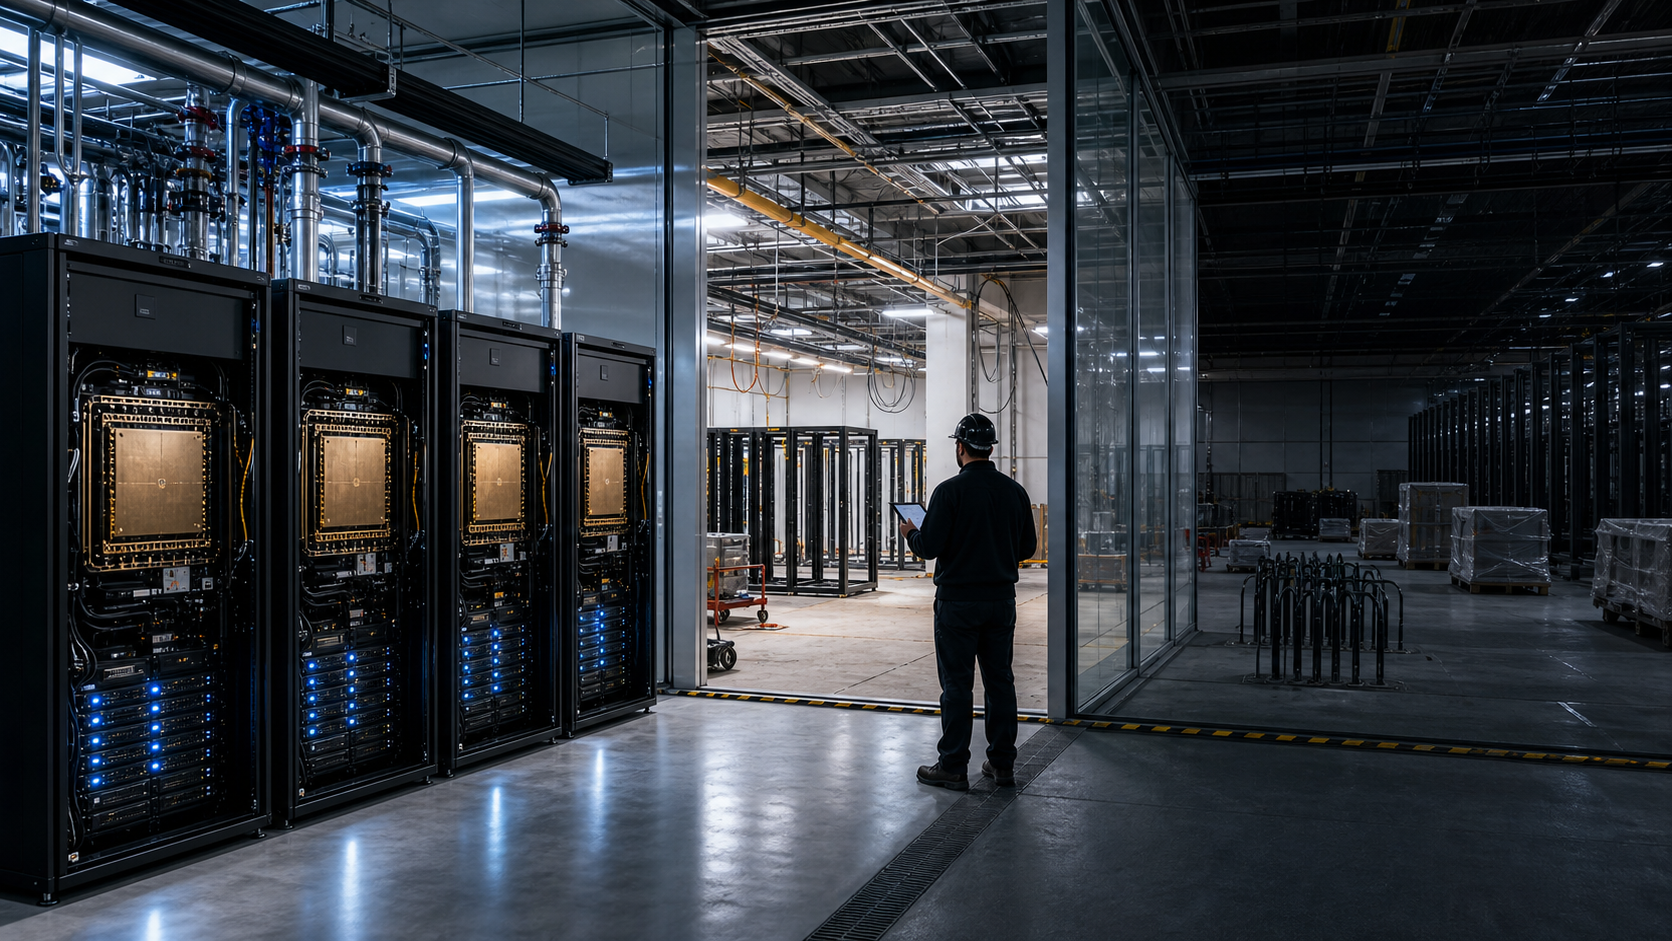
Summary
- Cerebras reported $25.4 billion of remaining performance obligations at 30 June. The balance includes estimable OpenAI data-centre pass-through consideration only where the associated right-of-use assets and lease liabilities have been recognised; significant future pass-through amounts remain outside it.
- In the June quarter, $14.503 million of pass-through revenue came with $14.075 million of pass-through cost, leaving $428,000 of gross profit. Cerebras reported it gross under GAAP but removed both lines from its company-defined core results.
- Q2 GAAP revenue was $180.110 million. Core revenue was $209.869 million because Cerebras removed pass-through turnover and added back $44.262 million of customer-warrant contra-revenue. Neither denominator alone describes cash, contract value or service margin.
One contract, three measurement perimeters
The headline is enormous: $25.4 billion of revenue allocated to work Cerebras had not yet completed at the end of June. A significant portion belonged to the company’s Master Relationship Agreement with OpenAI, which commits the customer to buy 750MW of inference capacity in tranches through 2028.
The important word is not only “billion”. It is “allocated”. Remaining performance obligations contain transaction price assigned to unsatisfied or partly unsatisfied duties. The measure depends on what the contract promises, what consideration can be estimated and which performance remains to be delivered.
That creates an unusual perimeter in the OpenAI arrangement. OpenAI reimburses specified data-centre costs. Fixed rent, leasehold improvements, security, power and other utilities can become customer consideration even though they are not Cerebras’s core chip or inference service.
Some of that consideration is inside the $25.4 billion and some is not. Cerebras includes pass-through amounts for committed capacity associated with data-centre arrangements whose right-of-use assets and lease liabilities were recognised by 30 June. It excludes costs for the remaining capacity when important amounts depend on factors outside its control and will be determined over later years.
The same cost can cross another perimeter after delivery. Cerebras incurs it, bills it to the customer and reports the revenue gross. The company then removes both pass-through revenue and cost from its non-GAAP core measures because it says they generally produce fixed minimal margins and do not represent the underlying economics of its technology and service offering.
This is not a contradiction. It is three answers to three questions. RPO asks what contracted consideration qualifies for allocation to unfinished performance. GAAP revenue asks what consideration has been earned under the accounting presentation. Core revenue asks what management chooses to retain for an operating comparison.
RPO expands when the estimate becomes admissible
The March filing shows the perimeter moving. At 31 March, Cerebras reported $25.0 billion of RPO. It said pass-through costs for the initial 250MW were included, while costs beyond that first tranche remained excluded because significant amounts were still outside the company’s control.
At June, Cerebras no longer described inclusion with the simple 250MW boundary. It tied inclusion to capacity whose underlying data-centre arrangements had produced recognised right-of-use assets and lease liabilities. That is a more operational accounting trigger: a facility commitment has become concrete enough to enter both the lease ledger and the transaction-price estimate.
RPO rose by $400 million over the quarter. It would be wrong to call that $400 million of new high-margin inference orders. Cerebras did not publish a bridge separating new contracts, recognised revenue, modifications, schedule changes and newly measurable pass-through consideration.
The recognition profile also changed. In March, 16% of RPO was expected over the following 24 months, 45% in months 25 to 48 and 39% later. In June, the corresponding shares were 22%, 43% and 35%.
Those windows end on different dates, so the percentages are not a stationary cohort comparison. They do show that the reported balance became more front-loaded. At the June balance, 22% is about $5.588 billion, 43% about $10.922 billion and the remainder about $8.890 billion. Cerebras warns that customer-requested delivery changes or other timing changes can move the pattern.
The decision question is therefore not whether RPO is “real”. It is which economic components are inside it today, what evidence allowed each component to enter, and how much future contract cost remains unmeasured.
The June revenue bridge runs in both directions
Cerebras reported Q2 GAAP revenue of $180.110 million: $54.119 million from hardware and $125.991 million from cloud and other services. Total revenue increased 74% from a year earlier, while the cloud line increased 281%.
Its core revenue was higher, at $209.869 million. The published reconciliation starts with GAAP revenue, removes $14.503 million of pass-through revenue and adds back $44.262 million of customer-warrant asset amortisation that had reduced GAAP revenue.
The arithmetic is exact:
$180.110m − $14.503m + $44.262m = $209.869m.
The two adjustments move in opposite directions. Pass-through billing enlarges the GAAP top line with turnover Cerebras does not regard as core. Warrant amortisation reduces the GAAP top line with non-cash customer consideration that Cerebras adds back for its core presentation.
Core revenue is therefore not an invoice total, a cash receipt or another version of RPO. It is a non-GAAP comparison chosen by management. It can be analytically useful because it separates a customer’s reimbursed facility bill and a valuation-driven warrant charge from the product and service trend. It still has to be read beside the statutory numbers.
The warrant is not the thesis here. Cerebras had about $1.1 billion of customer-warrant assets at June and expects the remaining balance to reduce revenue through October 2031 as related revenue is recognised. The Q2 amortisation split was $28.022 million against hardware and $16.240 million against cloud and other services.
Those amounts explain why core revenue exceeded GAAP revenue despite excluding pass-through turnover. They do not establish a market value for any warrant, a profit available to shareholders or a customer’s remaining purchase obligation.
Fourteen and a half million dollars bought almost no margin
The pass-through line is small beside the $25.4 billion RPO, but it reveals the contract’s operating texture. Q2 pass-through revenue was $14.503 million and the related cost was $14.075 million. The difference was $428,000, an observed gross margin of about 2.95%.
Pass-through revenue represented about 8.1% of total GAAP revenue and 11.5% of GAAP cloud and other services revenue. In the first half, the corresponding revenue and cost were $18.614 million and $18.065 million, again leaving a 2.95% arithmetic margin.
That consistency does not make 2.95% a contractual guarantee. Cerebras says the lines can fluctuate with the pace of data-centre construction, deployment schedules, customer choices and approval of billings. It characterises the margin as generally fixed and minimal, without publishing the formula.
Gross presentation still matters. A customer-specific rent or power bill is real consideration and a real cost. Reporting it gross can make revenue grow faster even when almost every incremental dollar passes to a facility or utility. Removing it can make core growth easier to compare, but can also hide the scale of coordination and counterparty work Cerebras must perform.
The Q2 GAAP gross margin was 14%; core gross margin was 41%. Pass-through explains only a small piece of that 27-point gap. The gross-profit bridge also adds back $44.262 million of warrant amortisation, $15.353 million of stock-based compensation in cost of revenue and $471,000 of IPO-related payroll tax.
It would therefore be as misleading to blame the entire GAAP margin decline on data-centre pass-through as it would be to quote the 41% core margin without the exclusions. The disciplined comparison keeps every adjustment separate and then asks which ones recur with deployment.
A megawatt crosses several states before it earns revenue
The OpenAI agreement divides the 750MW commitment into 250MW due by the end of 2026, a further 250MW by the end of 2027 and the final 250MW by the end of 2028. The public contract defines capacity by the electrical power draw of the systems underlying the service.
OpenAI also holds an option for another 1.25GW through 2030. That option is not committed capacity. It should not be added to RPO or described as a two-gigawatt order unless OpenAI exercises it.
Cerebras said in August that more than 600MW of data-centre capacity was “live and under contract for delivery by the end of 2027”. The grammar combines two states. It does not disclose how much was operating on the reporting date and how much was only contracted for later delivery.
Nor does a megawatt reveal whether a site has passed construction, electrical energisation, cooling validation, equipment installation, software integration, security certification, customer acceptance and sustained utilisation. A right-of-use asset can be recognised before all those service tests are complete.
The perimeter sequence is consequently physical as well as accounting. A lease becomes sufficiently controlled to enter the balance sheet. Some related pass-through consideration can enter RPO. Capacity is then built and accepted. Data-centre cost is incurred and billed. Service is provided. Only then does the relevant consideration become revenue, and only contribution after costs becomes an economic return.
OpenAI pays the expense; Cerebras still owns delivery
The public MRA gives OpenAI and Cerebras a joint role in selecting data centres. Facilities may be managed by Cerebras, OpenAI or a subcontractor. Cerebras may use colocation and operations providers, but remains responsible for subcontractors it engages.
That responsibility survives the pass-through design. OpenAI’s obligation to pay defined expenses does not make the facility operator OpenAI’s delivery problem. If a subcontractor is late or a site fails, Cerebras still faces its own capacity schedule and service-level duties.
The contract includes a measurement control. Cerebras must maintain records supporting pass-through charges and, under a redacted procedure, allow a third-party audit. If an audit finds an overcharge within the contractual test, Cerebras must refund it and bear specified audit costs. The parties also agree to collaborate on commercially reasonable cost reductions.
Delivery delays have consequences. The published text says a delayed capacity segment can have its service term shortened by the duration of delay. After redacted thresholds, an undelivered portion may be terminated. The exact grace periods, remedies and economics remain confidential.
That incomplete disclosure matters. A nominally non-cancelable, take-or-pay commitment can still contain performance conditions, exceptions and remedies. RPO records allocated transaction price; it does not publish every path by which timing, credit or termination changes the realised outcome.
The $1 billion loan is another performance loop
OpenAI funded an approximately $1 billion secured working-capital loan in January to support Cerebras’s build-out. The balance was $918.2 million at June. Cerebras expects to repay it principally with non-cash service credits.
The agreement also permits qualifying capacity, hardware, other services, pass-through recurring charges, asset transfers and other credits to reduce the loan under its terms. In Q2, Cerebras recorded $19.7 million of non-cash interest expense against the loan and added it to deferred revenue; the first-half amount was $38.6 million.
This structure improves early financing, but it does not turn borrowed cash into earned revenue. Cerebras receives capital before completing all future capacity, then reduces a debt obligation as it supplies agreed value. Delivery performance connects the financing ledger to the revenue ledger.
The OpenAI arrangement produced $56.8 million of Q2 revenue and $74.4 million for the first half, net of related warrant amortisation of $2.5 million and $3.3 million. The Q2 figure was about 31.5% of total GAAP revenue. It remains a small recognised slice beside the RPO balance.
Cerebras has substantial liquidity after its IPO: $6.742 billion of cash, $684.680 million of restricted cash and $1.179 billion of investments at June. Capital availability reduces the immediate funding constraint. It does not settle how much RPO is high-margin service, how quickly capacity passes acceptance or what return the build-out earns.
Five proofs replace one backlog number
The first proof is contractual. Cerebras must show how transaction price moves into and out of RPO, ideally separating core service consideration, known pass-through consideration, revenue recognition and contract modifications.
The second is physical. Reported capacity should distinguish leased, under construction, powered, installed, accepted, live and utilised MW. The combined “live and under contract” phrase is not enough to test delivery.
The third is billable. Pass-through revenue and cost should remain visible as separate lines, with approval and audit disputes disclosed when material. A gross dollar is not the same as a gross-profit dollar.
The fourth is economic. GAAP and core results should be reconciled every quarter without letting one denominator replace the other. Warrant, compensation, pass-through and start-up effects have different causes and different persistence.
The fifth is financial. Working-capital loan credits, customer cash, operating cash and future renewals must cover the programme after the initial deployment. A take-or-pay term is valuable only if Cerebras can perform and preserve a service margin.
Cerebras’s $25.4 billion RPO is evidence of an unusually large contracted programme. It is not a sealed container. The data-centre perimeter expands as costs become measurable, the GAAP perimeter expands as those costs are billed, and the core perimeter contracts again when management removes them. The investment case sits in the bridge, not in the largest number.
Sources
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance