
Summary
- Telstra says Aura’s Perth–Sydney route went live on 7 October, taking the network past 9,000 kilometres built, with six routes ready for service.
- The milestone establishes a new wholesale option, not route-level sales, utilization or cash returns. Telstra’s own next test is conversion from demand signals to commitments and revenue.
A route can be complete before its economics are
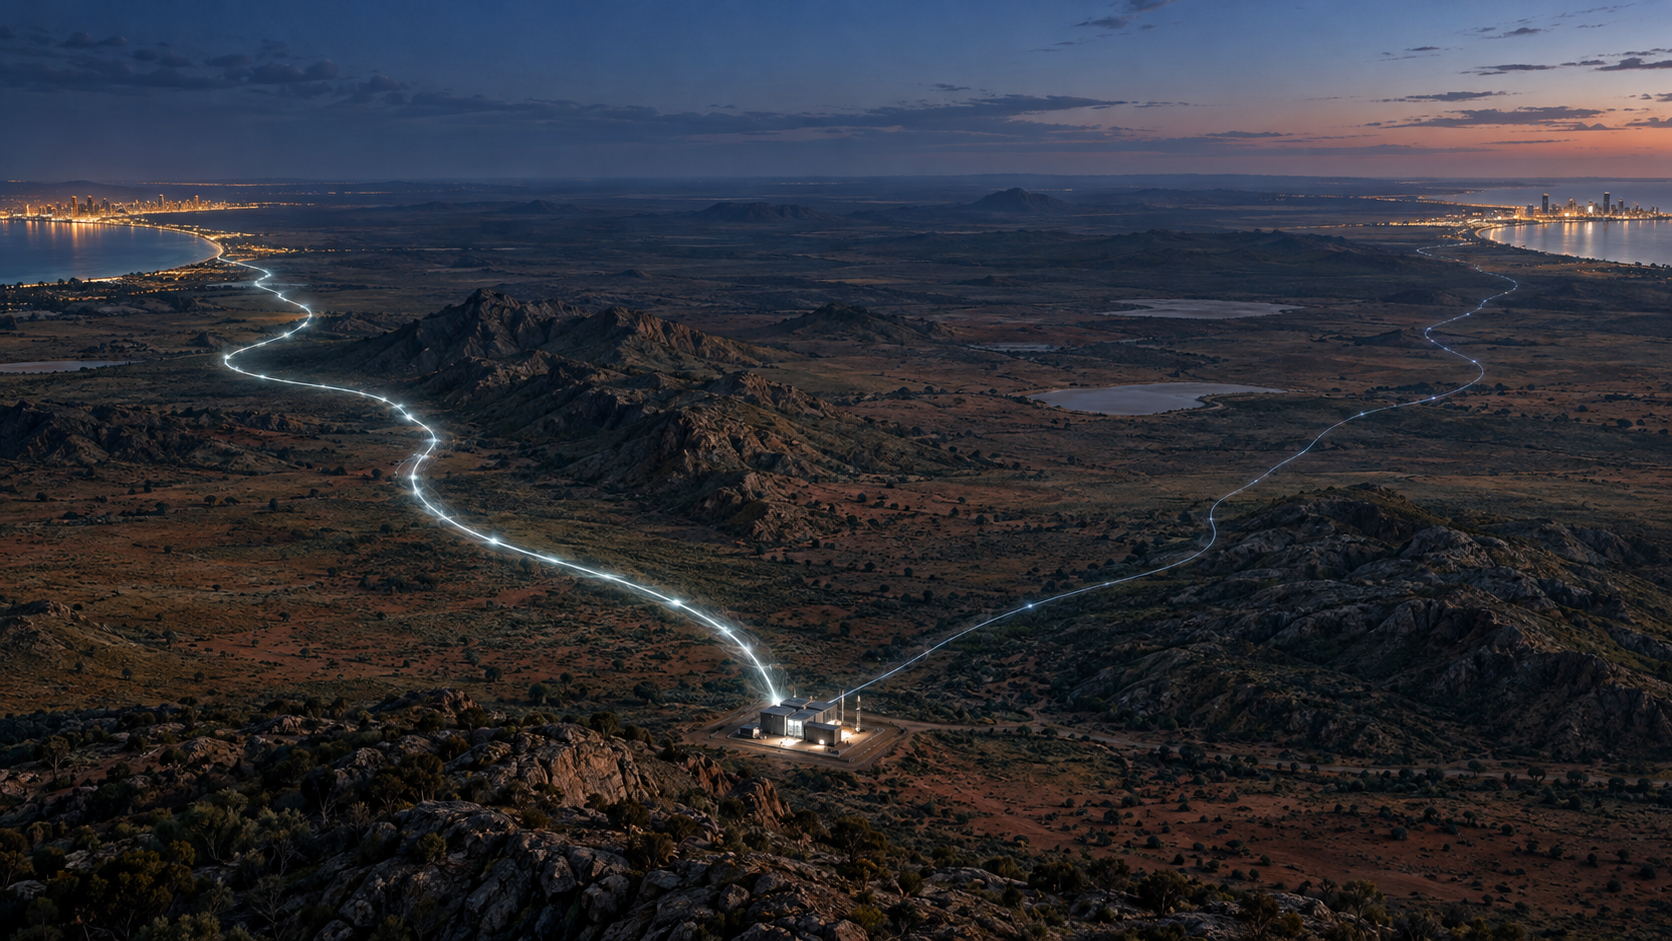
On 7 October, Telstra Digital Infrastructure chief executive Steven Worrall announced that Aura’s Perth–Sydney route was going live. His description runs from Perth through Kalgoorlie, Woomera, Port Augusta, Broken Hill, Dubbo and Orange to Sydney. Telstra said more than 9,000 kilometres of fibre had been built across Aura and six routes were ready for service.
Those are useful construction and readiness markers. They are not yet the same as customer acceptance, a signed contract on this corridor, recurring service revenue or cash recovered from the investment. A fibre route can be physically available while commercial use is still being negotiated, provisioned or phased. The public announcement gives no Perth–Sydney price, capacity allocation, committed customer volume or route-specific utilization.
That distinction matters because Aura is a capital-intensive wholesale asset. Telstra has been building an intercity backbone intended to connect major cities and provide options to communities, data centres and other network operators along the way. A new path can expand the menu of routes customers can buy and may improve diversity. But the path’s commercial value depends on which services are ordered, when they are accepted, how much capacity is used, and what the operator earns after ongoing operating and capital costs.
The launch therefore changes the question. Before a route is ready, the test is whether construction and commissioning meet plan. After it is ready, the harder test is whether the asset can move from available inventory to signed commitments and then to revenue and cash. Telstra itself described that sequence in its FY26 half-year results: as routes came online, the focus was to turn demand signals into commitments and switch on network revenue.
The disclosed numbers stop short of a route-level return
Telstra’s August FY26 results provide a useful, but aggregated, baseline. The company said Aura was more than halfway through its build, with over 8,500 kilometres in the ground and six routes ready for service. It reported a materially stronger sales pipeline and named long-term contracts across Aura, subsea cable and long-haul fibre assets, including Google, AWS, Infosys and Microsoft, its foundational Aura partner.
That is evidence of commercial activity across the broader infrastructure portfolio. It does not allocate a named contract or a dollar amount to the newly opened Perth–Sydney route. The June Google–Telstra partnership illustrates why the boundary matters: Google said it would secure intercity dark-fibre capacity on Aura, while Telstra would access fibre pairs on Google’s Tabua, Proa and Bulikula subsea systems. The companies described an exchange of infrastructure access, but did not disclose consideration, route-level volumes or a cash value that can be assigned to this route.
The return target also needs to stay in its lane. Telstra continues to cite a mid-teens internal rate of return and roughly nine-year cash payback for its strategic investment profile. Its expected A$1.8 billion of strategic investment through FY28 includes Viasat, not just Aura. Neither figure is a forecast for Perth–Sydney alone, and both are management targets rather than realized results.
The result is a fairly clear evidence ladder. Fibre built is not automatically a route ready for service. A ready route is not automatically a customer commitment. A commitment is not necessarily a service already accepted and used. And revenue, especially an early setup payment, is not the same as cash return over the life of the asset. Each rung is meaningful; skipping one makes the economics look more certain than public evidence allows.
Geography creates an option; contracts decide who pays for it
The route’s geography is strategically interesting. Telstra’s account traces it across a long inland corridor between Perth and Sydney and names several intermediate towns. The company says communities along the way will have the ability to connect into the network. That points to a potential wholesale opportunity beyond the two endpoints, but it does not establish that every named location has an active access point, a customer or a service order.
Route diversity can have value even when a customer does not fill every fibre pair. A network buyer may pay for a path that gives it an alternative to another corridor, supports recovery planning or reaches a new site. The economic question is who values that option enough to commit, and whether the contract’s duration, capacity reservation and service obligations compensate the builder for construction and maintenance. None of those terms is public for this route.
There is also a timing mismatch. The capital and civil works are committed before all future data-centre, cloud and enterprise demand is known. If demand arrives, a completed path can shorten the time to deliver a service and reduce the need to rebuild. If it arrives slowly, the operator carries an underused asset while waiting for customers to provision it. The network may still have public resilience value, but that benefit should not be counted as Telstra cash flow unless it is translated into paid services or another disclosed economic return.
The route’s opening is thus neither proof of success nor evidence of failure. It retires one class of risk—whether the physical route can be put into service—and makes other risks easier to observe: customer conversion, service acceptance, utilization, pricing and the pace at which cash arrives. A useful next disclosure would connect route readiness to contracted capacity, service activation and revenue, while preserving confidentiality around individual customer terms.
Sources
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance