
Summary
- Saudi Arabia’s regulator has designated STC and Dawiyat dominant service providers in the wholesale fixed broadband access market. Its market analysis treats copper, fibre and fixed wireless as part of that wholesale market and assesses geography regionally.
- The decisions create an obligation framework, not a service map. The evidence that matters next is whether an operator can request a defined product for a defined location, on terms and timing that make a retail offer possible.
The clock passed; the public record is not a scorecard
An operator can be named dominant and still leave a retailer with a practical question: can it order an access product where the next customer lives? That question is more specific than the word “wholesale”. It asks which network reaches the location, where traffic can be handed over, what the retailer must build itself, and how long it takes to turn a request into a billable service.
On 25 June 2026, the Communications, Space and Technology Commission (CST) issued two decisions. Decision 574/1448 designates Saudi Telecom Company (STC) a dominant service provider in the wholesale fixed broadband access market. Decision 573/1448 designates Dawiyat Integrated Telecommunications & Information Technology Company in the same market. Both decisions require compliance with obligations that apply to a dominant service provider, together with requirements and directives CST may issue later. Each says it is to be communicated for implementation within three months. That period elapsed on 25 September.
The date is a useful monitoring point, not a verdict. The public decisions establish who has been designated and when implementation was due to begin. They do not state how many access orders have been received, which have been accepted, how many locations are serviceable, or whether any party has failed to comply. Inferring a missed deadline or a functioning market from the calendar alone would confuse a legal instruction with operating evidence. CST’s STC decision and Dawiyat decision are the starting points for that distinction.
The market is regional and technology-neutral
CST’s 2025 Market Definition, Designation and Dominance Report (MDDD) gives the designations a more useful frame than a national fibre headline. It treats wholesale broadband access products over copper, fibre and fixed wireless access as part of the same product market. It describes the geographic market as regional, linking that scope to the regional rollout of fibre-based bitstream services. The market definition therefore does not say that every technology or every location is interchangeable. It says the regulator considers several access technologies within one product market while retaining geographic distinctions.
That matters because a retailer’s supply question is local even when its marketing plan is national. A network may have wide coverage in one region, limited reach in another and no suitable handover at a third. A nominally available wholesale product may also require the retailer to own more of the route, equipment or customer-facing control than it expected. Market-wide designation and address-level availability answer different questions.
The MDDD report also explains why retail competition may not discipline the wholesale price enough. CST models a 5–10% increase in a wholesale bitstream price as producing a 3–6% retail-price increase if fully passed through. It concludes that resulting customer switching would not constrain the wholesale supplier sufficiently. One reason is that a vertically integrated provider’s own retail business might not pass the increase on in the same way. That is CST’s analysis of a possible price change, not evidence that such an increase occurred or that either designated provider has abused its position. The point is structural: the retail bill may not reveal the cost or leverage embedded one layer below it. The MDDD report describes that boundary.
A handover determines what the retailer controls
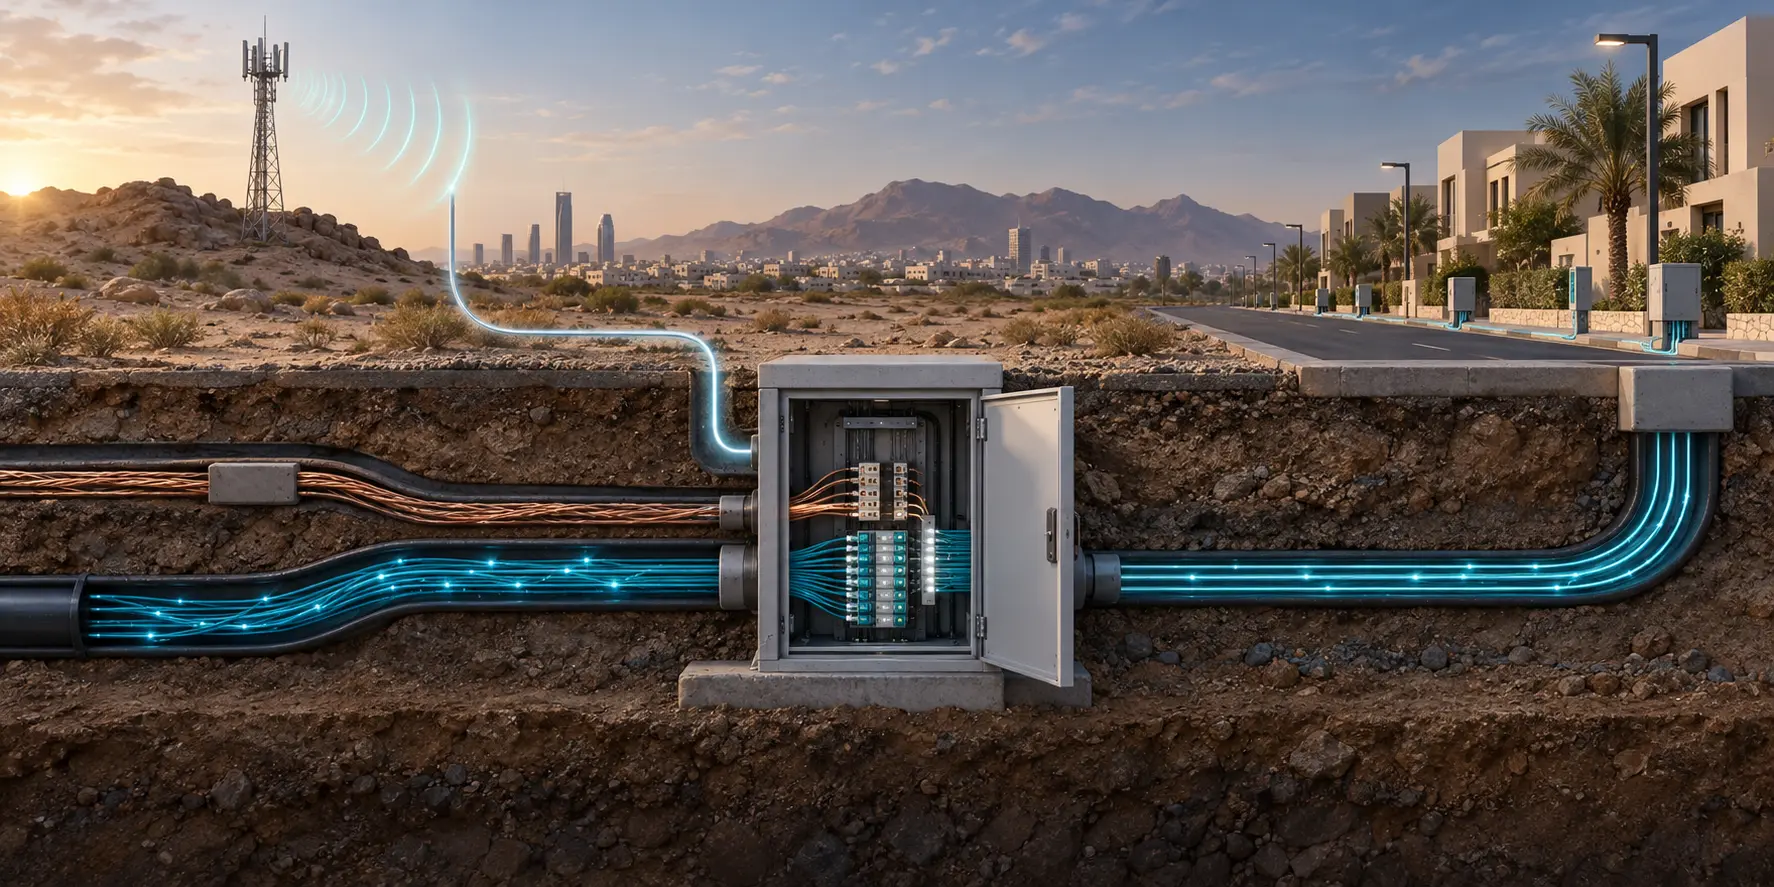
Wholesale broadband is not one uniform pipe. A bitstream product can be handed over at different points in a network. The access seeker then decides how much of the retail service depends on its own equipment and network, and how much depends on the access provider. CST’s MDDD names DSLAM, ATM and IP handovers as examples of points that change how much control the retailer has over the product it sells.
The trade-off is familiar to network operators. A more managed handover can reduce the access seeker’s need to build and operate equipment deep in the network. It can also leave the access provider with greater influence over the technical parameters available to the retailer. A handover farther toward the edge can offer the seeker more control, but it can demand more investment, engineering and interconnection. Which product is commercially useful depends on the balance: retail differentiation, local coverage, quality, cost and the provider’s own build plan.
That is why “two dominant providers” does not by itself reveal competitive choice. The number tells readers that CST placed two firms under a set of market-specific obligations. It does not show whether their footprints overlap in a given region, whether their POIs give a retailer the same reach, whether their products use comparable handover points, or whether their prices and service levels support a substitute offer. These questions need regional and product-level evidence.
The rule reaches the network through a request
CST’s Telecommunications and Information Technology Bylaw sets out the general bridge between a designation and access. Articles 27–35 require dominant providers to publish reference offers as CST directs, apply nondiscriminatory prices and comparable conditions, provide access on terms and service quality equivalent to their own or affiliates’ services, share necessary technical information, and protect information supplied by a requesting provider from use by business units that could gain a competitive advantage. A written access request is to be handled through good-faith negotiations, without deliberate delay or refusal to provide necessary information. Article 31 ties provision to the approved reference offer; Article 32 recognizes an exception where technical or commercial feasibility is not established unless CST decides otherwise. The bylaw also provides for neutral request handling, reporting to CST and referral of unresolved disputes. The current CST bylaw describes these duties and limits.
STC’s public reference offer shows how those rules can become a specific workflow. Its October 2025 Annex G, Schedule 19, says the other licensed operator initiates a wholesale bitstream request and that STC is not obliged to provide service at sites not designated as points of interconnection (POIs). The FTTH schedule adds more detail: the service is to match the standard and quality STC provides on its own network; the parties set technical, service-level and commercial terms in a separate agreement; and the requesting operator submits a form.
STC acknowledges within five business days and, within ten, identifies whether the work is network conditioning or software programming, or requires other work. The schedule then gives a 30- or 60-business-day negotiation period depending on that work, with additional charges possible in the latter case. Implementation follows an agreed timetable.
Those clauses show that “access” is a sequence: a place, a product, a technical handover, a request, an assessment, a price and a schedule. They do not show how often the process is used or how it performs. The offer is also STC’s 2025 document. It cannot be treated as Dawiyat’s terms or proof of current availability across all Saudi regions. STC’s service schedules make the contract boundary visible without answering the serviceability question.
What would make the designation measurable
The next public evidence would be a crosswalk from the obligation to the order. For each relevant region, it would show which wholesale technologies are offered, their handover points, the locations and POIs covered, the applicable prices and service levels, and the conditions an access seeker must meet. A request record would show the date received, acknowledgment, feasibility assessment, negotiation period, implementation date, outcome and reason for any refusal or additional charge. Comparable data for both designated providers would let a retailer, investor or regulator distinguish a broad legal right from a usable product.
Confidential network details need not be published to answer every question. The bylaw itself recognizes that some contractual information can remain confidential. Aggregated measures—requests received and completed, median time to assess, the share requiring extra works, service quality against the provider’s own retail service, and active wholesale locations—could still reveal whether the process is expanding choice or merely describing a route that few firms can use.
Without that evidence, three readings remain possible. The reference-offer process may be converting the designations into predictable service. It may be available in some locations and technically constrained in others. Or the public record may simply lag the operational detail. The documents reviewed do not decide among those outcomes. A finding of compliance or breach would require request and service evidence that is not present in the decisions.
The useful conclusion is narrower. CST has named two dominant providers in a regionally defined market and established duties around terms, information, negotiation and access. The contestability test now sits at the handover: whether the regional service can be priced, ordered, activated and compared. A designation is the rule’s entry point. The request and the address show whether it reaches the market.
Sources
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance