
Summary
Private Connectivity Fabric gives Lumen Technologies something conventional network expansion often lacks: customer cash before the corresponding infrastructure has completed its path to earned revenue. For the six months to June 30, 2026, Lumen reported $2.294 billion of operating cash flow, $1.845 billion of capital expenditure and a $1.772 billion positive change in deferred revenue.
The company says PCF advance payments raise operating cash flow and deferred revenue and are used to fund network expansion and simplification.
Crucially, the filing says the rise in deferred revenue from advance cash payments was only partially pursuant to recent PCF sales. The entire $1.772 billion movement cannot be assigned to Private Connectivity Fabric.
Prepayment improves sequencing, not project physics. Lumen still identifies construction delay, cost overrun, labour, permitting, supply-chain and demand risks around PCF, while Q2 2026 revenue fell to $2.805 billion from $3.092 billion and adjusted EBITDA excluding special items fell to $802 million from $877 million. Strategic business revenue grew 14%, but legacy revenue fell 15%; in absolute dollars, the strategic increase did not yet fully offset the legacy decline.
The AT&T divestiture has reduced debt, interest and consumer-fibre capital requirements but also recurring operating cash flow. Alkira can improve orchestration of the remaining enterprise network, but software does not remove the need to construct, light, test, repair and ultimately deliver physical capacity.
The dollar before the splice
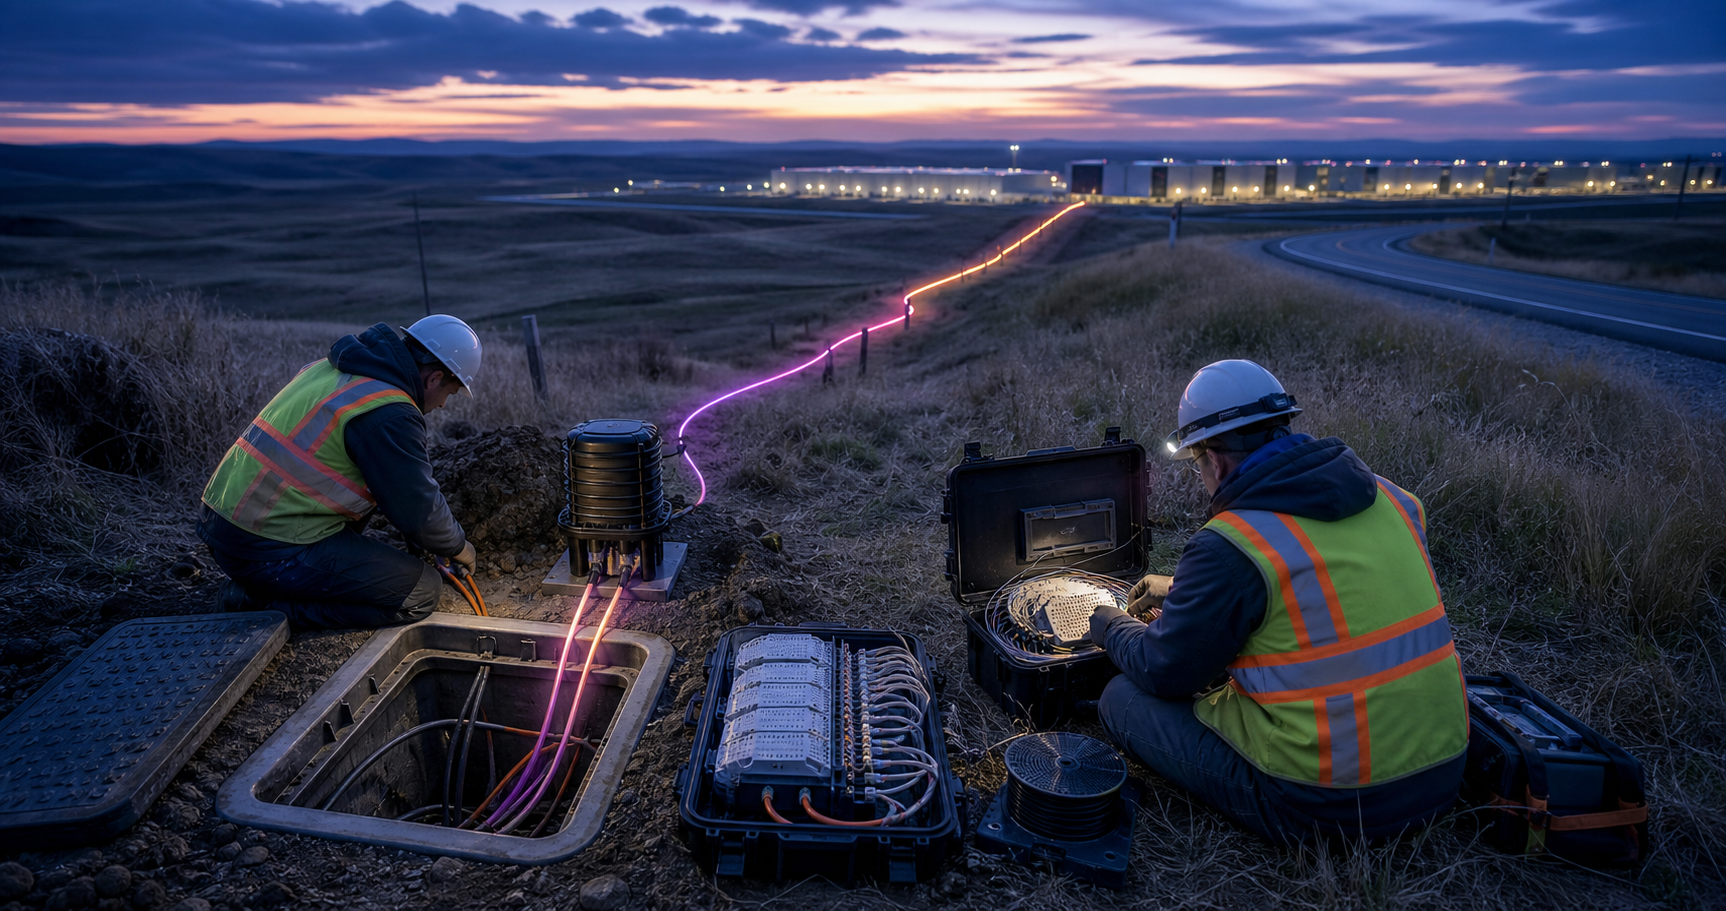
A useful way to understand Lumen Technologies in 2026 is to stop at the splice case.
A fibre cable can be in the ground and still not be a service. Individual fibres have to be joined. Long optical paths require equipment, power, configuration and testing. The route has to perform as required, and contractual delivery conditions have to be met. Lumen’s own 2025 Form 10-K says PCF agreements contain delivery obligations and performance conditions that affect the timing and amount of revenue recognition.
It also warns that weather, labour, permitting and supply-chain problems can cause construction delays or cost overruns.
Yet the cash does not necessarily wait for this physical sequence to finish. In its Q2 2026 Form 10-Q, Lumen states that advance payments under PCF agreements increased operating cash flow and deferred revenue, and that those payments are applied to network expansion and simplification projects, which in turn increase capital expenditure. That sentence contains the economic mechanism at the centre of the company’s current transformation.
Follow one hypothetical dollar, without pretending that Lumen discloses a standard PCF contract.
At contract signing, the dollar may not have moved at all. What exists is a commercial commitment governed by terms that Lumen does not disclose on a deal-by-deal basis. Announced contract value is consequently evidence of contracted demand, not evidence of cash in the bank. In October 2025 Lumen said total PCF deal value had exceeded $10 billion after another $1 billion of deals; its full-year 2025 results subsequently reported another $2.5 billion of contracts and described PCF sales as nearly $13 billion.
Those figures do not by themselves disclose how much cash has been collected, which routes are complete, when individual services become operational, what margins will be earned or when revenue will be recognised.
At advance payment, the sequencing changes. The customer has parted with cash before Lumen has necessarily completed all of the corresponding delivery work. Lumen has gained liquidity; the customer has demonstrated a form of commitment stronger than a forecast or expression of demand. Economically, this can reduce the amount of capital that Lumen itself must supply during the build period.
But the public disclosures do not establish PCF-wide cancellation rights, refund provisions, acceptance remedies, pricing concessions or the cost of capital implicitly embedded in those commercial bargains. Calling the advances “free financing” would therefore go too far. Calling them customer-funded working capital for network expansion is closer to what the filing actually supports.
At deferred revenue, accounting makes the distinction between cash and earnings visible. For the first half of 2026, the consolidated cash-flow statement recorded a $1.772 billion positive change in deferred revenue. That line item was equivalent in magnitude to roughly 77% of the period’s $2.294 billion of operating cash flow. The ratio illustrates the importance of timing; it is not an attribution.
Management explicitly says the increase in deferred revenue associated with advance cash payments was only partly related to recent PCF sales.
The distinction becomes even more important because “deferred revenue” is not a synonym for “unearned PCF revenue.” At June 30 the balance sheet showed $999 million of current deferred revenue and $8.178 billion of non-current deferred revenue, while the ASC 606 customer-contract-liability disclosure was only $623 million. Lumen explains that its revenue base also includes arrangements outside ASC 606, including fibre-capacity and conduit leases.
Its separate disclosure of unsatisfied ASC 606 performance obligations was $5.9 billion, but that measure excludes leasing arrangements and certain contracts for which revenue is recognised using the right-to-invoice practical expedient. None of these consolidated accounting measures can safely be relabelled as a PCF backlog.
At construction, the advance ceases to look like revenue and starts to look like a funding source for expenditure. Lumen spent $1.845 billion on capital expenditure during the first half. The company says rising labour, material and energy costs have increased both operating expenditure and capital expenditure, particularly for the continued PCF buildout and other network transformations. It also says shortages of critical components and materials have already slowed certain network expansion efforts.
This is the point at which the idea of a complete “construction-risk transfer” breaks down. A customer paying early can transfer financing timing away from Lumen, but it does not follow that the customer has assumed the engineering burden or cost-overrun risk. Lumen’s own risk disclosures continue to place construction delays and higher build costs squarely among the threats to PCF economics.
Unless an individual contract allocates those risks differently—and the public record does not disclose such terms—the conservative reading is that customer money helps finance the work while Lumen remains exposed to whether the work can be delivered economically.
The working-capital bridge has other moving parts. Accounts payable included $282 million associated with capital expenditure at June 30, down from $463 million at December 31, 2025. That movement matters because cash expenditure and physical construction progress do not occur on the same timetable: vendor invoices, payment terms and project milestones can move reported cash flow between periods without telling an analyst exactly how many routes have become usable.
At equipment, testing and customer acceptance, public disclosure becomes thinner. Lumen identifies performance conditions and delivery obligations, but it does not publish a universal PCF acceptance schedule, route-by-route commissioning calendar or standard customer remedy package. There is therefore no legitimate basis for assuming that a signed contract becomes revenue on a fixed number of days after construction, or that every PCF transaction has identical acceptance mechanics.
The economically relevant point is narrower: advance cash can precede satisfaction of the obligations that permit revenue recognition.
At revenue recognition, product type matters. Under ASC 606, Lumen says it recognises revenue when or as a performance obligation is satisfied; service revenue is recognised as the applicable service is provided. Advance design, planning, engineering, activation or installation fees that are not separate performance obligations are deferred and generally recognised over the relevant contract term or estimated useful life.
Separately, cash received on transfers of dark fibre can be treated as lease revenue outside ASC 606 and recognised ratably over the lease term. Private Connectivity Fabric is therefore not analytically reducible to a single cash-to-revenue formula.
Then comes maintenance and renewal. A completed optical system still has to remain available. Fibre cuts, equipment failures, power issues, field repair, capacity management and physical route diversity do not become software problems merely because ordering and orchestration are digital. The capital already spent also has to produce enough revenue over time to cover operating costs, sustaining investment and the cost of financing.
Lumen itself warns that changes in data-centre connectivity demand could reduce or even eliminate future PCF profitability.
Only at the final stage does the original dollar become part of the more demanding proposition: durable free cash flow. The customer may have paid much earlier. Lumen may have reported operating cash flow much earlier. But economically successful financing requires the installed network to earn enough over its useful commercial life to compensate for all the cash consumed after prepayment.
That distinction is particularly important in Lumen’s first-half numbers. Reported operating cash flow was $2.294 billion and capital expenditure $1.845 billion, producing $449 million of free cash flow under Lumen’s definition. Free cash flow excluding special items was $1.083 billion.
But the operating-cash-flow figure also included $729 million of AT&T transaction proceeds allocated to contractual credits and commercial agreements and therefore classified as operating rather than investing cash flow; it also reflected a $101 million voluntary pension contribution. The first half consequently provides substantial evidence of liquidity, but it is not a clean, single-period measure of the recurring cash yield of the post-divestiture enterprise network.
Private Connectivity Fabric prepayment is thus best understood as a mixture. It is customer commitment because cash is stronger evidence of demand than an unsigned plan. It is working capital because it brings funding forward relative to delivery. It is a partial financing-risk transfer because Lumen can use customer advances instead of supplying every construction dollar from existing cash or new borrowing.
But it is not, on the evidence disclosed, a wholesale transfer of construction, performance, maintenance or demand risk.
Demand that has not yet become service
This financing advantage matters only if the commercial conversion is fast enough.
The Q2 2026 results show a company whose portfolio is improving underneath a still-declining top line. Revenue was $2.805 billion, against $3.092 billion a year earlier. Adjusted EBITDA excluding special items was $802 million, against $877 million. Business revenue was $2.444 billion, down from $2.490 billion.
Inside Business, however, the direction of travel is clearer. Lumen reclassified its portfolio into “Strategic” and “Legacy” categories in 2026. Q2 Strategic revenue was $1.289 billion, up $159 million or 14% year on year; Legacy was $1.155 billion, down $205 million or 15%. For the first six months, Strategic increased by $266 million while Legacy decreased by $392 million. Dark fibre and conduit accounted for $109 million of the Q2 Strategic increase and $180 million of the six-month increase.
Those absolute dollars matter more than the symmetrical-looking percentages. In Q2, the $159 million Strategic gain still fell $46 million short of the $205 million Legacy decline. Across the first half, the $266 million Strategic increase fell $126 million short of the $392 million Legacy decline. This is not evidence that Private Connectivity Fabric is failing: Strategic includes several products, and the company does not separately disclose PCF recognised revenue.
It is evidence that the broader strategic portfolio had not yet crossed the most important operating threshold—new-dollar growth fully replacing old-dollar decay.
The total-company comparison is further complicated by the AT&T transaction, because Q2 Mass Markets revenue fell to $361 million from $602 million after the consumer-fibre sale closed on February 2. Portfolio removal is therefore mixed into the headline 9% revenue decline. An analyst testing the PCF thesis has to separate three processes that happen simultaneously: legacy enterprise erosion, strategic enterprise growth and the deliberate disappearance of divested consumer revenue.
The financing burden, meanwhile, has moved in the opposite direction. Q2 interest expense fell to $201 million from $338 million; for the first half it fell to $426 million from $685 million. Lumen attributes the decline principally to lower average debt and lower average interest rates. Cash interest paid in the first half was $371 million, versus $676 million a year earlier. The reduction gives strategic revenue more room to become free cash flow before financing consumes it.
But borrowing has not become costless. At June 30, Lumen reported $1.876 billion of cash, approximately $6.8 billion of secured debt, $6.3 billion of unsecured debt and $660 million of revolver availability. Earlier in 2026, Level 3 Financing issued another $650 million of 8.5% secured notes due 2036 to repurchase other debt.
Customer advances can therefore have real economic value by reducing reliance on marginal external financing, even though the embedded commercial price of obtaining those advances is undisclosed.
Lumen’s own full-year outlook sets the near-term cash benchmark. The company forecasts 2026 adjusted EBITDA excluding special items of $3.1 billion to $3.3 billion, free cash flow excluding special items of $1.9 billion to $2.1 billion and capital expenditure excluding special items of $3.2 billion to $3.4 billion. Those are Lumen forecasts, not independent estimates, and its outlook incorporates a $400 million tax refund from recent tax legislation.
The deeper test is what happens after unusually favourable timing items fade. A business can produce strong operating cash flow while deferred revenue rises because customers are paying before the company performs. That is good liquidity. It becomes good economics only when the subsequent expenditures produce services whose revenue and eventual cash margins justify the construction.
The physical scale of Lumen’s ambition makes that conversion problem large. On its Private Connectivity Fabric product page, Lumen set an expectation of 16.6 million intercity fibre miles at the end of 2025 and a target of 47 million by the end of 2028. Its February 2026 AT&T-close release rounded the year-end deployed figure to 17 million intercity fibre miles and repeated the 47 million target. The latter is a company target, not completed capacity.
That vocabulary needs discipline. Planned fibre is a capital programme. Installed or deployed fibre is physical plant. Lit fibre has optical equipment capable of carrying traffic. Accepted capacity, where contractual acceptance applies, has cleared the relevant customer conditions; Lumen does not disclose a PCF-wide acceptance timetable. Revenue-producing fibre has reached the accounting and commercial state at which the applicable service or lease is producing recognised revenue.
The 47 million-mile target cannot be treated as 47 million miles of accepted, billable capacity.
This is also why product engineering and project economics cannot be separated. Lumen says Private Connectivity Fabric is designed around newer fibre and modular network architecture, and markets performance advantages including 60% more capacity than legacy fibre and lower optical loss. Those are Lumen product claims, not independently established performance results.
Even if realised, a superior fibre design does not earn a return while the route is unfinished, while equipment is unavailable or while the customer’s contractual delivery conditions remain unsatisfied.
The strongest evidence for the transformation will therefore not be another large contract-value announcement. Contract value is at the beginning of the funnel.
The stronger evidence would be a sequence in which announced demand produces advance cash, advance cash funds construction, deployed infrastructure reaches commercial service, Strategic revenue grows in absolute dollars faster than Legacy shrinks, capital intensity eventually normalises and operating cash flow remains strong when the deferred-revenue build is no longer doing as much work.
A narrower company with a tighter clock
The AT&T sale makes that conversion test more consequential because Lumen Technologies has deliberately narrowed the company around it.
The AT&T transaction close transferred the consumer fibre-to-the-home business in eleven states for $5.75 billion in cash. The assets and customer relationships served more than one million fibre customers and reached more than four million enabled fibre locations.
Lumen said it used transaction proceeds and cash to reduce debt by more than $4.8 billion; its full-year release said net leverage fell below four times, annual interest expense was nearly 45% lower than 2025 levels and capital expenditure was reduced by more than $1 billion.
The SEC filing supplies the counterweight to that balance-sheet improvement. Lumen expects the divestiture to reduce recurring revenue and recurring operating cash flow, even as it reduces Mass Markets fibre-related capital expenditure by approximately $1 billion annually. This is not simply deleveraging; it is a deliberate exchange of one future cash-flow stream for lower leverage, lower capital requirements and greater strategic concentration on enterprise networking.
That trade is economically difficult to reverse. The consumer network and relationships have been transferred to AT&T. If enterprise-network monetisation takes longer than expected, Lumen cannot respond with an ordinary capital-allocation adjustment and recreate the divested subscriber base. The company has obtained lower fixed financing and investment burdens, but it has also given up the recurring operating cash associated with the sold footprint.
The remaining company therefore has fewer strategic contradictions but a clearer burden of proof.
Private Connectivity Fabric advances fit that narrower company unusually well. They finance an enterprise-oriented physical network using cash associated with enterprise connectivity demand. The AT&T proceeds reduce the inherited balance-sheet burden; customer advances help bridge new construction; later recurring revenue is supposed to make the enterprise-focused structure self-supporting. The sequencing is coherent.
The remaining question is whether the middle of the bridge—the actual network build—can carry the weight.
Here Alkira enters as a second, different capital allocation. The 10-Q records a $487 million cash purchase price, subject to adjustments, for Alkira; the transaction closed July 1, one day after the reporting period, so no Alkira acquisition amounts were included in Lumen’s June 30 consolidated financial statements. The preliminary purchase-price allocation was still being evaluated.
Lumen describes Alkira as a cloud-native, carrier-agnostic networking platform. In its Alkira acquisition close, the company says it expects Alkira technology to become part of Lumen Connect, allowing customers to build and manage secure connections across clouds, sites, partners and AI workloads through a more unified digital interface. That makes the acquisition a control-plane bet: better orchestration, visibility and automation could make physical connectivity easier to provision and consume.
But the control plane and the transport plane remain different economic objects. Alkira can potentially reduce operational friction around choosing, configuring and managing connectivity. It cannot make an unfinished physical route complete.
It cannot substitute for geographic route diversity where the network lacks it, restore optical performance lost to a physical fault, perform a field splice, replace failed line equipment, remove a permitting delay or satisfy a physical delivery condition merely by changing software state. Lumen’s own PCF risk disclosures make construction and delivery constraints explicit.
The acquisition therefore raises a more interesting strategic possibility than simple software diversification. If Lumen can pair a programmable control layer with abundant physical capacity, it may reduce the interval between a customer deciding it needs connectivity and activating capacity that already exists. That could improve utilisation of completed fibre and make network services easier to expand after initial deployment.
But the disclosures do not yet provide Alkira-specific revenue, margin, provisioning-time or cash-return data with which to measure that thesis.
Nor do they disclose enough to resolve customer bargaining power.
The 2025 10-K says no single customer represented more than 10% of consolidated operating revenue. That is useful but incomplete. Recognised revenue concentration is not the same thing as concentration of PCF contract value, advance payments or future route economics. Lumen does not disclose the share of announced PCF sales represented by its largest customer, the share of advances attributable to the largest counterparties or customer-by-customer renewal exposure.
Large customers can affect the economics in two opposing directions without requiring any assumption about Lumen’s undisclosed terms. A substantial prepayment strengthens the supplier’s funding position and demonstrates buyer commitment. At the same time, a buyer responsible for a large share of the economic justification for new capacity can matter disproportionately in future commercial negotiations.
How much of that potential bargaining power exists here depends on facts that are not public: whether capacity is readily reusable by other customers, the existence and nature of cancellation rights, service credits, acceptance conditions, renewal pricing, minimum commitments and other contractual protections.
Those unknowns are material. They prevent the nearly $13 billion of announced PCF sales from being converted analytically into a net-present-value estimate, an implied margin or a guaranteed future revenue schedule. They also prevent the advance payments from being classified cleanly as either customer financing or construction-risk transfer. They are, more plausibly, both customer commitment and financing support, with the actual division of residual risk still sitting inside contracts investors cannot see.
The transformation consequently runs on three clocks. Cash can arrive first. Construction follows. Earnings arrive last. At the same time, Legacy revenue is declining now and debt still carries interest now. The value of prepayment lies in widening the interval Lumen has to make the new network productive. It does not stop that interval from expiring.
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance