
Summary
- IBEX Limited reported more than ten AI Agent implementations across five verticals and two strategic AI Agent wins among nine new fourth-quarter logos. It did not disclose AI Agent revenue, contact volume, contract pricing, autonomous-resolution share, human work, customer acceptance, renewal, or cohort margin.
- Group results cannot fill that gap. Fourth-quarter revenue rose 11.6% to $164.3 million while adjusted EBITDA fell 1.3% to $20.2 million and adjusted EBITDA margin declined 160 basis points to 12.3%. The company linked the period's net-margin pressure primarily to new-client training and a temporary nearshore-to-offshore work transfer, not to AI.
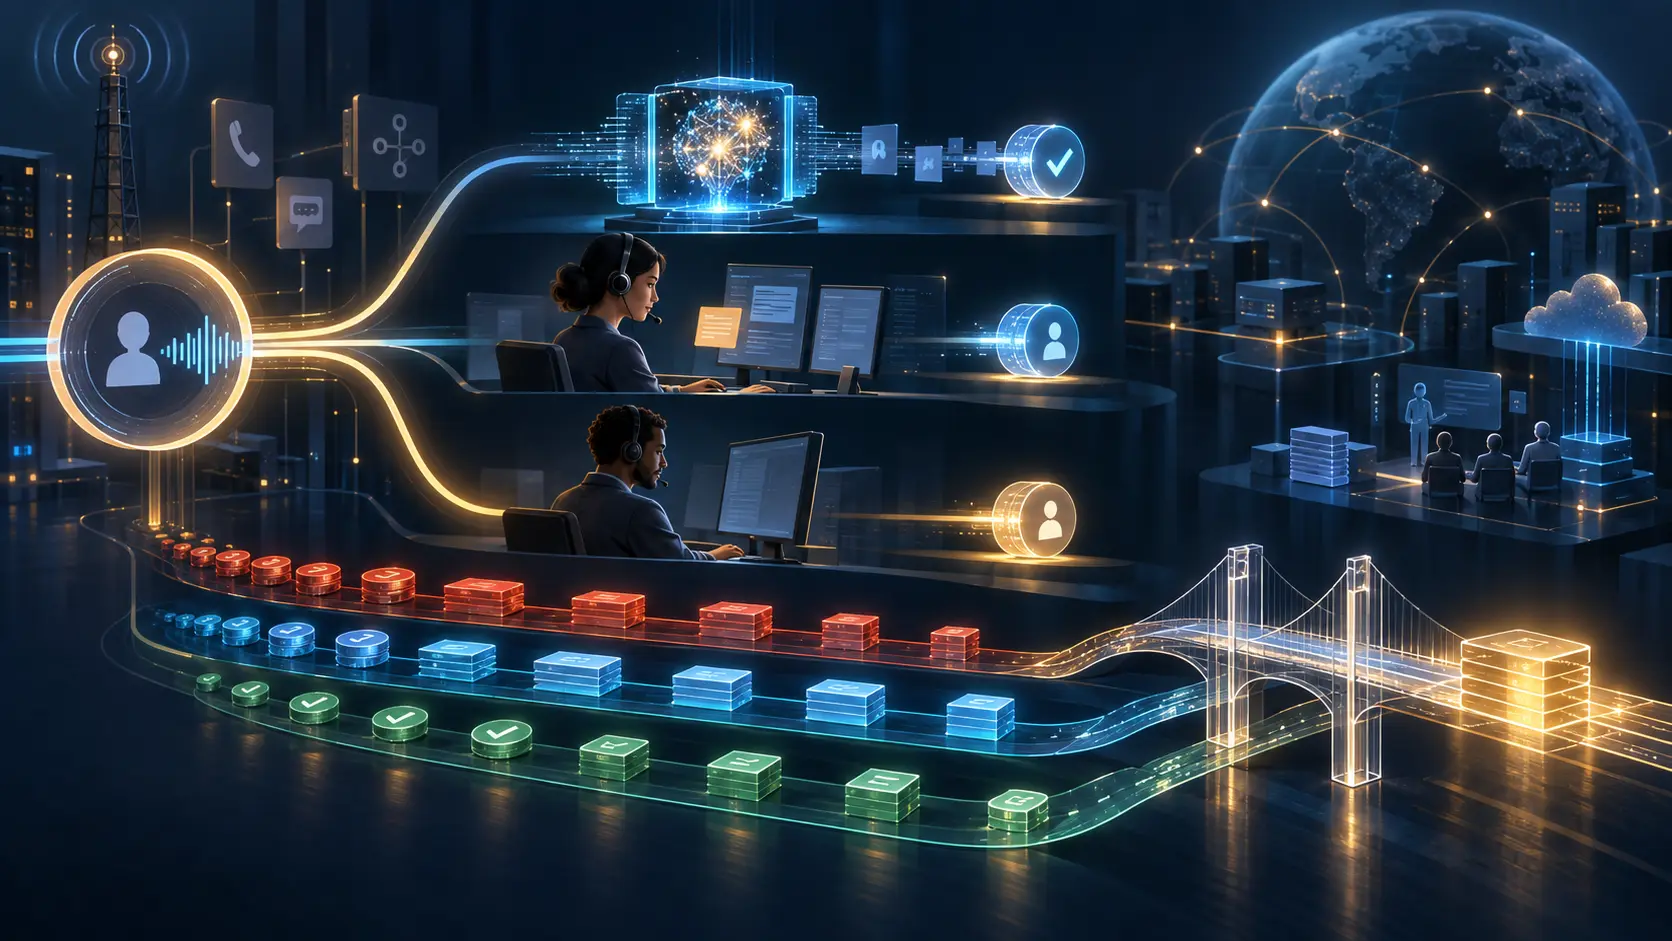
- A useful bridge would follow each deployment from signed scope and production date through eligible contacts, autonomous resolutions, assisted and human-only work, repeats and escalations, price basis, accepted outcomes, revenue, labour and platform cost, contribution margin, renewal, and expansion. Geography and new-client ramp must remain separate columns.
The implementation count stops before the economic event
“More than ten” answers a narrow question: has ibex moved AI agents beyond a laboratory demonstration? According to the company, yes. The number spans five verticals, and the fourth quarter included two new logos described as strategic AI Agent wins. The May partnership announcement with Sierra also identifies a phased Philippine Airlines deployment and says several implementations were at different stages.
But an implementation is not a stable unit of production. It may be a pilot handling one intent in one channel, a voice agent covering a larger queue, an assistant that leaves the human agent in control, or a combination of automation, routing and analytics. It can be signed, integrated, launched, expanded, paused or replaced. Without a definition of when ibex begins and stops counting, ten small deployments and ten scaled programmes occupy the same sentence.
The revenue line is broader still. Fiscal 2026 revenue reached $644.1 million, up 15.4%. The company attributed growth to several verticals, Wave iX solutions and its digital acquisition business. The 10-K says Wave iX is deployed across a majority of the client portfolio and supports changes across recruiting, hiring, training, management and customer experience. That installed footprint is not the same population as the more-than-ten customer-facing AI Agent implementations. Combining them would turn two different numerators into an invented denominator.
The disciplined conclusion is therefore modest. ibex has evidence of deployment activity and strong company-wide growth. Public documents do not provide the reconciliation needed to state how much of that growth, if any, came from AI-agent work.
One contact can create three different receipts
The operating distinction begins before finance. For every eligible customer contact, an autonomous system may complete the requested task; it may gather information and then transfer to a person; it may assist an employee while the employee remains responsible; or it may fail qualification and enter a conventional queue. Those paths consume different combinations of model inference, telephony, integration, supervision, training and paid human time.
They can also produce different revenue. The 10-K says client prices are often expressed per minute or hour, with some bonuses or penalties tied to client objectives. A contract built around human handling time may lose billable minutes when an AI agent resolves a contact quickly. A platform fee, per-resolution price or outcome payment could capture value differently. A hybrid arrangement might pay for both the automated front end and the remaining human work. ibex does not disclose which structure applies to its AI Agent wins.
This creates a question that marketing language cannot answer: who keeps the value of a shorter or avoided interaction? The client may receive a lower cost to serve. ibex may gain a software fee or higher contribution per outcome. A technology partner may collect usage economics. The end customer may receive faster resolution—or may repeat the contact if the first answer was incomplete. The same “automated” event can redistribute revenue, cost and risk among four parties.
A count of implementations ignores all of those movements. Even a count of contacts “handled by AI” is ambiguous unless it distinguishes completed tasks from authentication attempts, partial conversations, transfers, abandonments and repeat contacts. Containment is valuable only when the customer's problem is actually resolved and stays resolved.
The fourth quarter is a confounded observation, not an AI verdict
ibex's fourth quarter demonstrates why a bridge matters. Revenue rose from $147.1 million to $164.3 million. Net income fell from $9.6 million to $8.7 million, and net margin declined from 6.5% to 5.3%. Adjusted EBITDA was $20.2 million versus $20.5 million, with adjusted EBITDA margin down from 13.9% to 12.3%.
Those figures might tempt two opposite stories. One could claim that AI was already accelerating revenue. Another could claim that AI was compressing profitability. Neither follows from the evidence. The company said the net-margin decline was driven primarily by training costs related to new client wins and the temporary impact of work moving from nearshore to offshore centres. It did not allocate the training to AI contracts, identify the transferred programmes, or attribute the margin change to automation.
The 10-K explains the ordinary BPO mechanics behind that volatility. Hiring and training expenses arrive before revenue when demand expands. A shift from onshore to offshore delivery generally lowers the price paid by the client and reduces ibex's absolute revenue, while margins tend to increase. Vertical mix, digital acquisition, wages, facilities, software licences and foreign exchange also move the group numbers. In fiscal 2026, cost of services grew 18.3%, faster than the 15.4% increase in revenue, while full-year adjusted EBITDA margin was nearly flat at 12.8% compared with 12.9%.
None of this weakens the AI thesis by itself. It establishes the controls a serious measurement system must contain. An AI cohort should not receive credit for revenue produced by a conventional new-logo ramp, nor blame for cost incurred in a geographic transition. If an AI deployment required extra integration or training, that cost should appear in its own cohort. If automation let a programme move, shrink or expand its human delivery footprint, the sequence and counterfactual should be documented rather than assumed.
Build the bridge at cohort level
The minimum receipt begins with identity. Name the client cohort without exposing confidential customer information: vertical, contract type, signed date, production date, channel, languages, authorised intents and baseline operating geography. State what “implemented” means—technical go-live, first live contact, acceptance test, contracted volume, or full roll-out—and preserve later changes to that status.
The second section follows demand. Record eligible contacts, contacts offered to the AI agent, completed authentication, autonomous task resolutions, assisted-human contacts, direct human contacts, transfers, abandonments and repeats within an agreed window. These counts must reconcile so that an offered interaction cannot disappear when it crosses from software to a person. Separate a conversational turn from a contact, and a contact from a resolved customer need.
The third section records quality and control. Which intents were allowed? What actions could the agent execute in systems of record? Which cases required approval? How often did a person intervene? What was the error, complaint or correction rate? Which outcome did the client accept for billing or service-level purposes? A “successful implementation” is management's description until the acceptance rule and observed result are visible.
The fourth section connects operations to money. Show the price basis, recognised revenue, credits and penalties, model and platform charges, integration and support cost, telephony, security review, human handling minutes, supervision, hiring, training and transition cost. The result should be a contribution view, not an allocation of every corporate overhead dollar. Its purpose is to reveal whether the programme earns more because the service is better, because labour moved, because the contract changed, or because a temporary ramp cost expired.
Finally, follow durability. Renewal, expansion to new intents, contraction, rollback and termination belong to the same history. A launch that meets acceptance in month one but creates repeat contacts in month three is not the same economic object. Nor is a pilot that expands from one queue to a client-wide service. Cohorts should mature without rewriting their original baseline.
A public case study shows why denominators matter
ibex's anonymised national-retailer case study offers a useful bounded example. It reports more than 37,000 inbound calls handled by AI, 11.7% containment without an agent handoff, 70% customer-authentication success and a claimed 20% reduction in repetitive tasks. These figures are more informative than an implementation count because they begin to describe workload and flow.
They also raise the next questions. Is 11.7% calculated over all inbound calls, the calls offered to the virtual agent, or successfully authenticated calls? Does “handled” include transferred and abandoned calls? Was containment measured immediately or after a repeat-contact window? What volume and labour baseline produced the 20% figure? Did pricing reward containment, resolution, minutes, availability or another result? The public page need not disclose a customer's confidential economics, but portfolio reporting should define measures consistently enough to compare cohorts.
The case study cannot be extrapolated to the more-than-ten deployments. It concerns one unnamed retailer, one design and one measurement period. Its value for diligence is methodological: a numerator becomes decision-useful only when the eligible population, route, observation window and accepted outcome travel with it.
The human estate has not disappeared
At 30 June 2026, ibex reported approximately 35,000 employees, up from about 33,000 a year earlier. It operated 30 delivery centres and 21,705 production workstations, with 20,325 in use and reported utilisation of 94%. Nearly 176 million customer interactions were managed during the year. None of those figures is partitioned into autonomous, assisted and human-only work.
That absence matters because AI can alter human work without simply removing it. A virtual agent may absorb routine contacts while leaving employees with longer, less predictable and more sensitive cases. Assistance may shorten handling time but add review duties. New automation may require trainers, integration engineers, quality analysts and exception teams before it stabilises. If a client expands total demand, human headcount may rise even as automation share rises. If work shifts offshore at the same time, labour cost can change for reasons unrelated to the model.
A credible receipt therefore measures work, not a political promise about jobs. It should show paid human hours per resolved need, training hours, schedule volatility, escalation complexity and quality-review load. It should also show whether productivity gains are retained by ibex, passed to the client through lower prices, reinvested in service, or absorbed by technology and transition costs.
Evidence boundaries
The fiscal 2026 release confirms the implementation count and consolidated results. It does not disclose an AI segment. The 10-K describes portfolio-wide Wave iX deployment and operating economics but does not connect a particular AI agent to recognised revenue or cost. The Sierra announcement contains supplier and customer statements about a phased deployment; it is not a contract, audit or cohort profit statement.
The analysis does not infer that AI caused the fourth-quarter margin decline, the year's revenue growth, higher headcount, geographic migration or fiscal 2027 guidance. It does not treat the word “successful” as proof of profitability, renewal or independent outcome acceptance. It does not apply one retailer's published metrics to other clients. The claim is narrower: implementation has become visible, while the economic bridge remains missing.
Sources
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance