Summary
- CRTC rejected a request to extend aggregated wholesale fibre access to every SWIFT-funded network. Existing contractual access obligations remain a different matter.
- SWIFT's temporary 51% interest is in funded network elements, not the companies operating them. It does not make every provider subject to the same wholesale rules.
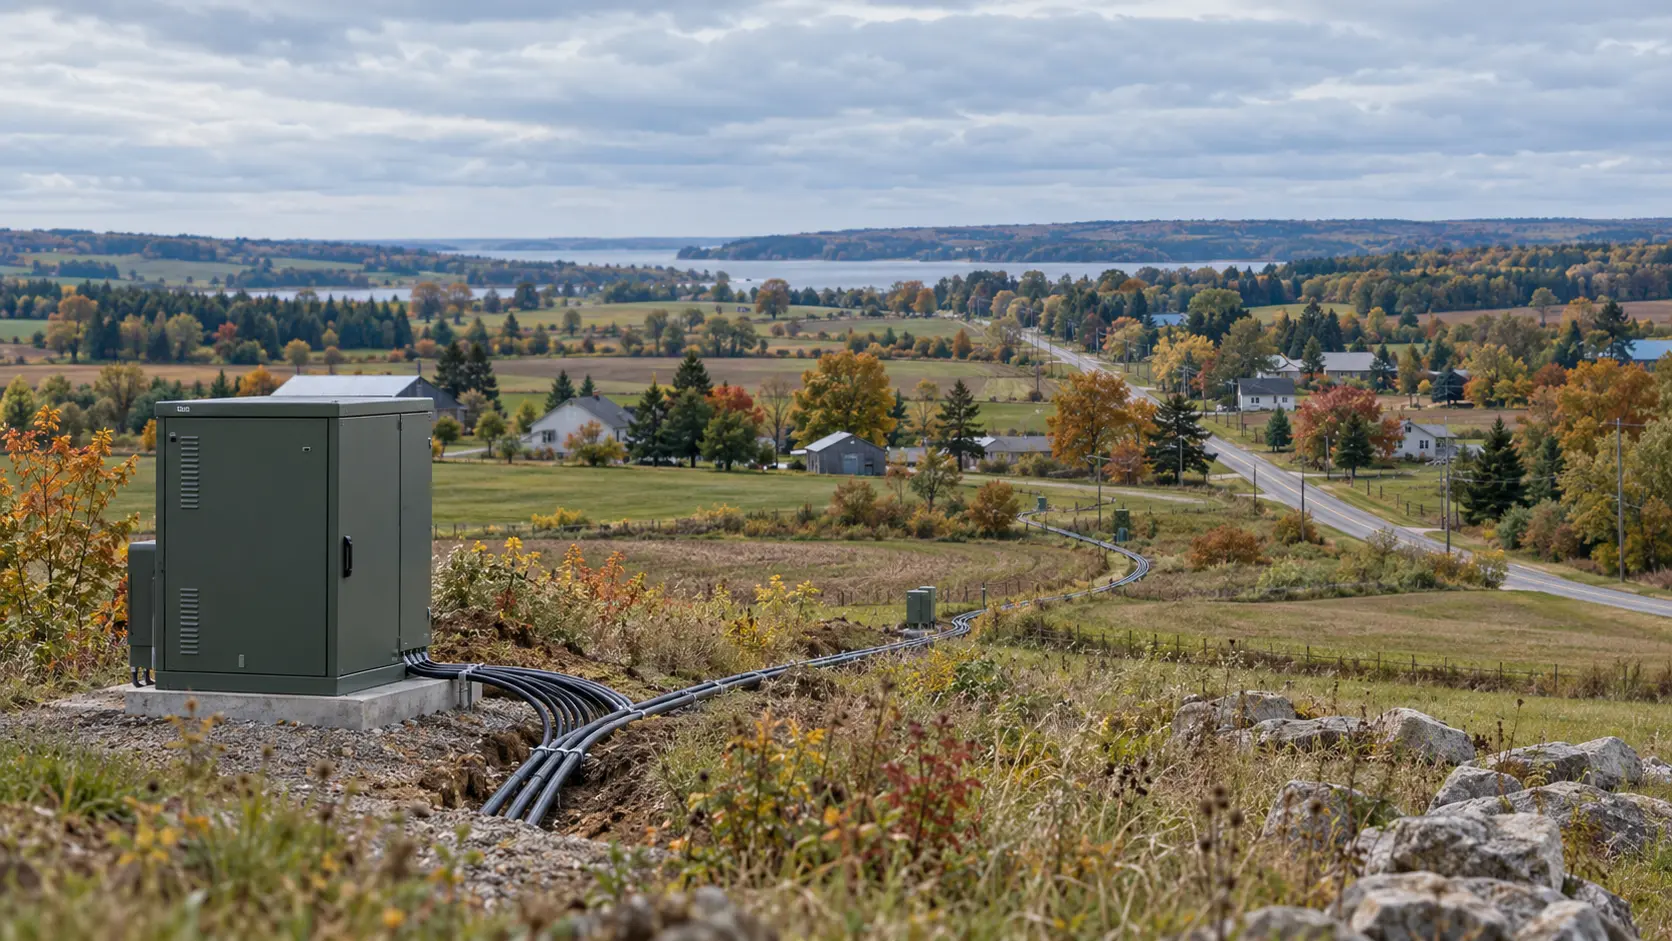
A fibre splice in a roadside enclosure is an unglamorous place to look for competition. Yet that is roughly where a would-be rival can begin on a SWIFT-funded network. The Ontario broadband initiative's interconnection page describes splice points in vaults, pedestals and telecommunications enclosures, with county-level lists and directions to contact the relevant provider.
Those are real starting points. They are not, on their own, a broadband product that another internet provider can order and sell to households. Between a place to connect and a service worth selling lie transport, technical arrangements and a price.
That gap sits behind a March 27, 2026 decision by CRTC. Broadlytics wanted the regulator to apply its aggregated wholesale fibre-to-the-premises rules to all networks funded through SWIFT, alongside an open-access framework and safeguards for asset transfers. The application was denied.
What the public stake actually buys
SWIFT is a non-profit, municipally backed regional initiative that combines public and private investment in southwestern Ontario. The decision describes networks reaching more than 66,000 households and businesses. Reaching them is a substantial achievement; it does not tell us how many have switched supplier or can choose between competing offers.
The ownership arrangement looks powerful at first glance. SWIFT holds a 51% equity interest in the network elements it funds for seven years after each project is completed. The provider builds and operates the network, then receives SWIFT's interest at the end of that period. This is not a majority stake in the provider's company, and there is no single seven-year clock for the whole programme.
Nor does that stake put every recipient into the same regulatory category. Under the 2024 wholesale framework, the aggregated fibre mandate applied to specified large incumbent telephone companies in their traditional territories, with exceptions. It was not a rule for every carrier receiving a subsidy. In the SWIFT case, CRTC identified Bell as the only recipient subject to that mandate and said it had complied through tariffs.
Two ways to hand over a connection
Aggregated access bundles the local connection with transport to a more central handoff. A rival can reach customers through fewer interconnection locations. Disaggregated access leaves more of the transport job to the rival, using more local handoffs. The difference can change the cost and complexity of entering a rural market without changing a metre of the fibre outside a house.
SWIFT's providers were already contractually required to offer disaggregated access. The decision records 4,469 interconnection points. Calling the networks simply “closed” would miss that obligation. Calling the figure 4,469 opportunities for a ready-to-launch retail service would go too far in the other direction. SWIFT's public page describes backhaul access and where to ask about it, not a complete retail-access rate card or proof that each location is economical to use.
The majority found no established breach of the existing policy and insufficient grounds on this record to reopen the wholesale framework. It treated the additional requests about private contractual arrangements as outside its jurisdiction in this proceeding. That was the disposition of this application, not a finding that competition on every funded network was satisfactory.
Commissioner Bram Abramson agreed that the requested legal confirmation had not been established. His partial dissent concerned what should happen next. He wanted a structured inquiry into market power on subsidised local networks and proportionate safeguards: perhaps retail-price constraints, simpler open access or equivalent requirements from a funder. These were options for examination, not orders imposed on SWIFT providers.
There is a useful restraint in that disagreement. Public funding can bring a network to places commercial investment has not reached. Making that network usable by a rival may require a different set of decisions, and rules designed for large carriers may be too cumbersome for small ones. The splice point is a beginning. The competitive offer still has to be built around it.
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance