
Summary
- ServiceTitan reported US$527.4 million of remaining performance obligations, or RPO, at 31 July 2026. About half is expected to be recognised within 12 months and substantially all of the rest by July 2029.
- That measure includes deferred revenue and qualifying non-cancellable contracts, but excludes upsell products as well as payment, financing and other usage fees. It therefore omits important parts of the commercial surface around Max.
- Max enrolled locations more than doubled again in the second quarter, and management now expects more than 700 by fiscal year-end. An enrolled location is an adoption count, not disclosed contract value, live usage or recognised revenue.
- Quarterly revenue rose 21% to US$292.8 million, with subscription revenue up 22% and usage revenue up 24%. Those results establish growth, but ServiceTitan has not published a Max-only bridge to revenue, retention or contribution margin.
- The next useful receipt would connect parent customers and locations to activation, module mix, billing basis, recognised revenue, renewal and incremental cost. Neither RPO nor location count can supply that connection alone.
A sound measure with a visible edge
ServiceTitan’s fiscal second-quarter results give two apparently complementary signs of forward momentum. Remaining performance obligations reached US$527.4 million. Max, the advanced package through which the company is concentrating much of its AI and automation offer, more than doubled its enrolled-location count for a second consecutive quarter and is expected to exceed 700 locations by the end of the fiscal year.
It is tempting to place the two numbers on one line: contracts on one side, adoption on the other, with future revenue sitting between them. The company’s own accounting definitions prevent that shortcut.
RPO is not a loose sales forecast. In ServiceTitan’s Form 10-Q, it is the amount of contracted transaction price that has not yet been recognised as revenue. It includes deferred revenue and non-cancellable contracts whose original duration exceeds one year. Roughly 50% should become revenue during the following 12 months, with substantially all of the remainder expected by 31 July 2029.
That makes RPO a real receipt. Its edge is equally real. ServiceTitan excludes upsell products from the measure. It also excludes payment, financing and other usage fees for which revenue is recognised under the right-to-invoice practical expedient. Nearly all subscription agreements automatically renew in one-year increments rather than operating as multi-year commitments. The balance therefore describes a defined part of future contracted revenue, not the full earning surface of the platform.
The distinction matters more as the product mix changes. ServiceTitan says new-deal volume increasingly includes Max upsells. Core subscription revenue and some other products are recognised ratably over the service term; subscription revenue tied to Max upsells is recognised as billed. FinTech, certain upsells and other products produce usage revenue. A growth initiative can consequently be commercially meaningful while sitting partly beyond RPO.
Seven hundred locations do not equal seven hundred customers
Management’s Max disclosure is precise about its unit and silent about its economics. In the prepared remarks, ServiceTitan says it entered the first quarter with a small base, more than doubled enrolled locations to just over 100, then exceeded its plan to double again in the second quarter. It now expects more than 700 enrolled locations by year-end. Virtual Agents revenue and call volume also more than doubled sequentially, although management described the contribution as early overall.
“Location” is not interchangeable with “active customer”. The investor presentation defines an active customer as a parent organisation that can contain several locations, brands or subsidiaries and that had more than US$10,000 in annualised billings during the relevant period. One customer can therefore generate several enrolled Max locations.
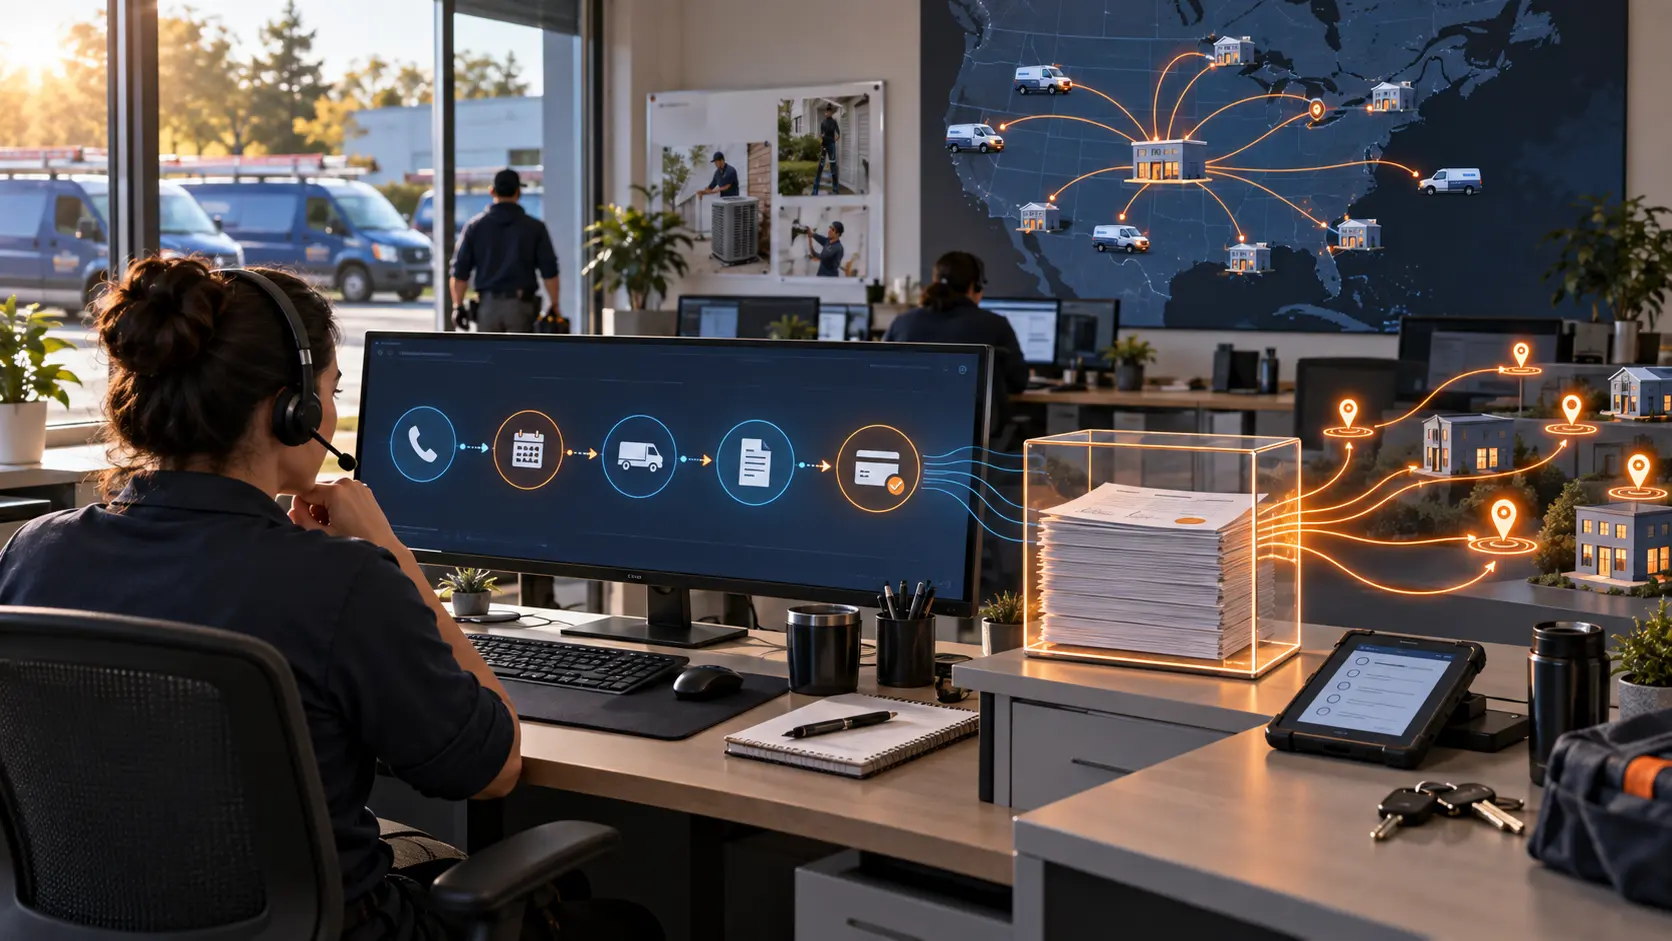
Nor does enrolment reveal operational status. The company’s Max product page describes a package that connects lead generation, call handling, field work, office processes and payment across the lead-to-cash chain. It is in limited release, with existing customers invited to apply. An enrolment might identify a selected location or package commitment; public disclosures do not say whether every enrolled location has activated every module, generates usage, pays the same price or has completed a renewal.
This is not a criticism of the count. Operational programmes need leading indicators before a full revenue cohort matures. It is a constraint on interpretation. More than 700 locations would show distribution through a customer base, not US$700 of anything, 700 contracts or 700 independent buying organisations.
The quarter proves growth, not its Max attribution
ServiceTitan generated US$292.756 million of revenue in the quarter, 21% more than a year earlier. Platform revenue rose 22% to US$284.496 million. Within it, subscription revenue increased 22% to US$212.373 million and usage revenue increased 24% to US$72.123 million. Gross transaction volume reached US$26.8 billion, up 17%.
These are substantial movements. They also demonstrate why a product-level bridge is needed. Usage revenue rose by US$14.150 million, helped by greater GTV and a higher earn rate. Subscription revenue rose by US$37.620 million. The filing does not separate how much of either increase came from Max. AI-related features can influence usage, an upsell invoice or retention without appearing as a distinct reporting line.
Net dollar retention remained above 110%. ServiceTitan calculates that measure from annualised billings, beginning with the same customer cohort a year earlier and incorporating expansion, contraction and churn. Annualised billings itself combines annualised quarterly invoices for Core and upsell subscriptions with the latest quarter’s usage revenue. It is useful evidence that the established cohort expanded in aggregate. It is not a Max retention rate, and it does not turn a quarter of usage into a binding year of revenue.
That boundary protects both sides of the argument. A sceptic cannot conclude that Max lacks revenue merely because it is absent from RPO. An enthusiast cannot assign the company’s 22% subscription growth, 24% usage growth or greater-than-110% retention to Max. The missing item is attribution, not performance.
The margin bridge belongs beside the revenue bridge
GAAP operating loss narrowed to US$27.552 million, or 9.4% of revenue. Non-GAAP operating income was US$44.424 million, a 15.2% margin. Operating cash flow was US$58.0 million and non-GAAP free cash flow was US$50.5 million. ServiceTitan has also presented a long-term non-GAAP operating-margin target of about 25%.
None of those figures is a Max margin. The reconciliation between GAAP and non-GAAP operating results adds back US$48.608 million of stock-based compensation and related payroll taxes, US$13.515 million tied to co-founder performance awards, and US$9.853 million of amortisation. Those adjustments explain most of the US$71.976 million gap between the two measures.
Max can still improve economics. A richer package may lift subscription value; automation may deepen usage; a product spanning marketing, dispatch, field service and payments may reduce churn. It can also require model inference, data work, product support, implementation and sales capacity. A location count does not reveal the incremental gross profit after those costs. The company-wide long-term target is neither a promise about Max nor a substitute for a cohort contribution margin.
A narrower deployment surface can be a control
During the quarter, ServiceTitan narrowed its immediate Max focus. Rather than push into every new trade contemplated earlier, it concentrated on existing commercial trades—mechanical, electrical, plumbing and landscaping—and residential roofing. That decision can improve implementation quality and sales repeatability. It also changes the denominator against which adoption should be read.
The forecast of more than 700 enrolled locations is not penetration of the entire addressable market. The investor deck estimates roughly US$90 billion of trailing-twelve-month GTV among current customers, around US$650 billion in served markets and about US$1.5 trillion in total addressable markets. Those are management estimates at three different levels. The smaller product scope and the broader market estimates should not be blended into one penetration percentage.
A disciplined Max receipt would group locations by parent customer, trade, existing-versus-new customer and activation stage. It would then identify modules enabled, recurring subscription value, usage volume, payment earn rate, invoicing and recognition. Renewal, contraction and service cost would complete the economic line. ServiceTitan need not disclose customer-sensitive detail; consistent cohort ranges would already distinguish distribution from monetisation.
Sources
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance