
Summary
- NMP reported about US$119.8 million in its trust on 4 September, but public holders may redeem and the agreement sends the remaining trust money first to transaction and other closing expenses. Only the residue becomes working capital.
- Closing is not conditioned on a minimum amount of cash or new third-party financing. A legally completed transaction could therefore deliver far less operating liquidity than the trust headline suggests.
- Up to US$82 million of seller debt may remain after the restructuring. Separately, US$75 million of seller preferred stock accrues 9% a year—US$6.75 million for a full year before compounding—and generally pays in additional preferred shares unless the board elects cash.
- At the maximum disclosed retained debt, the arithmetic produces US$318 million of equity consideration and US$243 million of seller common-stock consideration after the preferred layer. These are illustrative contract mechanics, not a forecast of the closing balance.
- GTS's cited US$140 million of 2025 revenue and 12.5% EBITDA margin are unaudited, while EBITDA is unreconciled non-GAAP. The S-4, redemption result, expense statement and final debt documents are the next evidence needed.
The trust is a ceiling, not a cheque
The announcement gives investors a clean sequence of headline amounts. GTS is valued at an implied enterprise value of US$400 million. NMP's trust held approximately US$119.8 million on the agreement date. GTS reported about US$140 million of 2025 revenue. It is tempting to read those figures as price, new cash and operating scale.
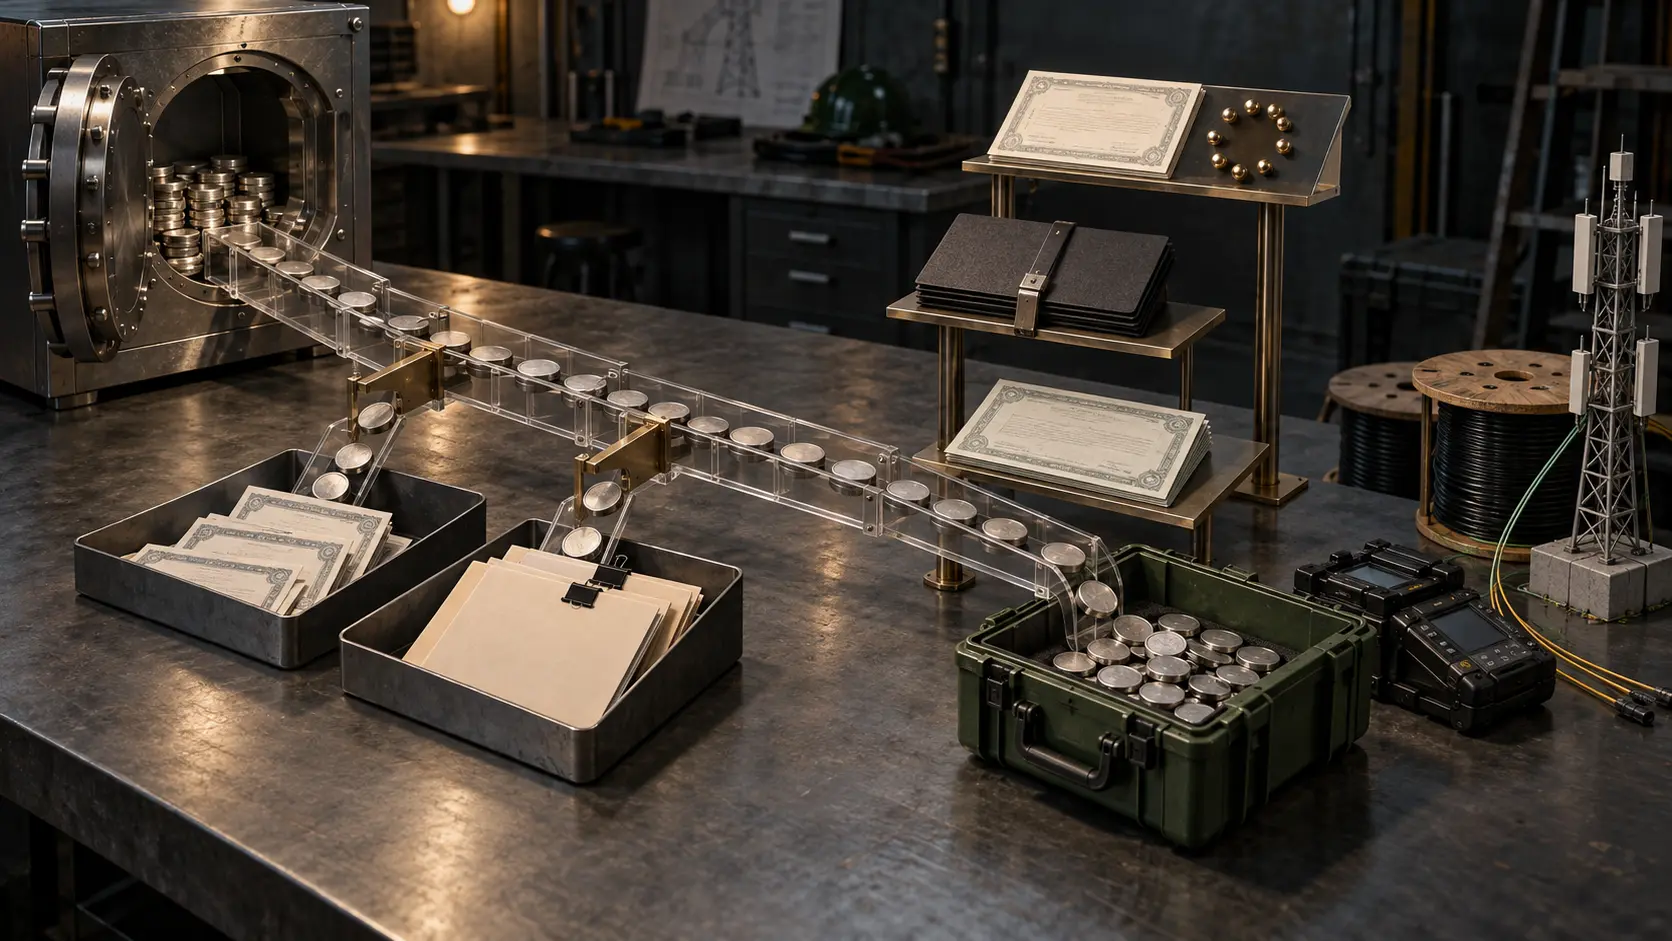
The contract describes a different sequence. Public shareholders receive a redemption opportunity. The trust remaining after redemptions becomes “available trust proceeds.” Those proceeds first pay NMP's accrued and deferred expenses, sponsor loans for transaction or administrative costs, extension expenses and unpaid company expenses at closing. Only what remains after those claims is retained by the combined company as its working-capital reserve.
At 30 June, NMP reported US$119.212 million in trust and only US$106,746 of cash outside it. The September announcement updated the figure to roughly US$119.8 million, but disclosed neither a redemption assumption nor closing-expense estimate.
No minimum cash transfers the uncertainty to day one
Many acquisition agreements make closing conditional on the combined company retaining a specified amount of cash. This agreement does not. It also lacks a condition requiring third-party financing. The parties say GTS's existing liquidity and internally generated cash flows should be sufficient for current operations.
That can help a transaction close despite redemptions. It also means deal completion and a well-funded growth plan are separate tests. GTS says a public listing can support expansion in fibre, wireless densification, data-centre connectivity and future acquisitions. Those ambitions require people, equipment, bonding capacity, receivables finance and the ability to absorb project timing. The agreement does not guarantee that trust proceeds will fund them.
The useful disclosure is the estimate due two business days before closing: trust proceeds after redemptions, closing expenses and the working-capital reserve.
The seller remains a creditor and a preferred holder
The consideration is more layered than an all-stock label suggests. Before closing, debt owed to Streeterville Capital is to be restructured. A US$75 million first-lien secured note and a seller line of credit of up to US$7 million, including accrued interest within the stated aggregate cap, may leave as much as US$82 million outstanding to the seller.
Enterprise value is reduced by this retained seller debt to determine equity consideration. If the retained balance equals the US$82 million ceiling, equity consideration is US$318 million. From that, US$75 million is allocated to preferred stock and US$243 million to common stock. A lower debt balance would change both amounts, so this is a worked example rather than a closing prediction.
The preferred instrument has its own economic clock. Its US$75 million stated value earns 9% annually, or US$6.75 million for a full year before any compounding. Payment generally comes through additional preferred shares unless the board chooses cash. It ranks ahead of common equity in distributions and liquidation, converts initially at US$12 per Class A share, and carries consent rights over debt, asset pledges, certain discounted stock issues and fundamental transactions. After a declared uncured default, the return rises to 12% and the stated value can increase.
The instrument therefore conserves cash when the return is paid in kind, but it does not make the cost disappear. It increases the preferred claim that common holders must sit behind.
Twenty votes make five percent economically small but politically large
After subtracting preferred stock, 95% of the seller's common consideration is issued as Class A and 5% as Class B. The two classes have equal economic rights, but each Class B share carries 20 votes and converts one-for-one into Class A.
The final control percentage cannot be calculated responsibly: redemptions remove cash and continuing public shares, rights convert, retained debt changes seller shares, and a 15% post-closing incentive plan is contemplated. Investors need separate pro forma tables for economic ownership and votes; the 5% Class B allocation alone is misleading.
The valuation inputs still await their audit bridge
The announcement cites approximately US$140 million of 2025 revenue, 36% growth and a 12.5% EBITDA margin. Simple multiplication gives roughly US$17.5 million of EBITDA. Against US$400 million of enterprise value, that is about 2.86 times revenue and 22.9 times EBITDA.
Those ratios are arithmetic, not a verdict. GTS states that the figures are unaudited, may change and that EBITDA is unreconciled. Revenue does not answer cash conversion, customer concentration, backlog quality or working-capital absorption.
The agreement required audited financials on the earlier of 19 September or 15 days after signing unless NMP chose a later date. The subsequent S-4 is meant to carry the financial and pro forma detail needed to connect operating performance, transaction claims and the cash left at closing. Before that filing, precision about leverage or value creation would outrun the evidence.
Sources
- NMP's 8-K filing index for the proposed combination
- NMP Form 8-K describing the transaction structure
- Business Combination Agreement dated 4 September 2026
- Form of Series A preferred-stock certificate
- NMP Form 10-Q for the quarter ended 30 June 2026
- Transaction announcement and unaudited GTS financial measures
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance