
Summary
- Digi signed a US$130 million cash agreement on 1 October to acquire Disruptive Technologies. Regulatory approval is still required; the announcement expected a close before year-end.
- The target reported US$15 million in calendar-2025 revenue and US$4 million in annualized recurring revenue. Digi also says more than 250,000 sensors are deployed, but that count is not a disclosed total of active or subscribed devices.
- Digi expects about US$9 million of additional FY2028 adjusted EBITDA and free cash flow from integration. It is a forecast, not a result, and the release does not give target standalone earnings or a bridge to the forecast.
Analysis
The headline acquisition price is clear; the economic conversion is not. Digi says it will pay US$130 million in cash, financed from its existing revolving credit facility. Dividing that consideration by the target’s US$15 million of 2025 revenue gives about 8.7 times revenue; dividing by US$4 million of ARR gives 32.5 times the reported run rate. Those are arithmetic comparisons, not valuation multiples: the release does not call US$130 million enterprise value, ARR is not revenue recognised during the year, and neither ratio says what the target earns after operating costs.
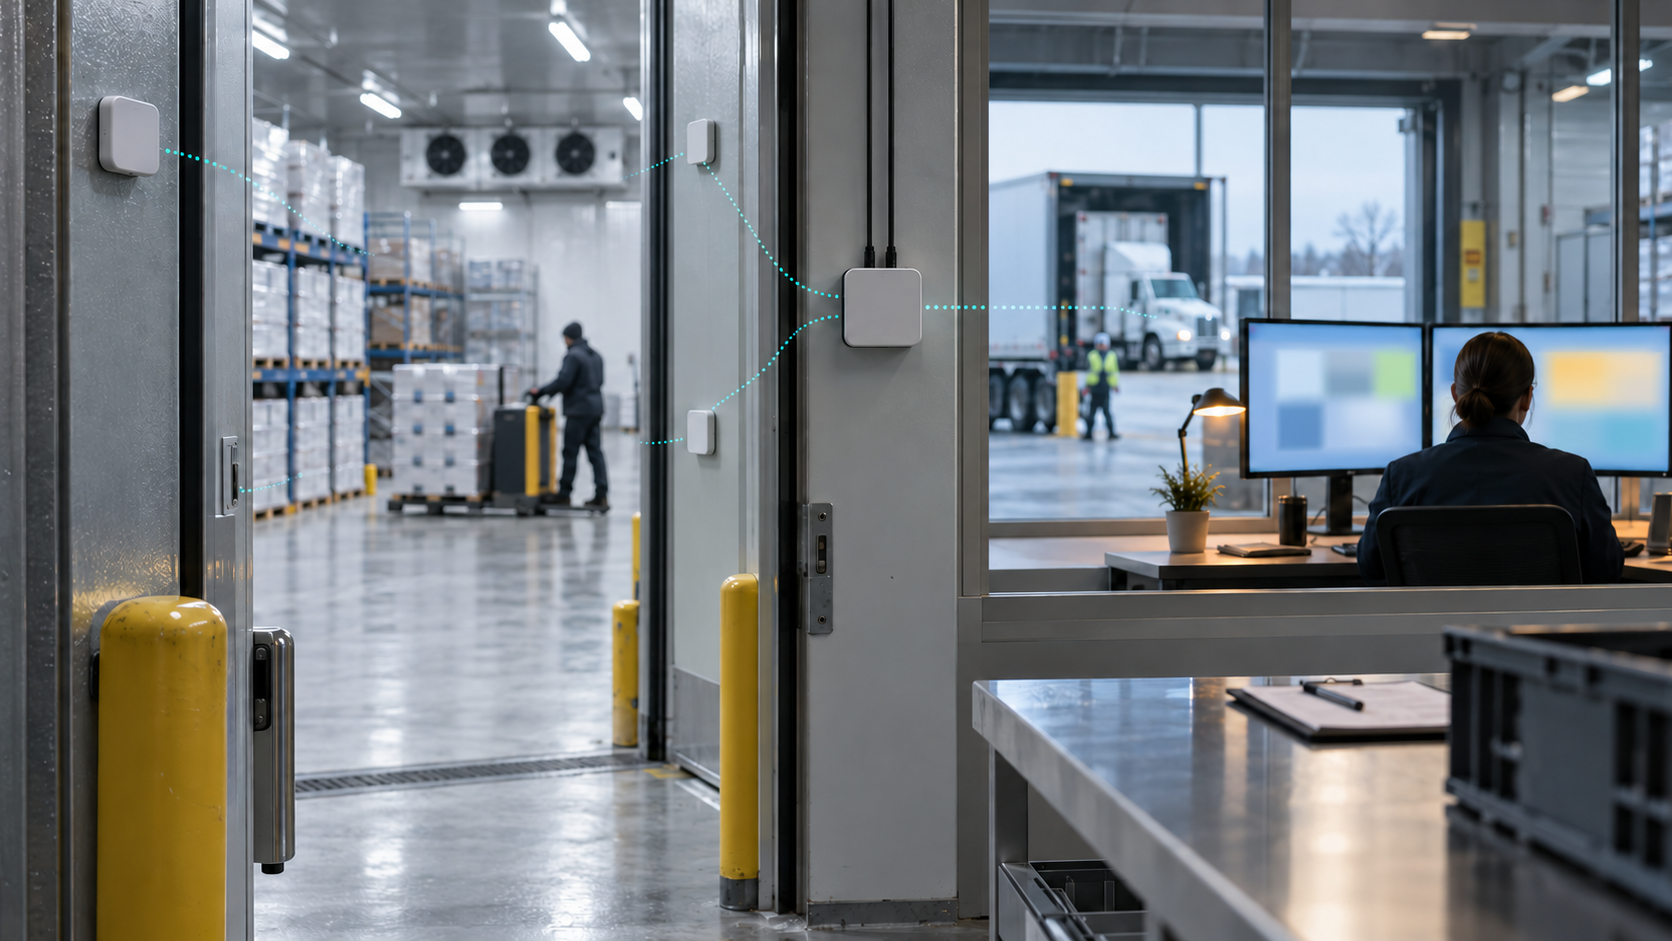
The device base is the strategic starting point, not the subscription base. Digi describes more than 250,000 sensors as deployed and says the products can monitor a broader set of conditions. Its product page advertises battery life of up to 15 years. Long service life can make monitoring useful for years, but it does not tell investors how many installations are active, who pays for them, or how often customers renew. The count cannot substitute for those receipts.
There is a plausible operating fit. Digi’s FY2025 Form 10-K describes SmartSense as sensors, gateways and cloud applications for condition monitoring, employee tasks and supply-chain visibility. It says customers historically paid an annual subscription to monitor sensor data and that SmartSense was moving toward a broader sensing-as-a-service offer. The acquired business therefore adds more sensing options to a model whose value is supposed to continue after installation. That is strategic logic, not proof that the systems, customer contracts or workflows already operate as one product.
Europe is another option with a boundary. Digi calls the deal SmartSense’s first meaningful commercial presence there and points to customer relationships and infrastructure across more than 25 countries. The statement does not quantify European revenue, paying accounts or deployments in each country. It describes a route to market, not market penetration already achieved.
The most useful disclosed checkpoint lies in FY2028. Digi’s 1 October announcement attaches approximately US$9 million to expected FY2028 adjusted EBITDA and free cash flow. The release does not separate the two measures or show how much comes from the target’s existing operations versus integration benefits. Until later reporting supplies that bridge, the forecast is a management target rather than an investment return already earned.
The acquisition’s test is thus narrower than “more sensors” and more demanding than “Europe expansion.” Digi must show that the devices support paid monitoring or task workflows, that customers keep using them, and that the resulting economics appear in reported recurring revenue and cash generation. If the company reports only deployed units, it will have measured reach—not conversion.
Sources
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance