
Summary
- Descartes reported $377 million of cash at 30 April 2026. It then announced approximately $30 million upfront for Drivin on 6 July, $100 million for Tai on 24 August and $120 million for Extensiv on 1 September.
- The $250 million announced total was 66.3% of the old cash snapshot. Subtracting the two produces $127 million mechanically, but not a current balance: post-April operating cash, buybacks, foreign exchange, acquired cash, adjustments and any revolver activity remain outside that arithmetic.
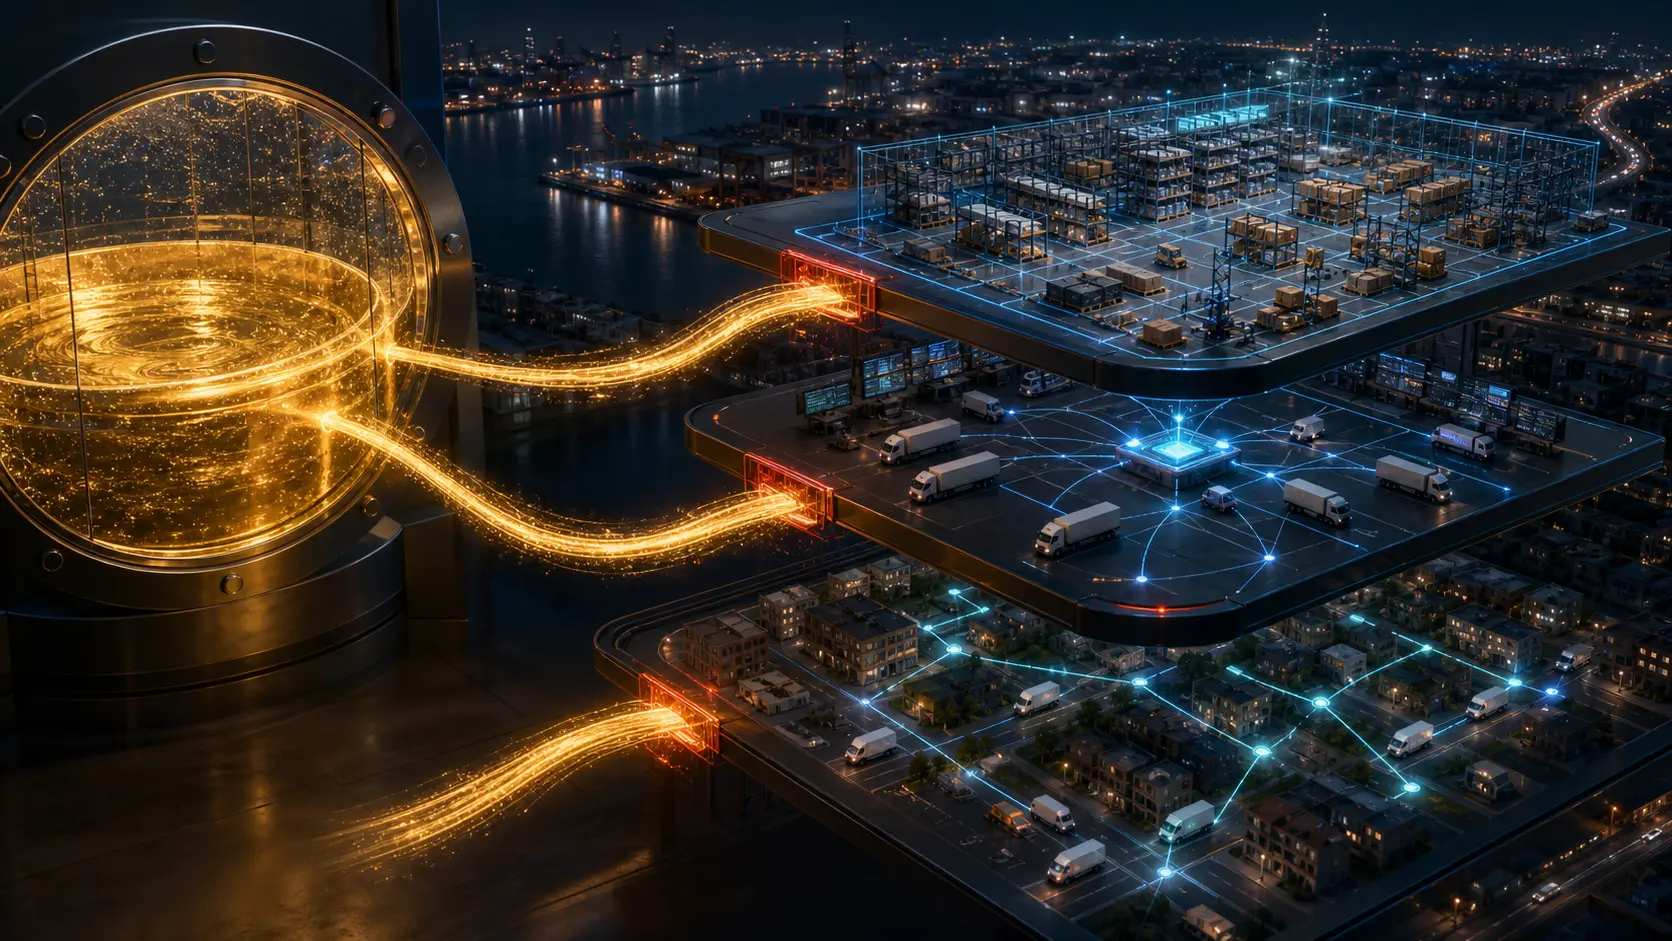
- The acquisitions extend Descartes across three connected control surfaces: last-mile routing and dispatch, freight-broker execution, and 3PL warehouse, inventory, order and billing workflow.
- The next report needs two receipts: a cash-and-debt bridge from 30 April and a revenue bridge that separates inherited acquisition contribution from activity in the pre-deal business.
The arithmetic is easy enough to invite the wrong conclusion. Descartes Systems Group had $377 million of cash on 30 April. After that date, it agreed to pay approximately $30 million upfront for Drivin, $100 million for Tai Software and $120 million for Extensiv. Add the announcements and the result is $250 million. Subtract that from the April balance and the result is $127 million.
Only the first calculation is useful. The $250 million represented 66.3% of the last disclosed cash snapshot, using rounded company figures. The second calculation pretends that a balance sheet stood still while a software company traded for four months. Descartes continued collecting cash, paying employees and suppliers, repurchasing shares and moving money across currencies. Closing statements can also differ from announcement prices because a target brings cash, working-capital adjustments and transaction costs of its own.
The company had a revolving credit facility, but the disclosures frozen for this analysis do not say whether it was drawn for any of the three deals.
So the headline is not that Descartes has $127 million left. It is that a company with a substantial acquisition habit deployed announced consideration equal to about two-thirds of its latest cash reference point in 57 days. That changes what the next set of accounts must explain.
The April balance already had a deal inside it
The 30 April cash number was not a pre-acquisition blank sheet. During the quarter, Descartes used $29.7 million for acquisitions, net of cash acquired. Most of that was Idelic, acquired on 22 April for approximately $25.3 million net of cash. The Idelic announcement had described an upfront price of about $28 million plus as much as $12 million of performance-based consideration expected in fiscal 2028 and 2029.
The two Idelic figures are compatible. One is a rounded gross announcement; the other is the accounting cash outlay after acquired cash. More importantly, Idelic was already reflected in the $377 million balance. Adding it to the post-April $250 million would charge the same deal to both sides of the snapshot.
The quarter's cash bridge shows how quickly a static subtraction loses meaning. Descartes generated $75.1 million from operating activities. It spent $29.7 million net on acquisitions and $2.6 million on capital expenditure. Share issuance added $3.5 million; withholding taxes related to share awards used $4.5 million; buybacks used $20.8 million; and currency movements reduced cash by $0.5 million. Together, subject to rounding, those movements raised cash by $20.5 million from $356.5 million at January-end to $377 million.
Repurchases did not stop neatly at quarter-end. Descartes bought 305,000 shares in Q1 and another 196,800 between 1 May and 2 June. The Q1 disclosure does not give the cash cost for that post-quarter tranche. It is one visible reason why the April balance cannot simply be carried forward.
Three acquisitions form a logistics-control stack
The sequence looks more coherent when the products are placed along an order's physical journey.
Drivin operates near the last mile. Its cloud software plans routes, dispatches fleets, monitors movement and gives delivery visibility, with a strong Latin American footprint. The 6 July announcement put upfront cash at approximately $30 million and added a possible $5 million revenue-based payment expected in fiscal 2029.
Tai sits upstream with the freight broker. Its transportation management system covers quoting, carrier sourcing, load execution, billing and customer engagement. Descartes announced the acquisition on 24 August for approximately $100 million cash.
Extensiv sits where third-party logistics providers receive, store and fulfil goods. Its software covers warehouse inventory, orders, B2B and B2C fulfilment, billing and connections to marketplaces and carriers. Descartes announced approximately $120 million cash on 1 September, explicitly following Tai.
The perimeter now reaches from warehouse records through brokered transport to last-mile execution. That is a control thesis, not proof of integration. The announcements do not establish that customer records already move across the products, that commercial teams cross-sell them, that overlapping modules will be retired or that costs have been removed. The value lies in what Descartes may be able to coordinate; the next evidence must show whether coordination actually occurs.
Available credit is not another cash balance
At 30 April, Descartes reported a $350 million revolving facility with the full amount available. With lender approval, it could be increased to $500 million. That sounds like another reservoir, but liquidity capacity and cash are not interchangeable.
The facility is secured by a first charge over substantially all company assets. Borrowing costs carry a spread of zero to 250 basis points based on consolidated net debt to adjusted EBITDA, while unused availability carries a 20-to-40-basis-point standby fee. A draw would therefore replace cash depletion with a secured liability and a price that rises with leverage. The expansion option is not committed money until lenders approve it.
The correct question is not whether Descartes could finance $250 million. The April snapshot showed both ample cash and undrawn capacity. The question is what mix of cash generated after April, balance-sheet cash, acquired cash and borrowing ultimately funded the closings—and what that mix leaves for further acquisitions, buybacks and operating resilience.
History makes the question material rather than alarming. Descartes used $151.6 million net of acquired cash for subsidiaries in fiscal 2026, $290.2 million in fiscal 2025 and $142.7 million in fiscal 2024. It also paid $34.2 million of contingent consideration during the year ended January 2025: $9.2 million had been recognised at acquisition and $25 million ran through operating cash flow. A headline purchase price can therefore reappear later in a different cash-flow line.
The operating denominator has to catch up
Before the three post-quarter acquisitions entered the accounts, Q1 revenue was $193.6 million, including $180.5 million of services revenue. Adjusted EBITDA was $89.8 million and operating cash flow was $75.1 million. Those figures show a business capable of replenishing liquidity, but they are not a forecast for the months between April and September.
The more revealing Q1 detail is the sequential bridge. Descartes said revenue growth attributable to new and existing customers was only $0.9 million. Drivin, Tai and Extensiv were all outside the period. Once they enter the income statement, total growth alone will no longer reveal how the pre-deal platform is performing.
The next report should therefore identify acquired contribution, integration expenses and acquisition-related amortisation. Changes in deferred revenue and remaining performance obligations can help show whether inherited contracts are expanding the forward book. Contingent consideration should remain separate from upfront cash, especially for Drivin and Idelic. None of these disclosures is needed to prove the deals happened; they are needed to test whether the new control perimeter is earning its keep.
The $250 million ratio is best treated as a disclosure threshold. It is too large relative to the old cash balance to be ignored, yet too incomplete to support a current-liquidity verdict. Descartes has already shown where it wants more control. It now has to show the route by which money and growth moved into that perimeter.
Sources
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance