Summary
- Akamai says multi-year Cloud Infrastructure Services contracts signed during the first half of 2026 were collectively worth more than US$2.8 billion. One new US technology customer committed more than US$600 million over four years for robotics work.
- CIS revenue was US$99.3 million in the June quarter, 39% higher than a year earlier. The contract total is not quarterly revenue, collected cash, deployed capacity or disclosed profit.
- In May, Akamai issued US$3.5 billion of new convertible-note principal and received US$3.453 billion after issuance costs. Only a portion is intended for accelerated CIS capital expenditure; general corporate purposes and share repurchases also sit inside the financing account.
- Second-quarter capex was US$346.5 million, or 32% of revenue, on Akamai’s accrual-basis non-GAAP definition. The figure is company-wide, includes internal-use software and differs from the US$225.8 million cash paid for property, equipment and capitalized software.
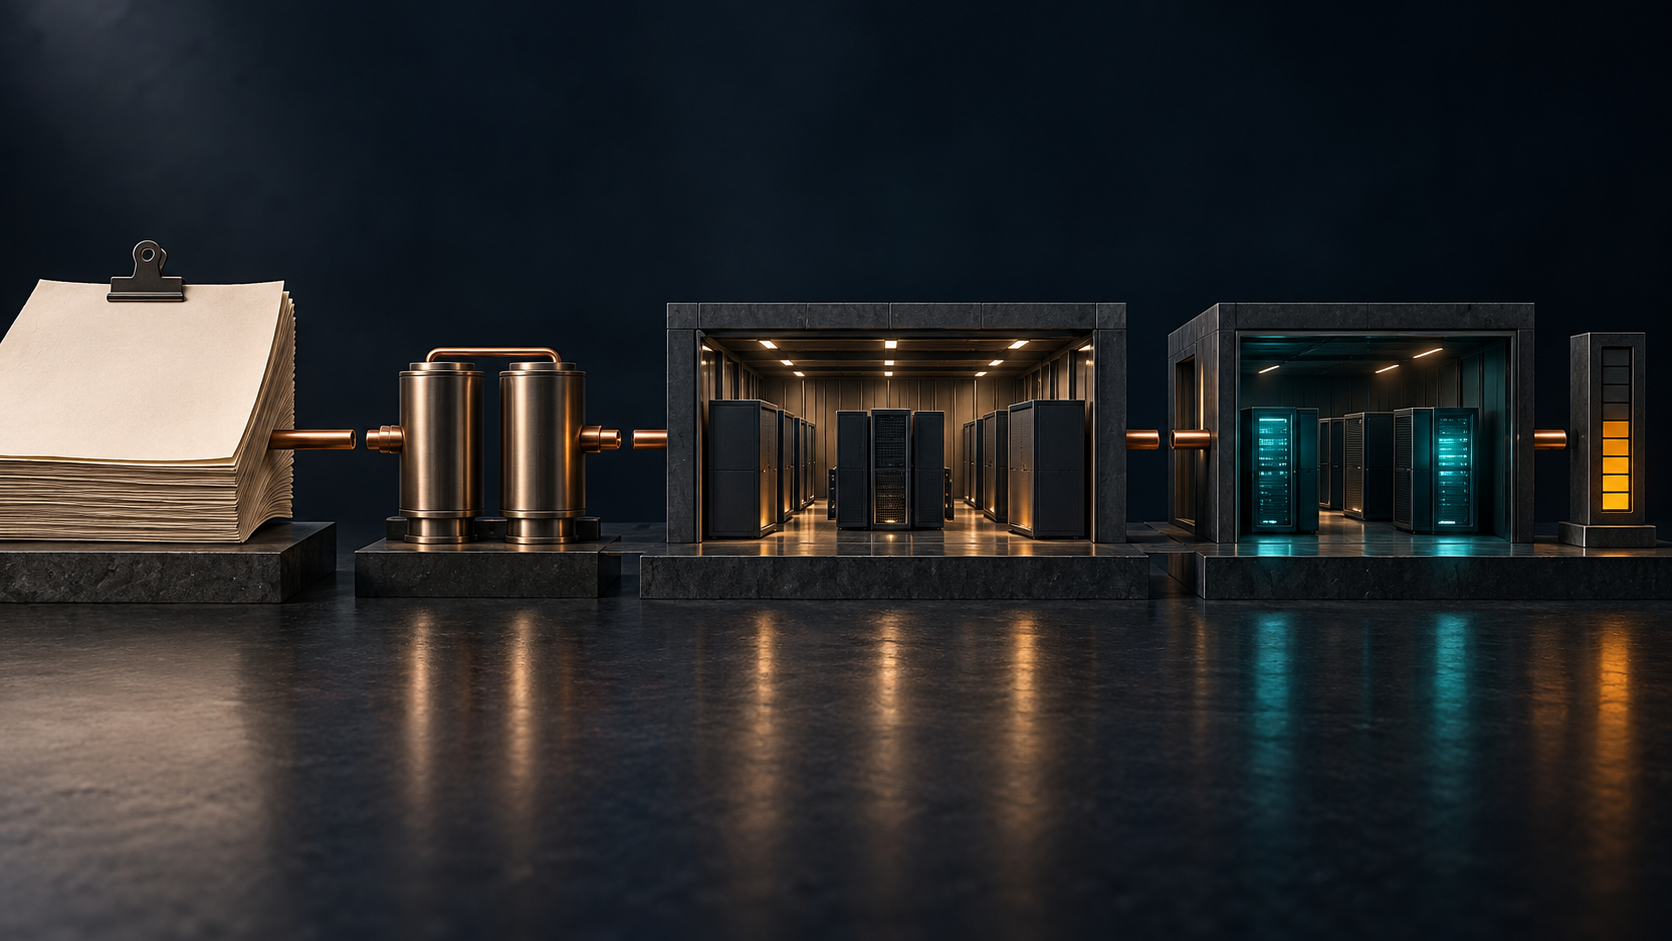
- The useful receipt is a sequence: contract, funding allocation, equipment and site delivery, customer-ready capacity, consumption, revenue recognition, cost absorption, cash and renewal.
A contract headline skips several states
Akamai’s second-quarter release gives investors an unusually large number: numerous multi-year CIS contracts signed year to date were collectively worth more than US$2.8 billion. The announcement also identifies one new, unnamed US technology customer whose four-year commitment exceeds US$600 million and will support robotics development.
Those are real commercial signals. A new customer willing to sign a four-year infrastructure arrangement has made a different decision from a buyer running a short experiment. But “worth” does not say how much capacity is available today, when minimums begin, whether commissioning or acceptance gates apply, how use is scheduled, what termination provisions exist or what gross margin the account can earn.
Dividing US$600 million by four to obtain US$150 million a year would create a smooth schedule the company has not disclosed. The contract could ramp, carry different prices for reserved and burst use, or depend on delivery milestones. None of those possibilities should be asserted as fact. The disclosed fact is the total horizon; the missing receipt is the route through that horizon.
The revenue clock has started, but it is much smaller
CIS produced US$99.319 million of revenue in the June quarter, up 39% from US$71.463 million a year earlier. First-half CIS revenue was US$193.931 million. This growth is important counterevidence to any suggestion that Akamai is financing an infrastructure business without customers. It shows an operating service line already expanding quickly.
It does not reconcile the US$2.8 billion announcement. Akamai reports most services as stand-ready obligations satisfied over time. Revenue is generally recognized ratably as consistent monthly commitments expire, while usage above a commitment is recognized when the units are served. A signature can therefore enter a contractual measure long before its full value appears in revenue; burst demand can appear only when consumed.
The June Form 10-Q reports US$7.6 billion of company-wide remaining performance obligations. Roughly 40% is expected within twelve months, another roughly 40% in years two and three, and the rest later. That balance covers the company’s customer contracts, not just CIS. Akamai does not disclose how the more-than-US$2.8-billion CIS contract total overlaps with RPO, so the two figures cannot be added, substituted or treated as independent backlogs.
US$3.5 billion of notes is a funding pool, not a CIS budget
In May, Akamai issued two new convertible notes: US$1.75 billion due in 2030 and US$1.75 billion due in 2032. The notes have zero coupon rates, and the company received US$3.452749 billion after issuance costs. Akamai says it intends to use a portion of the net proceeds for accelerated capital expenditure supporting CIS and the rapid build-out of its global footprint, while retaining general corporate uses. It also says a portion was used for share repurchases.
The wording matters. The whole US$3.5 billion principal is not a disclosed infrastructure budget. Net proceeds are smaller than principal; note hedges and warrants create separate financing flows; and management retains allocation discretion. The first half included US$615.7 million of repurchases, although the filing does not assign every repurchase dollar to the new notes. Akamai says it expects no more repurchases during 2026 as it invests in CIS.
Zero coupon is not the same as free capital. At 30 June Akamai had US$7.64 billion of convertible-note principal outstanding across five maturities from 2027 to 2033. Conversion conditions, cash settlement, refinancing and eventual dilution remain part of the capital structure. The new notes lengthen the runway for investment, but the economic test is what management buys, when that capacity enters service and what return it earns before the financing calendar closes.
Thirty-two per cent of revenue is an accrual-basis build signal
Akamai’s supplemental accounts put second-quarter capital expenditure at US$346.536 million, up from US$206.337 million in the March quarter and US$214.181 million a year earlier. Capex equalled 32% of Q2 revenue, against 19% in Q1 and 21% in Q2 2025.
The composition was US$261.732 million of property and equipment plus US$84.804 million of capitalized internal-use software. This is Akamai’s non-GAAP, accrual-basis definition. The cash-flow statement instead records US$225.753 million of cash purchases across those two categories. The US$120.8 million gap is mainly a timing difference between amounts accrued but unpaid at quarter-end and cash settlement of current or prior accruals. It is not a hidden saving and should not be subtracted from revenue as though it were an expense.
Nor is the US$346.5 million disclosed as CIS-only capex. It includes the company-wide equipment and internal-software account. The rising number is evidence that Akamai’s investment cycle accelerated; it is not a certificate showing which customer received which servers, in which region, on what date or at what utilization.
The margin receipt comes after the installation receipt
The cost side is already moving. Company-wide Q2 co-location cost rose 14% to US$99.494 million, bandwidth fees rose 17% to US$53.521 million and network build-out and support rose 28% to US$74.415 million. Total cost of revenue increased 14% while total revenue increased 5%. GAAP operating margin fell to 7% from 15%; non-GAAP operating margin fell to 25% from 30%.
These figures cannot be assigned wholly to CIS. Security, delivery and other cloud applications share Akamai’s network and cost base, while stock compensation and other adjustments widen the difference between GAAP and non-GAAP measures. They do show why a contract-value headline is not yet a margin answer. Servers, memory, power, space, bandwidth, software and deployment labour can enter the cost base before customer use has fully ramped.
Akamai itself says hyperscaler demand is increasing server, memory and co-location prices. It expects network build-out and support services to rise as compute partner programmes expand. A 2025 filing also notes that co-location commitments can be expensed before a compute location is fully utilized. The operating sequence therefore has an absorption interval: installed capacity may be customer-ready while revenue is still catching up.
Liquidity provides useful counterweight. Akamai generated US$326.266 million of operating cash in Q2 and ended June with US$4.616 billion of cash and marketable securities. Free cash flow under its definition was US$100.513 million after cash-basis equipment and internal-software purchases. This is not a liquidity-crisis story. It is a capital-allocation story in which strong financing and cash generation still have to be converted into account-level service economics.
Sources
Member Briefing
Deeper Profile Context
Sign in with the right membership level to unlock the full briefing and source notes.
Only for Strategic Circle
Strategic Circle
Open to all readers. Unlock profile briefings after joining and signing in.
Join Strategic CircleOnly for Leadership Alliance
Leadership Alliance
For qualified IP-asset owners and management; sign in to unlock alliance briefings.
Join Leadership Alliance